Tag: alternative credit data
Download our case study to learn how home equity lender, Spring EQ, leveraged Experian Boost to help applicants qualify for better loan rates and terms.
Historically, economic hardships have directly impacted loan performance. Are you prepared to navigate and successfully respond to the current environment?
Learn the benefits of leveraging alternative credit data to better assess risk at the onset of the loan decisioning process. Read more.
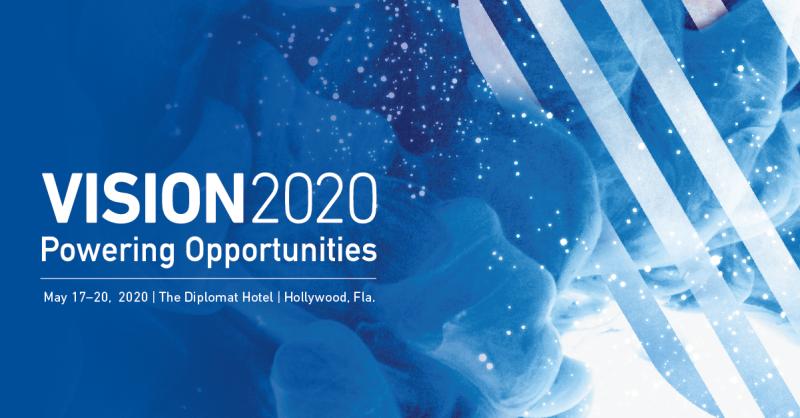
If you're looking for a competitive edge in 2020, Vision is your ticket into differentiating your organization with the latest insights and innovation.
Exploring some of the top trends for the financial services industry going into the new decade from data and decisioning to fraud and customer experience.
As we prepare for the excitement and challenges of a new decade, the same can be true for how we approach the use of alternative data. Read more!
The DMV is embracing technology to improve overall customer experience, and financial institutions can benefit from doing the same.
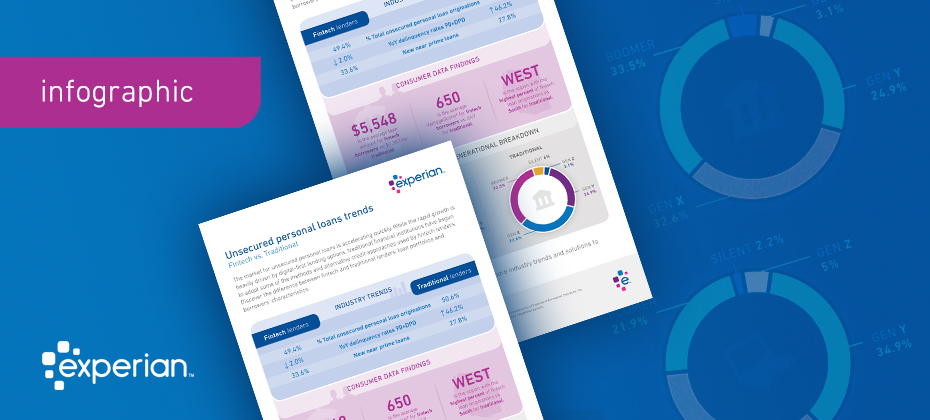
How are fintechs faring against traditional FIs? Our latest infographic uncovers industry trends and key metrics in unsecured personal installment loans.
It’s important for lenders to get a comprehensive view to find the most qualified candidates. Using alternative credit data can expand your choices.
Alex Lintner, Group President at Experian, recently had the chance to sit down with Peter Renton, creator of the Lend Academy Podcast, to discuss alternative credit data,1 UltraFICO, Experian Boost and expanding the credit universe. Lintner spoke about why Experian is determined to be the leader in bringing alternative credit data to the forefront of the lending marketplace to drive greater access to credit for consumers. “To move the tens of millions of “invisible” or “thin file” consumers into the financial mainstream will take innovation, and alternative data is one of the ways which we can do that,” said Lintner. Many U.S. consumers do not have a credit history or enough record of borrowing to establish a credit score, making it difficult for them to obtain credit from mainstream financial institutions. To ease access to credit for these consumers, financial institutions have sought ways to both extend and improve the methods by which they evaluate borrowers’ risk. By leveraging machine learning and alternative data products, like Experian BoostTM, lenders can get a more complete view into a consumer’s creditworthiness, allowing them to make better decisions and consumers to more easily access financial opportunities. Highlights include: The impact of Experian Boost on consumers’ credit scores Experian’s take on the state of the American consumer today Leveraging machine learning in the development of credit scores Expanding the marketable universe Listen now Learn more about alternative credit data 1When we refer to "Alternative Credit Data," this refers to the use of alternative data and its appropriate use in consumer credit lending decisions, as regulated by the Fair Credit Reporting Act. Hence, the term "Expanded FCRA Data" may also apply in this instance and both can be used interchangeably.
The 2019 report reveals new consumer and lending insights, an overview of the regulatory landscape, and what's next for machine learning and alt data.

Millions of consumers lack credit history and/or have difficulty obtaining credit from mainstream financial institutions. To ease access to credit for “invisible” and below prime consumers, financial institutions have sought ways to both extend and improve the methods by which they evaluate borrowers’ risk. This initiative to effectively score more consumers has involved the use of alternative credit data.1 Alternative credit data is FCRA-compliant data that is typically not included in a traditional credit report and is used to deliver a more complete view into a consumer’s creditworthiness. “Alternative credit data helps us paint a fuller picture of a consumer so they can get better access to the financial services they need and deserve,” said Alpa Lally, Vice President of Data Business at Experian. Experian recently sponsored the FinovateSpring conference in San Francisco, where Alpa had a chance to sit down with Jacob Gaffney, Editor-in-Chief of the HousingWire News Podcast, to discuss ways consumers can improve their credit scores. As an immigrant, Alpa spoke personally about the impact of having a limited credit history and how alternative credit data can help drive greater access to credit for consumers and profitable growth for lenders through more informed lending decisions. Highlights include: How alternative and traditional credit data differ Types of alternative credit data being used by lenders How “credit-invisibles” can best leverage alternative credit data Alternative credit data product solutions, including Experian BoostTM Listen now 1When we refer to “Alternative Credit Data,” this refers to the use of alternative data and its appropriate use in consumer credit lending decisions, as regulated by the Fair Credit Reporting Act. Hence, the term “Expanded FCRA Data” may also apply in this instance and both can be used interchangeably.
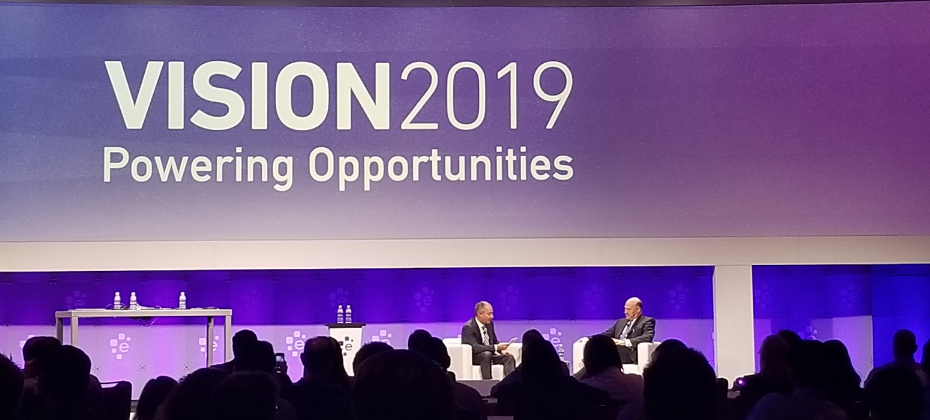
Day 1 of Vision 2019 kicked off with remarks from the CEO, Group President, and a keynote by Gary D. Cohn, Former Director of the U.S. Economic Council.
Experian's annual thought leadership conference will be held May 5-8 in San Antonio Texas, and will feature 50+ sessions on the industry's latest trends.
We’ve rounded up what it takes for consumers to have a good credit score, in addition to some alternative considerations. Read more!