Tag: alternative data
Fintechs have been an enormously disruptive force of change in financial services over the past 10 years. From digital payments, lending, insurance, digital banks, to personal finance and many other subsectors in between, fintechs have rapidly transformed everything from business and operating models to customer expectations. It’s this innovative drive that is celebrated and fostered each year at LendIt Fintech - a conference that brings together the fintech and financial services community to connect and reimagine the future of finance. And there may not be another year on record that called for the reimagining of finance more than 2020. Last year, the financial services industry – from consumers, fintechs and other subdivisions across the globe – endured many changes and challenges due to the COVID-19 pandemic. But it also brought accelerated innovations; and with them, increased customer expectations and a focus on financial equity and inclusion. As consumer credit scores and demand for credit continue to rise, fintechs have an opportunity to re-examine what credit looks like in a post-COVID lending environment, and explore opportunities for growth in 2021. Experian’s Chief Product Officer Greg Wright tackled this topic at the recent Lendit Fintech conference, alongside Ibo Dusi of Happy Money, Myles Reaz of Upgrade and the Garry Reeder with the American Fintech Council. Watch the full panel discussion in the video below and hear more about: How panelists define data, alternative data and how it factors in their lending How alternative data can help drive financial inclusion and get to a ‘yes’ more often with consumers Using data to make the consumer experience more frictionless and seamless For more information about how Experian can help fintech organizations of all sizes reach their business and lending goals, visit our fintech solutions page. Explore Experian's Fintech Solutions
The jump to the cloud means that lenders are suddenly more capable than ever at making analytically sound and more financially inclusive decisions.

Download our report to learn why alternative credit data is supplemental and essential to consumer lending and how it’s being used by consumers and FI's.
In our most recent podcast, Experian experts discuss how to enhance your portfolio analysis after an economic downturn and drive greater access to credit.
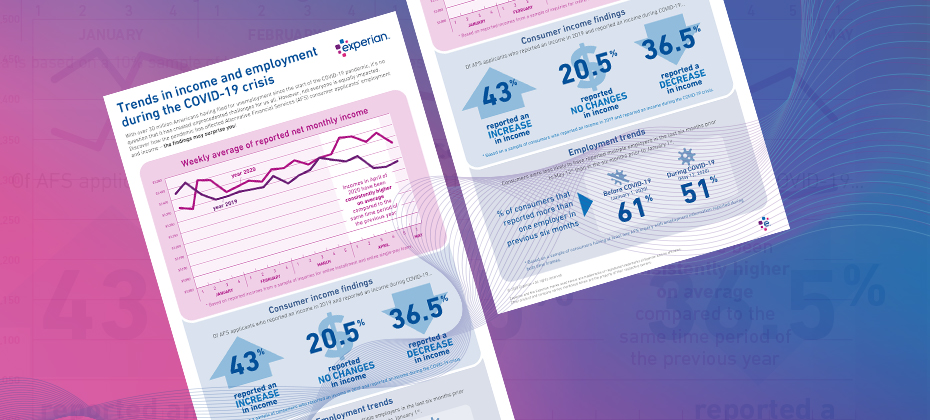
COVID-19 has had far-reaching economic consequences. When it comes to your consumers' finances, are you seeing the full picture?
COVID-19 will affect the way financial institutions lend and provide credit. See what Shawn Rife, Experian’s Director of Product Scoring, had to say.
Learn the benefits of leveraging alternative credit data to better assess risk at the onset of the loan decisioning process. Read more.
Since the end of the recession, customer loyalty has been a focus for lenders, given that there are more options for AFS borrowers. Read more!
As we prepare for the excitement and challenges of a new decade, the same can be true for how we approach the use of alternative data. Read more!
The DMV is embracing technology to improve overall customer experience, and financial institutions can benefit from doing the same.
It’s important for lenders to get a comprehensive view to find the most qualified candidates. Using alternative credit data can expand your choices.
Alex Lintner, Group President at Experian, recently had the chance to sit down with Peter Renton, creator of the Lend Academy Podcast, to discuss alternative credit data,1 UltraFICO, Experian Boost and expanding the credit universe. Lintner spoke about why Experian is determined to be the leader in bringing alternative credit data to the forefront of the lending marketplace to drive greater access to credit for consumers. “To move the tens of millions of “invisible” or “thin file” consumers into the financial mainstream will take innovation, and alternative data is one of the ways which we can do that,” said Lintner. Many U.S. consumers do not have a credit history or enough record of borrowing to establish a credit score, making it difficult for them to obtain credit from mainstream financial institutions. To ease access to credit for these consumers, financial institutions have sought ways to both extend and improve the methods by which they evaluate borrowers’ risk. By leveraging machine learning and alternative data products, like Experian BoostTM, lenders can get a more complete view into a consumer’s creditworthiness, allowing them to make better decisions and consumers to more easily access financial opportunities. Highlights include: The impact of Experian Boost on consumers’ credit scores Experian’s take on the state of the American consumer today Leveraging machine learning in the development of credit scores Expanding the marketable universe Listen now Learn more about alternative credit data 1When we refer to "Alternative Credit Data," this refers to the use of alternative data and its appropriate use in consumer credit lending decisions, as regulated by the Fair Credit Reporting Act. Hence, the term "Expanded FCRA Data" may also apply in this instance and both can be used interchangeably.
The 2019 report reveals new consumer and lending insights, an overview of the regulatory landscape, and what's next for machine learning and alt data.
Earlier this month, Experian joined FinovateSpring in San Francisco, CA to demonstrate innovations impacting financial health to over 1,000 attendees. The Finovate conference promotes real-world solutions while highlighting short-form demos and key insights from thought-leaders on digital lending, banking, payments, artificial intelligence and the customer experience. With more than 100 million Americans lacking fair access to credit, it's more important than ever for companies to work to improve the financial health of consumers. In addition to the show's abundance of fintech-centered content, Experian hosted an exclusive, cutting-edge breakout series demonstrating innovations that are positively impacting the financial health of consumers across the nation. Finovate Day One Overview While fintechs, banks, venture capitalist, entrepreneurs and industry analysts ascended on the general conference floor for a fast-paced day of demos, a select subset gathered for a luncheon presented by Experian North America CEO, Craig Boundy, and Group President, Alex Lintner. Attendees were given an in-depth look at new, alternative credit data streams and tools that are helping to increase financial access. Demos included: Experian Boost™: a free, groundbreaking online platform that allows consumers to instantly boost their credit scores by adding telecommunications and utility bill payments to their credit file. More than half a million consumers have leveraged Experian Boost, increasing their score by an average of 13 points. Cumulatively, Experian Boost has helped add more than 2.8 million points to consumers’ credit scores. Ascend Analytical Sandbox™: A first-of-its-kind data and analytics platform that gives companies instant access to more than 17 years of depersonalized credit data on more than 220 million U.S. consumers. It has been the most successful product launch in Experian’s history and recently earned the title of “Best Overall Analytics Platform” at this year’s Fintech Breakthrough Awards. Alternative Credit Data: Comprised of data from alternative credit sources, this data helps lenders make smarter and more informed lending decisions. Additionally, Experian’s Clear Data Platform is next-level credit data that adds supplemental FCRA-compliant credit data to enrich decisions across the entire credit spectrum. This new platform features alternative credit data, rental data, public records, consumer-permissioned data and more Upon conclusion of the luncheon, Alpa Lally, Experian’s Vice President of Data Business at Consumer Information Services, was interviewed for the HousingWire Podcast with Jacob Gaffney, HousingWire Editor in Chief, to discuss how new forms of data streams are helping improve consumers’ access to credit by giving lenders a clearer picture of their creditworthiness and risk. “Alternative credit data is different than traditional credit data and helps us paint a fuller picture of the consumer in terms of their ability to pay, willingness to pay and stability. It helps consumers get better access overall to the credit they deserve so that they can actively participate in the economy,” said Lally. Finovate Day Two Overview On the last day of the conference, expert speakers took to the main stage to analyze the latest fintech trends, opportunities and challenges. Alex Lintner and Sandeep Bhandari, Chief Strategy Officer and Chief Risk Officer at Affirm, participated in a fireside chat titled “Improving the Financial Health of America’s 100 Million Credit Underserved Consumers.” Moderated by David Penn, Finovate Analyst, the session explored the latest innovations, trends and technologies – from machine learning to alternative data – that are making a difference in positively impacting the financial health of Americans and expanding financial opportunities for underserved consumers. The panel discussed the efforts made to put financial health at the center of their business and the impact it’s had on their organizations. Following the fireside chat, Experian hosted a second lunch briefing, presented by Vijay Mehta, Chief Innovation Officer, and Greg Wright, EVP Chief Product Officer. The lunch included exclusive table discussions and open conversations to help attendees leave with a better understanding of the importance of prioritizing financial health to build trust, reach new customers and ultimately grow their business. "We are actively seeking out unresolved problems and creating products and technologies that will help transform the way businesses operate and consumers thrive in our society. But we know we can't do it alone," Experian North American CEO, Craig Boundy said in a recent blog post on Experian's fintech partnerships and Finovate participation. "That's why over the last year, we have built out an entire time of account executives and other support staff that are fully dedicated to developing and supporting partnerships with leading fintech companies. We've made significant strides that will help us pave the way for the next generation of lending while improving the financial health of more people around the world." For more information on how Experian is partnering with fintechs, visit experian.com/fintech or read our recent blog article on consumer-permissioned data for an in-depth discussion on Experian BoostTM.
Learn four ways fintech has changed the lending process and how traditional financial institutions and lenders can keep up. Read more!