Tag: VantageScore
To maximize limited marketing spend, lenders will need to be more prescriptive to increase response rates on fewer delivered offers.
To improve results within the subprime space, lenders need to have a well-established pre-delinquent contact optimization approach. Read more!
Learn how to accurately and consistently report on consumers' credit while complying with regulatory guidance during the COVID-19 pandemic.
Since the end of the recession, customer loyalty has been a focus for lenders, given that there are more options for AFS borrowers. Read more!
An Experian study revealed 86% of millennials believe that buying a house is a good financial investment - they just don't have the credit scores they need.
Later this year, FICO will retire its Score V1, making it mandatory for those lenders still using the old software to find another solution.
Recent analysis of the personal loan market revealed a 9-pnt negative shift in the avg VantageScore® credit score for personal loan originations from Q3 to Q4 of '16.
Personal loans have been booming for the past couple of years with double-digit growth year-over-year. But the party can’t last forever, right? In a recent Experian webinar, experts noted they have seen originations leveling off. In fact, numbers indicate it’s gone from leveled off to a slight year-over-year decline. They projected the first quarter of calendar year 2017 may also be down, but then we’ll see a peak again in the second quarter, which is typical with the seasonality often associated with personal loans. The landscape is changing. A recent data pull revealed a 9-point shift in the average VantageScore® credit score for originations from Q3 to Q4 of 2016. Lenders are digging deeper in order to keep their loan volumes up, and it is definitely a more competitive marketplace. The days where lenders were once able to grow their personal loan business with little effort are gone. Kelley Motley, Experian’s director of analytics, noted some of the personal loan origination volume shifts may be due to the rebound in the housing market and increased housing values, enabling super-prime and prime consumers to now also consider home equity loans and lines of credit, in lieu of personal loans. Still, the personal loan market is healthy. Lenders just need to be smart about their marketing efforts and utilize data to improve their response rates, expand their risk criteria to identify consumers trending upward in the credit ranks, and then retain them as their cash-flow and financial situations evolve. In the presentation, experts revealed a few interesting stats: 67% of those that open a personal installment loan had a revolving trade with a balance >$0 5% of consumer that close a personal loan reopen another within a few months of the original loan closure 68% of consumers that re-open a new personal loan within a short timeframe of closing another personal loan do so with the same company Together, these stats illustrate that individuals are largely leveraging personal loans to consolidate debt or perhaps fund an expense like a vacation or an unexpected event. Once the consumer comes into cash, they’ll pay off the loan, but consider revisiting a personal loan again if their financial situation warrants it. The calendar year Q2 peak has been consistent since the Great Recession. For many consumers, after racking up holiday debt and end-of-year expenses, the bills start coming in during the first quarter. With the high APRs often attached to revolving cards, there is a sense of urgency to consolidate and lock in a more reasonable rate. Others utilize the personal loan to fund weddings, vacations and home improvement projects. Kyle Matthies, a senior product manager for Experian, reminded participants that most people don’t need your product, so it’s essential to leverage data find those that do. Utilizing propensity score and attributes, as well as tools to dig into ability-to-pay metrics and offer alignment can really fine-tune both an organization’s marketing and retention strategies. To learn more about the current state of personal loans, access our free webinar How lenders can capitalize on the growth in personal loans.
VantageScore found consumers rendered “unscoreable” by commonly used credit scoring models are nearly identical financial/credit behavior to scoreables
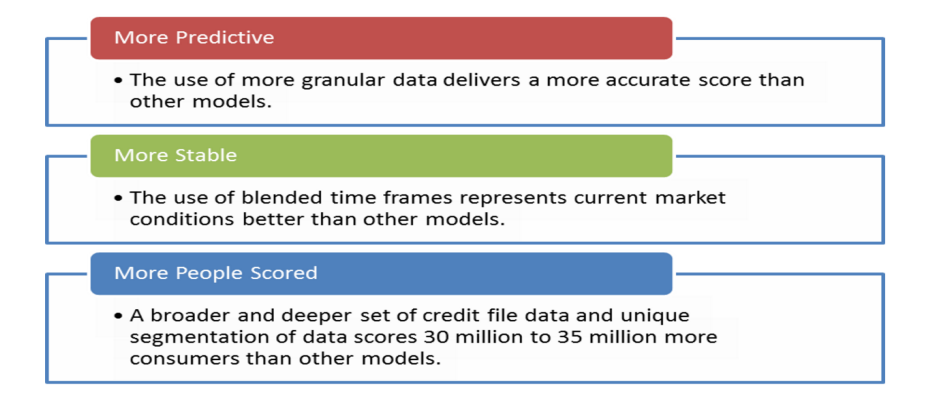
More lenders are turning to VantageScore® to help achieve their goals and reduce risk
As credit behavior and economic conditions evolve, using a model that's validated regularly can give lenders greater confidence in the model’s performance.
A recent survey commissioned by VantageScore® Solutions, LLC found that among consumers who are unable to obtain credit, 27% attribute the situation to lack of a credit score. Most consumers support newer methods of calculating credit scores 49% feel that consistent rental, utility and telecommunications payments should count in determining credit scores 50% agree that competition in the credit scoring marketplace is beneficial Lenders can help solve the credit gap by using advanced risk models that can accurately score more consumers. The result is a win-win: More consumers get access to mainstream credit, and lenders gain more customers. >> Infographic: America’s Giant Credit Gap VantageScore® is a registered trademark of VantageScore Solutions, LLC.
Experian® recently released the 2015 State of Credit report, which analyzes key credit metrics across the nation.
According to a recent survey commissioned by VantageScore® Solutions, millennials cite being unscoreable as the main obstacle to credit access. Among the findings: One-third of millennials cannot obtain the credit they need Of those unable to obtain credit, 34% attribute it to lack of a credit score 49% of millennials agree that competition in the credit-scoring marketplace is beneficial Lenders can help this segment and open the gateway of credit by using advanced risk models that can accurately score consumers considered unscoreable by conventional risk models. >> Infographic: The Giant Credit Gap VantageScore® is a registered trademark of VantageScore Solutions, LLC.
VantageScore® models are the only credit scoring models to employ the same characteristic information and model design across the three credit bureaus.