According to new research from Experian Marketing Services, a recognized leader in data-driven marketing, 90 percent of marketers struggle to move beyond single-channel marketing programs to optimize their marketing across channels or around the customer. The company today announced an expansion of its strategic, cross-channel consulting offerings to address this need and help organizations increase the sophistication and effectiveness of their marketing programs. Marketers can now take a free online assessment to discover where their organization falls on Experian’s Marketing Sophistication Curve The new program, which offers marketers strategic guidance around common marketing pain points, is designed to help them progress up Experian’s Marketing Sophistication CurveSM. The curve is a framework and road map that allows organizations to accurately assess the state of their marketing operations and identify the steps necessary for creating individualized marketing experiences around the customer. “Recognizing the need to change and knowing how to make that happen are two entirely different things,” said Matt Seeley, president, Experian Marketing Services, North America. “While the industry is exploding with marketing clouds and automation technology, most organizations have unique challenges that off-the-shelf software doesn’t address. Experian’s Marketing Sophistication Curve offers marketers help with the first critical step in that process: an understanding of where you are today and what you need to do tomorrow.” Experian Marketing Services is offering marketers a chance to identify where they fall on the curve on its Website. The four phases of Experian’s Marketing Sophistication Curve The culmination of more than 30 years of experience working with the world’s top brands to improve their marketing effectiveness, Experian’s Marketing Sophistication Curve outlines four primary phases of marketing sophistication: Phase I: Single-Channel Optimization — Brands at this stage seek new sources of data and analytical approaches to do more with existing programs and tools. They struggle to achieve a higher performance from data-driven campaigns. Phase II: Multichannel Marketing — Organizations at this stage engage customers across multiple channels but seek greater consistency. They struggle to incorporate newer channels, like mobile, into their messaging strategy. Phase III: Cross-Channel Marketing — The marketing organization at this stage implements cross-channel marketing programs but struggles to organize data and target campaign content around customers easily, consistently and in useful time frames. Phase IV: Cross-Channel Optimization — This is the apex of modern marketing, where customer context, location and timing merge with every imaginable form of customer data to create a single, shared and immediate view of the customer across all channels. Improving marketing by addressing the common pain points Experian Marketing Services’ new cross-channel consulting program offers marketers a set of new bundled offerings around three common pain points that must be addressed as marketers move from one phase of the curve to the next: acquisition, growth and retention, and win-back. “As new technologies and channels are introduced, consumer behavior changes, and in return how we assess and approach these traditional marketing issues needs to evolve,” continued Seeley. “The curve’s framework and the addition of the new strategic consulting bundles to our existing portfolio are part of our long-term commitment to be both a superior marketing technology provider and a strategic partner for leading marketers around the world.”
Experian Consumer Services in association with Univision Communications Inc., the leading media company serving Hispanic America, recently launched a Spanish-language, credit-focused product and online financial resource center for the U.S. Hispanic community called Crédito y Más. The new product was developed to improve Hispanics access to credit education and resources. With Crédito y Más, consumers can check their credit score, receive a credit report, and have credit monitoring, among other benefits and access the information in Spanish or English. One of the most valuable features is the Centro de Información™, a robust resource center with articles, videos, financial calculators, a glossary of key credit terms and more.
How can I improve my credit score? That’s a question thousands of consumers ask Experian every day. This question is asked even more frequently now that lenders are sending an estimated 120 million credit-score disclosures each year to consumers when they are denied credit or are offered terms that are less favorable than those offered to others. These score disclosures provide consumers with basic information about the score used in a transaction and direct them to the national credit bureaus if they have any questions. However, when consumers ask Experian how they can improve their credit standing, it’s difficult to respond in an easy and consumer-friendly way. The difficulty arises because, although we want to help, the Credit Repair Organizations Act (CROA) puts substantial roadblocks between credit bureaus and consumers.
Related Posts
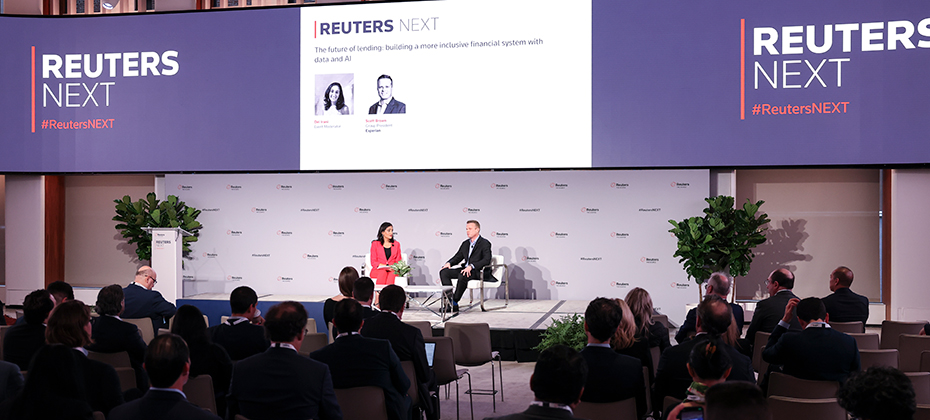
Today, we stand at the forefront of a digital revolution that is reshaping the financial services industry. And, against this backdrop, financial institutions are at vastly different levels of maturity; the world’s biggest banks are managing large-scale infrastructure migrations and making significant investments in AI while regional banks and credit unions are putting plans in place for modernization strategies, and fintechs are purpose-built and cloud native. To explore this more, I recently had the privilege of attending the annual Reuters NEXT live event in New York City. The event gathers globally recognized leaders across business, finance, technology, and government to tackle some of today’s most pressing issues. On the World Stage, I joined Del Irani, a talented anchor and broadcast journalist, to discuss the future of lending and the pivotal role of data and AI in building a more inclusive financial system. Improving financial access Our discussion highlighted the lack of access to traditional financial systems, and the impact it has on nearly 100 million people in North America alone. Globally, the problem affects over one billion people. These people, who are credit invisible, unscoreable, or have subprime credit scores, are unable to secure everyday financial products that many of us take for granted. What many don’t realize is, this is not a fringe subset of the population. Most of us, myself included, know someone who has faced the challenges of financial exclusion. Everyday Americans, including young people who are just starting out, new immigrants and people from diverse communities, often lack access to mainstream financial products. We discussed how traditional lending has a limited view of a consumer. Like looking through a keyhole, the lender’s understanding of the person in view is often incomplete and obstructed. However, with expanded data, technology, and advanced analytics, there is an opportunity to better understand the whole person, and as a result have a more inclusive financial system. At Experian, we have a unique ability to connect the power of traditional credit with alternative data, bringing a more holistic understanding of consumers and their behaviors. We are dedicated to leveraging our rich history in data and our expertise in technology to create the future of credit and ultimately bring financial power to everyone. The future of lending After spending two days with over 700 industry leaders from around the world, one thing is abundantly clear: much like the early days of the internet, today, we are at the cutting-edge of a technical revolution. Reflecting on my time at Reuters NEXT, I am particularly excited by the collective commitment to drive innovative, and smarter ways of working. We are only beginning to scratch the surface of how data and technology can transform financial services, and Experian is positioned to play a significant role. As we look to the future, I am excited about the ways we will create new opportunities for businesses and consumers alike.
The advertising ecosystem has seen significant transformation over the past few years, with increased privacy regulation, changes in available signals, and the rise of channels like connected TV and retail media. These changes are impacting the way that consumers interact with brands and how brands understand and continue to deliver relevant messages to consumers with precision. Experian has been helping marketers navigate these changes, and as a result, our marketing data and identity solutions underpin much of today’s advertising industry. We’re committed to empowering marketers and agencies to understand and reach their target audiences, across all channels. Today, we are excited to announce our acquisition of Audigent—a leading data and activation platform in the advertising industry. With Audigent’s combination of first-party publisher data, inventory and deep supply-side distribution relationships, publishers, big and small, can empower marketers to better understand their customers, expand the reach of their target audiences and activate those audiences across the most impactful inventory. I am excited to bring together Audigent’s supply-side network as a natural extension to our existing demand-side capabilities. Audigent’s ability to combine inventory with targeted audiences using first-party, third-party and contextual signals provides the best of all worlds, allowing marketers to deliver campaigns centered on consumer choices, preferences, and behaviors. The addition of Audigent further strengthens our strategy to be the premier independent provider of marketing data and identity, ultimately creating more relevant experiences for consumers. To learn more about Experian and Audigent, visit https://www.experian.com/marketing/ and https://audigent.com/.
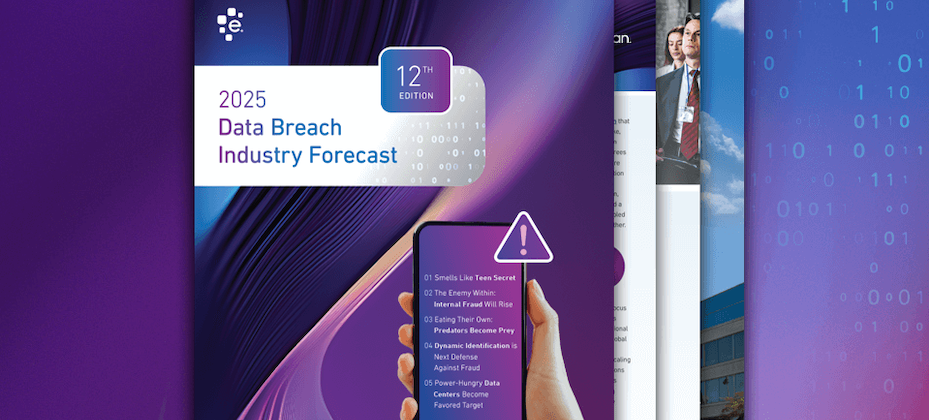
When it comes to cybercriminals and threat vectors, we need to expect the unexpected. Experian’s 12th annual Data Breach Industry Forecast highlights several potential trends for 2025, with AI playing a central role. This year has already seen more data breaches and impacted consumers than 2023, indicating that global data breaches are not slowing down. Some things to watch out for next year includes the potential for more internal fraud. As companies train employees on AI, there is a growing risk that some will misuse their knowledge for internal theft and sourcing sensitive information. Another trend may be cyberattackers targeting large data centers, with the growth of generative AI introducing power as a new attack vector. It’s reported that a single ChatGPT query uses significantly more electricity than a standard Google search, making data centers and cloud infrastructure vulnerable, especially in countries with varying security standards. We expect AI-related attacks to dominate the headlines next year and investments in cybersecurity will increase to tackle this emerging threat, as hackers leverage AI for phishing, password cracking, malware, and deepfakes. Jim Steven, Head of Crisis and Data Response Services at Experian Global Data Breach Resolution in the UK, anticipates that global data breaches will persist at their current rate next year. He notes that ransomware attacks are likely to become even more sophisticated with the integration of AI. Additionally, Steven predicts that threat actors will escalate their tactics to achieve greater rewards, and the misuse of consumer data to damage reputations will increase in 2025. To access the complimentary report, click here.
This is my video description!
media text block