In 2013, I came out to my brother. Sitting down at dinner, knowing whole-heartedly that he would fully accept me and nothing with our relationship would change, I was still scared. Each year on October 11, National Coming Out Day, I reflect on that first coming out experience and what I truly feared. Even though I knew I was safe, I also knew that coming out to him was just the start of coming out every single day for the rest of my life. It was the start of facing discrimination and judgment both in day-to-day life and professionally. It wasn’t a decision I made lightly. Coincidently, my brother came out to me at that very same dinner which certainly took some weight and anxiety off my shoulders. We came out to our family, together later that week and we were welcomed with love, acceptance, and support. The unconditional support I received is not normal, but my anxiety around the process was. I am grateful and quite lucky that my initial coming out process to my family was, for lack of a better term, easy. Like many others I don’t experience that same ease everywhere I go. I have been asked to leave restaurants, turned away from stores, spat on multiple times, and even asked to leave mass during service. I am regularly questioned when entering or leaving a women’s public restroom. Michele Bodda, our executive co-sponsor of Experian’s Pride employee resource group, said it perfectly in her message two years ago, “The difficulty some of our LGBT+ colleagues face making daily decisions about where they can be fully present aren’t merely insecurities. They are the realities of being LGBT+.” Let that sink in. Coming out is not a one and done experience, it is something we do over and over throughout our lives. That reality impacts people in different ways, and it’s why acknowledging National Coming Out Day means so much to me – why it means so much to many others. I feel particularly fortunate to work for a company that celebrates and recognizes our uniqueness. I know many people at Experian, like myself, who feel empowered and supported to bring their whole self to work and that reality is assuring, professionally and personally. I have been told I am brave for bringing forth my full authentic self each day. During a time of such global anxiety, uncertainty, and open expressions of intolerance and hatred, being a voice of empowerment, representation, and visibility for folks who do not feel comfortable being out is more important than ever. I’m willing to be a voice so others know they are not alone. Be brave with me. And if you’re not ready, I understand. I’m here for you when you are.
In a world that was already becoming increasingly digital, COVID-19 expedited timelines and turned forecasted projects into immediate needs nearly overnight. I’ve seen this play out in my role at Experian as well as across the financial services industry. Experian was recognized as an innovative company prior to the pandemic and the current environment has only accelerated our ability to innovate. As we surpassed the six month mark adjusting to our new normal, I was invited to join Bloomberg’s Future of Finance: Leveraging Digital Transformation for a Virtual World roundtable discussion with Senior Analyst of Bloomberg Intelligence Julia Chariell and leaders from IBM, Ally Financial, Deutsche Bank and others, to share how we are rising to meet the needs of consumers and lenders during the COVID-19 pandemic. You can find a recap of our conversation here and view the full video discussion here. We know each American is facing unique COVID-19-related circumstances, so there is not a one-size-fits-all solution. This notion has carried us as we are rising to meet the needs of our clients and consumers during the pandemic. We must allow individuals who can still meet their financial obligations to have access to credit and ensure lenders can identify them. Maintaining and improving financial access for these consumers will play an important role in our road to economic recovery. To continue to lend responsibly, the financial services industry must carefully examine all aspects of consumer financial capability in near real-time – consumer control and consumer-permissioned data play a key role in achieving this. By leveraging accurate data, I believe we have a chance to lessen the impact of the current U.S. economic crisis, extend credit responsibly, and support the hardest-hit consumers as we adjust to a new world post COVID-19.
Identity has always been the cornerstone of the advertising ecosystem; the connective tissue that helps brands create a more relevant experience for consumers. For the past 20-plus years, identity has heavily relied on the third-party cookie. But with the third-party cookie set to become obsolete in the next year and a half, and to a lesser, unknown extent, Apple’s pullback on the identifier for advertisers (IDFA), the industry needs to re-evaluate and adapt. Without the third-party cookie, identity is a bit more complicated. Consumers engage brands through hundreds of different devices, apps and channels—and with walled gardens and disparate data sources, it’s tough to connect these digital touchpoints together. Add to that, the hundreds of offline interactions consumers have, and the single-customer view is unattainable; at least without the right data resources and partners. With little concrete direction on how to move forward in the post-cookie world, finding the right identity resolution partner can help you connect digital and offline touchpoints and better understand consumers. Forrester recently released its Now Tech: Identity Resolution, Q3 2020 report, identifying 28 identity resolution providers that can help with identity data management, analysis and measurement. Experian is proud to be included on the list. These identity resolution products serve a number of different use cases and it is important to select a vendor that you can trust while navigating this dynamic market. The new report states “Marketers must proactively calculate how industry changes impact identity resolution and marketing efforts, evaluate current partners’ ability to accommodate changes, and consider alternative providers and approaches.” Finding new ways to approach identity resolution is challenging in such a dynamic industry; the path forward likely isn’t rooted in a single identifier. Experian is committed to helping you resolve consumer identities. Our solutions connect consumers at every touchpoint and execute matching in a privacy-compliant manner. The phase-out of third-party cookies has already changed the advertising industry as we know it. But the deprecation of third-party cookies does not mean then end of people-based advertising; we still need to provide a relevant experience for consumers. The balance between data privacy and security with relevancy is achievable; the right partner can help you get there. Learn more about how Experian can help you resolve customer identities.
Related Posts
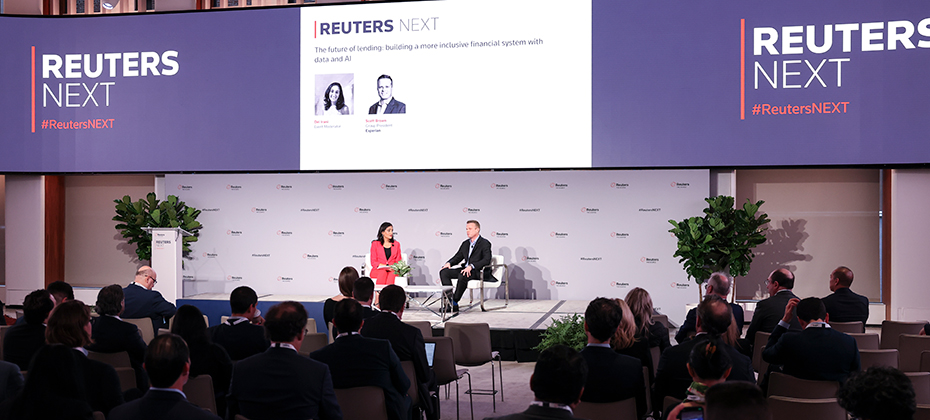
Today, we stand at the forefront of a digital revolution that is reshaping the financial services industry. And, against this backdrop, financial institutions are at vastly different levels of maturity; the world’s biggest banks are managing large-scale infrastructure migrations and making significant investments in AI while regional banks and credit unions are putting plans in place for modernization strategies, and fintechs are purpose-built and cloud native. To explore this more, I recently had the privilege of attending the annual Reuters NEXT live event in New York City. The event gathers globally recognized leaders across business, finance, technology, and government to tackle some of today’s most pressing issues. On the World Stage, I joined Del Irani, a talented anchor and broadcast journalist, to discuss the future of lending and the pivotal role of data and AI in building a more inclusive financial system. Improving financial access Our discussion highlighted the lack of access to traditional financial systems, and the impact it has on nearly 100 million people in North America alone. Globally, the problem affects over one billion people. These people, who are credit invisible, unscoreable, or have subprime credit scores, are unable to secure everyday financial products that many of us take for granted. What many don’t realize is, this is not a fringe subset of the population. Most of us, myself included, know someone who has faced the challenges of financial exclusion. Everyday Americans, including young people who are just starting out, new immigrants and people from diverse communities, often lack access to mainstream financial products. We discussed how traditional lending has a limited view of a consumer. Like looking through a keyhole, the lender’s understanding of the person in view is often incomplete and obstructed. However, with expanded data, technology, and advanced analytics, there is an opportunity to better understand the whole person, and as a result have a more inclusive financial system. At Experian, we have a unique ability to connect the power of traditional credit with alternative data, bringing a more holistic understanding of consumers and their behaviors. We are dedicated to leveraging our rich history in data and our expertise in technology to create the future of credit and ultimately bring financial power to everyone. The future of lending After spending two days with over 700 industry leaders from around the world, one thing is abundantly clear: much like the early days of the internet, today, we are at the cutting-edge of a technical revolution. Reflecting on my time at Reuters NEXT, I am particularly excited by the collective commitment to drive innovative, and smarter ways of working. We are only beginning to scratch the surface of how data and technology can transform financial services, and Experian is positioned to play a significant role. As we look to the future, I am excited about the ways we will create new opportunities for businesses and consumers alike.
The advertising ecosystem has seen significant transformation over the past few years, with increased privacy regulation, changes in available signals, and the rise of channels like connected TV and retail media. These changes are impacting the way that consumers interact with brands and how brands understand and continue to deliver relevant messages to consumers with precision. Experian has been helping marketers navigate these changes, and as a result, our marketing data and identity solutions underpin much of today’s advertising industry. We’re committed to empowering marketers and agencies to understand and reach their target audiences, across all channels. Today, we are excited to announce our acquisition of Audigent—a leading data and activation platform in the advertising industry. With Audigent’s combination of first-party publisher data, inventory and deep supply-side distribution relationships, publishers, big and small, can empower marketers to better understand their customers, expand the reach of their target audiences and activate those audiences across the most impactful inventory. I am excited to bring together Audigent’s supply-side network as a natural extension to our existing demand-side capabilities. Audigent’s ability to combine inventory with targeted audiences using first-party, third-party and contextual signals provides the best of all worlds, allowing marketers to deliver campaigns centered on consumer choices, preferences, and behaviors. The addition of Audigent further strengthens our strategy to be the premier independent provider of marketing data and identity, ultimately creating more relevant experiences for consumers. To learn more about Experian and Audigent, visit https://www.experian.com/marketing/ and https://audigent.com/.
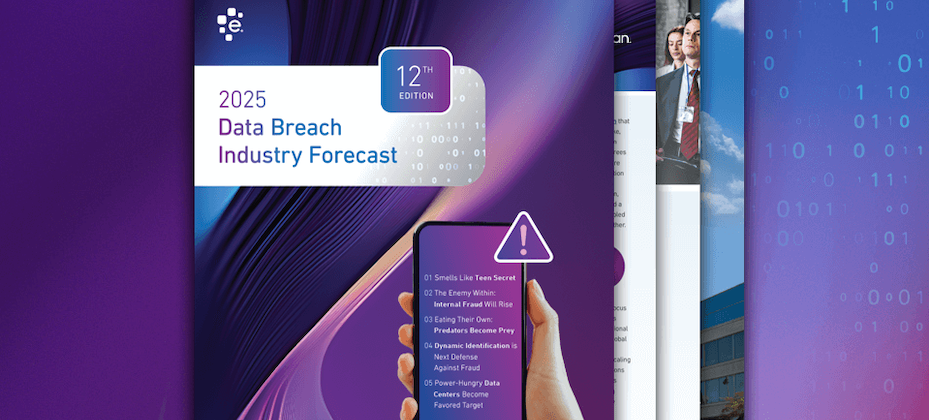
When it comes to cybercriminals and threat vectors, we need to expect the unexpected. Experian’s 12th annual Data Breach Industry Forecast highlights several potential trends for 2025, with AI playing a central role. This year has already seen more data breaches and impacted consumers than 2023, indicating that global data breaches are not slowing down. Some things to watch out for next year includes the potential for more internal fraud. As companies train employees on AI, there is a growing risk that some will misuse their knowledge for internal theft and sourcing sensitive information. Another trend may be cyberattackers targeting large data centers, with the growth of generative AI introducing power as a new attack vector. It’s reported that a single ChatGPT query uses significantly more electricity than a standard Google search, making data centers and cloud infrastructure vulnerable, especially in countries with varying security standards. We expect AI-related attacks to dominate the headlines next year and investments in cybersecurity will increase to tackle this emerging threat, as hackers leverage AI for phishing, password cracking, malware, and deepfakes. Jim Steven, Head of Crisis and Data Response Services at Experian Global Data Breach Resolution in the UK, anticipates that global data breaches will persist at their current rate next year. He notes that ransomware attacks are likely to become even more sophisticated with the integration of AI. Additionally, Steven predicts that threat actors will escalate their tactics to achieve greater rewards, and the misuse of consumer data to damage reputations will increase in 2025. To access the complimentary report, click here.
This is my video description!
media text block