In the early 1970’s a brilliant engineer/inventor/music lover designed a credit card sized electronic music player. Early prototypes and models of this small music player received the accolades of “the most radical music system ever” from the audio industry. Many of you may think I am talking about Steve Jobs – well I am not. This inventor however was distracted, did not pay attention to the business and saw the technology get away from him. And that is why today, Jobs and Apple’s 1.75 billion iPods are a household name and Kane Kramer is not. So the question for you today is…are you keeping your eye on the technology, trends, and market place that will make your commercial lending efforts successful and sustainable? In a CEB TowerGroup survey, bank executives clearly called out that maximizing credit applications with quality growth is the top priority for 2014. To be successful in achieving that growth commercial bankers will be focused in 2014 and beyond on these five key areas: (1) Rationalizing infrastructure, (2) Optimizing sourcing, (3) Centralizing risk management, (4) Enhancing liquidity management, and (5) Implementing commercial loan management solutions. To back that claim, in the 2013 Sales Readiness Assessment, CEB TowerGroup found that banks that are taking these steps to lead in technology changes were seeing an increase of 8% in their top performing relationship managers, and a 13% increase overall. And while growth is critical, we cannot take our eye off the existing portfolio. Best practices suggest that to make the most impact in 2014, institutions should in the next 90 days to take steps to look at their individual loans, but with multiple factors, e.g. duration, convexity, and yield. But even more important banks should aggregate these views to a portfolio level to make sure that can optimize returns overall. So while we see that in commercial lending the 3-year CAGR is now 10.5% and looking stronger, banks need to focus and not be distracted and capitalize on these opportunities. Invest and stay focused on the future! Vision 2014: The new world of commercial lending from Experian Business Information Services Tweet this! Not focusing on #innovation & change can cost you. Kramer designed IXI in the 70’s. But #apple gained with 1.7 B #ipod sold. #vision2014 Click to Tweet This At @ExperianVision and Joanne Pollitt from CEB Tower Group talking about #change in cmcl #banking for 2014. Are you ready? @ExperianVision Click to Tweet This What is your #banks top #commercial #banking #initiative for 2014?? How can @Experian_DA_GCP and @Experian_US help you #succeedandproceed Click to Tweet This
4000! Consumers view over 4000 ads per day. As a result they are overwhelmed with information and opt not to see what could be waiting for them. The best way to grab the consumer’s attention and CLOSE the sale is to target them with content directly related to their interests. This is not an easy task, but Experian can help lenders stay above the noise and drive relevant traffic to their websites. We can turn a site visit into a credit qualified lead and ultimately a high-quality booked account – cutting through the “junk” that drags down your portfolio’s performance.
The amount of data being generated nowadays is staggering. In fact, according to one source, more data has been produced in the past two years than ever before. Certainly Experian has made it our business to understand all of this data and how to harness it. I’ve recently had the opportunity to consider the impact of data in Formula 1 Racing, the most prestigious and high-tech racing series on the planet. Experian is a sponsor of Williams Martini Racing, which is one of the “big four” teams in the sport and has produced 16 Formula One World Championship titles.
Debt is often thought of as a scary word and many spend their lives trying to avoid it at all costs. Understanding what credit is, why you need it and how to build it can help make it less frightening and can actually put you in control. Debt doesn’t have to be a four-letter word. To wrap up Financial Literacy Month, Experian released a study this week that takes an in depth look at debt and credit scores in the 20 largest cities across the U.S. and compares the numbers to where these cities were four years ago. The findings show that Detroit residents have the least amount of debt, while the residents of Dallas have the most.
Did you know children are increasingly vulnerable to being a victim of identity theft? Their clean credit history is an easy target for perpetrators. Thieves often can profit for years before the crime is detected. In general, minors should not have credit activity or a credit report until they apply for loans or a credit card. That said, it is possible that they may have a credit history if you have added them as an authorized user to your credit accounts during their teen years.
Experian-Oliver Wyman data reports a 46 percent increase in home equity lending; 19 percent increase in bankcard origination volume Costa Mesa, Calif., April 30, 2014 — Experian®, the leading global information services company, today released year-end analysis of credit and mortgage trends from the 2013 Q4 Experian–Oliver Wyman Market Intelligence Report that showed positive economic indicators along with smarter consumer spending. “Overall from 2013 we saw a strong steady improvement in the economy similar to our 2012 year-end review. Consumer confidence increased as they continue to be resilient during the ongoing recovery,” said Linda Haran, senior director of product management and strategy for Experian Decision Analytics. “While overall consumer debt increased 6 percent, it was not heavily weighted in one particular VantageScore segment. Debt increases occurred across all VantageScore consumer segments equating to a balanced distribution of increases in total debt year-over-year. That represents smarter spending among all consumers.” “Other positive indicators coming out of 2013 include bankruptcies declining 12 percent from 2012 and consumer delinquency trends continuing to decrease. Home Equity originations realized strong growth in 2013, exceeding 2009 levels as new lending was up 42 percent in Q4 2013 over the same period a year ago.” Watch Experian Decision Analytics analysts Linda Haran and Alan Ikemura discuss the latest trends from the Experian-Oliver Wyman Q4 2013 report on consumer debt, bankcards, mortgages and auto. 2013 Mortgage trends included: Overall mortgage origination volume in 2013 was $2 trillion up from $1.9 trillion in 2012 2013 saw annual growth of 25% in new home purchase volume compared to 2012 Overall mortgage 30+ day mortgage delinquency rates were down 14 percent in 2013 versus 2012 The West region saw 30+ day mortgage delinquency rates drop 23 percent in 2013 versus 2012. California saw a 24 percent decline in late mortgage payments. 2013 Bankcard trends included: Analyzing the data for 2013 shows a 19 percent increase in bankcard origination volume, growing from $228 billion to $271 billion year over year. Two-thirds of new bankcard originations occurred among the Super Prime (781 – 850) and Prime (661-780) VantageScore tiers. The U.S. 60+ day delinquency bankcard rates overall improved 14.5 percent in Q4 2013 versus Q4 2012. All 50 states saw bankcard delinquency rates improve for the 60+ day category. California, Tennessee, Massachusetts, Michigan and Wisconsin were the top 5 states that improved their 60+ day delinquency bankcard rates in Q4 2013. Arizona, New Mexico, Arkansas, West Virginia and Alaska were the bottom 5 states in terms of overall percentage improvement among 60+ day delinquency bankcard rates in Q4 2013. Experian has dedicated educational resources to help consumers understand the impact debt has on credit. Consumers can visit our Live Credit Smart website to learn more. For more insight from Experian Decision Analytics, watch our 2013 Q4 Experian–Oliver Wyman Market Intelligence Report presentation: http://ex.pn/1eJaRZB. Make sure to join us for Q1 2014 Experian–Oliver Wyman Market Intelligence Report webinar. About the data The data for this insight and analysis was provided by Experian’s IntelliViewSM product. IntelliView data is sourced from the information that supports the Experian–Oliver Wyman Market Intelligence Reports and is easily accessed through an intuitive, online graphical user interface, which enables financial professionals to extract key findings from the data and integrate them into their business strategies. This unique data asset does this by delivering market intelligence on consumer credit behavior within specific lending categories and geographic regions.
Related Posts
Read Moreio55 Button 2- Learn more Primary button Secondary button Related Posts image1 image2 media text block
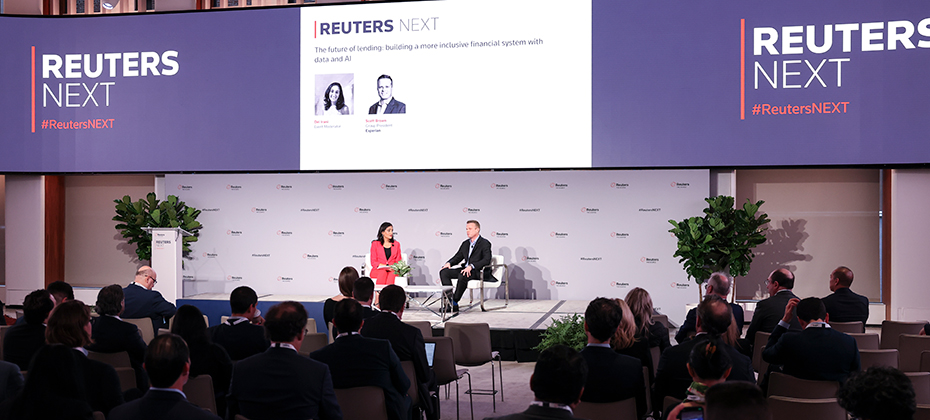
Today, we stand at the forefront of a digital revolution that is reshaping the financial services industry. And, against this backdrop, financial institutions are at vastly different levels of maturity; the world’s biggest banks are managing large-scale infrastructure migrations and making significant investments in AI while regional banks and credit unions are putting plans in place for modernization strategies, and fintechs are purpose-built and cloud native. To explore this more, I recently had the privilege of attending the annual Reuters NEXT live event in New York City. The event gathers globally recognized leaders across business, finance, technology, and government to tackle some of today’s most pressing issues. On the World Stage, I joined Del Irani, a talented anchor and broadcast journalist, to discuss the future of lending and the pivotal role of data and AI in building a more inclusive financial system. Improving financial access Our discussion highlighted the lack of access to traditional financial systems, and the impact it has on nearly 100 million people in North America alone. Globally, the problem affects over one billion people. These people, who are credit invisible, unscoreable, or have subprime credit scores, are unable to secure everyday financial products that many of us take for granted. What many don’t realize is, this is not a fringe subset of the population. Most of us, myself included, know someone who has faced the challenges of financial exclusion. Everyday Americans, including young people who are just starting out, new immigrants and people from diverse communities, often lack access to mainstream financial products. We discussed how traditional lending has a limited view of a consumer. Like looking through a keyhole, the lender’s understanding of the person in view is often incomplete and obstructed. However, with expanded data, technology, and advanced analytics, there is an opportunity to better understand the whole person, and as a result have a more inclusive financial system. At Experian, we have a unique ability to connect the power of traditional credit with alternative data, bringing a more holistic understanding of consumers and their behaviors. We are dedicated to leveraging our rich history in data and our expertise in technology to create the future of credit and ultimately bring financial power to everyone. The future of lending After spending two days with over 700 industry leaders from around the world, one thing is abundantly clear: much like the early days of the internet, today, we are at the cutting-edge of a technical revolution. Reflecting on my time at Reuters NEXT, I am particularly excited by the collective commitment to drive innovative, and smarter ways of working. We are only beginning to scratch the surface of how data and technology can transform financial services, and Experian is positioned to play a significant role. As we look to the future, I am excited about the ways we will create new opportunities for businesses and consumers alike.
The advertising ecosystem has seen significant transformation over the past few years, with increased privacy regulation, changes in available signals, and the rise of channels like connected TV and retail media. These changes are impacting the way that consumers interact with brands and how brands understand and continue to deliver relevant messages to consumers with precision. Experian has been helping marketers navigate these changes, and as a result, our marketing data and identity solutions underpin much of today’s advertising industry. We’re committed to empowering marketers and agencies to understand and reach their target audiences, across all channels. Today, we are excited to announce our acquisition of Audigent—a leading data and activation platform in the advertising industry. With Audigent’s combination of first-party publisher data, inventory and deep supply-side distribution relationships, publishers, big and small, can empower marketers to better understand their customers, expand the reach of their target audiences and activate those audiences across the most impactful inventory. I am excited to bring together Audigent’s supply-side network as a natural extension to our existing demand-side capabilities. Audigent’s ability to combine inventory with targeted audiences using first-party, third-party and contextual signals provides the best of all worlds, allowing marketers to deliver campaigns centered on consumer choices, preferences, and behaviors. The addition of Audigent further strengthens our strategy to be the premier independent provider of marketing data and identity, ultimately creating more relevant experiences for consumers. To learn more about Experian and Audigent, visit https://www.experian.com/marketing/ and https://audigent.com/.