Greater transparency in buy now, pay later activity is key to helping consumers build their credit histories and supporting responsible lending.
Experian North AmericaScott Brown, Group President, Financial Services
Affirm plans to report all pay-over-time loan products issued from April 1, 2025, and beyond, including Pay-in-4. The move will help drive greater transparency into the buy now, pay later market while helping consumers build their credit histories over time.
Related Posts
Read Moreio55 Button 2- Learn more Primary button Secondary button Related Posts image1 image2 media text block
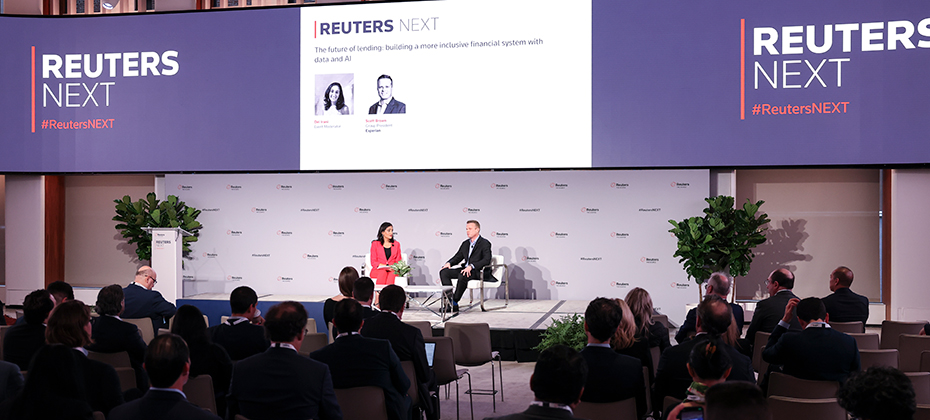
Today, we stand at the forefront of a digital revolution that is reshaping the financial services industry. And, against this backdrop, financial institutions are at vastly different levels of maturity; the world’s biggest banks are managing large-scale infrastructure migrations and making significant investments in AI while regional banks and credit unions are putting plans in place for modernization strategies, and fintechs are purpose-built and cloud native. To explore this more, I recently had the privilege of attending the annual Reuters NEXT live event in New York City. The event gathers globally recognized leaders across business, finance, technology, and government to tackle some of today’s most pressing issues. On the World Stage, I joined Del Irani, a talented anchor and broadcast journalist, to discuss the future of lending and the pivotal role of data and AI in building a more inclusive financial system. Improving financial access Our discussion highlighted the lack of access to traditional financial systems, and the impact it has on nearly 100 million people in North America alone. Globally, the problem affects over one billion people. These people, who are credit invisible, unscoreable, or have subprime credit scores, are unable to secure everyday financial products that many of us take for granted. What many don’t realize is, this is not a fringe subset of the population. Most of us, myself included, know someone who has faced the challenges of financial exclusion. Everyday Americans, including young people who are just starting out, new immigrants and people from diverse communities, often lack access to mainstream financial products. We discussed how traditional lending has a limited view of a consumer. Like looking through a keyhole, the lender’s understanding of the person in view is often incomplete and obstructed. However, with expanded data, technology, and advanced analytics, there is an opportunity to better understand the whole person, and as a result have a more inclusive financial system. At Experian, we have a unique ability to connect the power of traditional credit with alternative data, bringing a more holistic understanding of consumers and their behaviors. We are dedicated to leveraging our rich history in data and our expertise in technology to create the future of credit and ultimately bring financial power to everyone. The future of lending After spending two days with over 700 industry leaders from around the world, one thing is abundantly clear: much like the early days of the internet, today, we are at the cutting-edge of a technical revolution. Reflecting on my time at Reuters NEXT, I am particularly excited by the collective commitment to drive innovative, and smarter ways of working. We are only beginning to scratch the surface of how data and technology can transform financial services, and Experian is positioned to play a significant role. As we look to the future, I am excited about the ways we will create new opportunities for businesses and consumers alike.
The advertising ecosystem has seen significant transformation over the past few years, with increased privacy regulation, changes in available signals, and the rise of channels like connected TV and retail media. These changes are impacting the way that consumers interact with brands and how brands understand and continue to deliver relevant messages to consumers with precision. Experian has been helping marketers navigate these changes, and as a result, our marketing data and identity solutions underpin much of today’s advertising industry. We’re committed to empowering marketers and agencies to understand and reach their target audiences, across all channels. Today, we are excited to announce our acquisition of Audigent—a leading data and activation platform in the advertising industry. With Audigent’s combination of first-party publisher data, inventory and deep supply-side distribution relationships, publishers, big and small, can empower marketers to better understand their customers, expand the reach of their target audiences and activate those audiences across the most impactful inventory. I am excited to bring together Audigent’s supply-side network as a natural extension to our existing demand-side capabilities. Audigent’s ability to combine inventory with targeted audiences using first-party, third-party and contextual signals provides the best of all worlds, allowing marketers to deliver campaigns centered on consumer choices, preferences, and behaviors. The addition of Audigent further strengthens our strategy to be the premier independent provider of marketing data and identity, ultimately creating more relevant experiences for consumers. To learn more about Experian and Audigent, visit https://www.experian.com/marketing/ and https://audigent.com/.
Amid the rise in usage of generative AI tools, companies across industries are looking for fraud detection strategies that enable them to combat sophisticated fraud schemes now and in the future. At Experian, we’re committed to ensuring our clients can make the most informed, data-driven decisions to protect the customers they serve while mitigating risk. To support this, today we’re excited to announce our acquisition of NeuroID – an industry leader in behavioral analytics. NeuroID combines the power of behavioral analytics with advanced device and network intelligence to create the first line of defense against malicious bots, bad actors, and fraud rings. This can help clients identify everything from identity theft to account takeover fraud from the very first interaction. NeuroID’s modern and frictionless capabilities amplify Experian’s fraud risk suite by providing a new layer of insight into digital behavioral signals and analytics observed for both new and returning users throughout the customer lifecycle. Together with NeuroID, we’re excited to build new blended offerings that detect risk but also empower businesses to confidently navigate the online landscape and trust in their transactions. Experian has a long legacy of providing award-winning fraud and identity solutions to protect companies and their customers. Last year alone, our identity verification and fraud prevention solutions helped clients avoid an estimated $15 billion in fraud losses globally. Adding NeuroID to the Experian family is another step in our commitment to continuous innovation in fighting fraud and helping clients and consumers keep pace with the evolving identity landscape. NeuroID’s behavioral analytics solutions are available now through CrossCore® on the Experian Ascend Technology Platform™ as a key fraud-detection capability. With NeuroID seamlessly integrated into Experian, clients can use one service provider to proactively monitor and analyze a user’s real-time digital behavior. To learn more, click here.
Amid some of the financial challenges that underserved communities experience, members across the financial services community remain committed to championing initiatives and programs that drive greater financial inclusion. In fact, collaboration has led to the inclusion of non-debt related payment information on consumers’ credit profiles, as well as digital services that make it easier to manage money. These efforts have helped to broaden access to fair and affordable financial resources for more individuals. While significant progress has been made, there is still more work to do. However, some of the misconceptions and myths about the financial services community are hindering further advancement. Debunking these myths will accelerate progress by building trust between the financial services community and consumers. Person withdrawing money from ATM contactless Myth #1: “Financial institutions have no interest in underserved consumers or credit invisibles.” The truth is, banks and credit unions want to say “yes” to more prospective borrowers, including individuals and families from underserved communities. Beyond being the right thing to do, it’s an opportunity to potentially build lifelong relationships with a relatively untapped market. A show of good faith to communities who have largely been ignored by the financial system could lead to customer loyalty that may extend to their family and friends. That’s why participants across the financial ecosystem have been proponents of including expanded data sources—such as on-time telecom, utility and video streaming service payments—on to consumer credit reports, as well as exploring other Fair Credit Reporting Act (FCRA)-regulated data sources, including payment data on short-term small dollar loans and expanded public records data. Making this data more accessible to lenders provides a more comprehensive view of a consumer’s ability and willingness to repay outstanding debt—an actionable solution to extending credit to consumers without lenders taking on additional risk. Myth #2: “There is a lack of trustworthy financial education resources.” The financial services community and affiliated organizations recognize that empowering people with financial knowledge and skillset are critical to consumers’ financial success. In fact, banks and credit unions are partnering with nonprofits and non-governmental organizations to better understand the unique challenges and opportunities within specific communities and provide relevant tools and resources. For example, Experian’s B.A.L.L. for Life (Be A Legacy Leader) program, launched in partnership with the National Urban League, serves as a catalyst for engaging with Black communities and low-income youth through live events and digital financial education. Subject matter experts, professional athletes, celebrities, and other influencers share their experiences and expertise, covering topics such as banking, credit, financial management and investing. In addition, to help people improve their financial management, Experian partners with the National Foundation for Credit Counseling (NFCC). The NFCC connects consumers with certified financial counselors to help them address various pain points, including debt management, homeownership, student loans or small business cash flow issues. Myth #3: “Underserved communities have few opportunities to build credit and enter the mainstream financial system.” People from underserved communities, as well as younger consumers and recent immigrants are often excluded from the mainstream financial system because they lack an extensive credit history. Historically, it’s created a vicious cycle; in order to get credit, you have to have credit. Fortunately, there has been a sea change in innovative solutions to address the specific needs of these populations. These include new credit scoring models and microfinancing which provide financial services to individuals who may have been excluded from traditional banking systems. In addition, by incorporating expanded data sources, such as telecom, utility and residential rental payments onto credit reports, lenders have more visibility into consumers who may have been excluded by traditional credit scoring methods.These programs help individuals and families from underserved communities establish and build a credit history that could enable loans, or the ability to rent an apartment or open their dream business. An example is Experian Boost®, a free feature that allows Experian members to contribute their history of making utility, cellphone, insurance, residential rent and video streaming service payments directly into their Experian credit profile. By incorporating nontraditional credit data like paying utility bills on time, online banking transactions, rental payments and verified income data, more people can establish a credit profile that can potentially qualify them for a loan. More Inclusion, Fewer Myths It’s encouraging that community organizations and banks are beginning to see the economic and social benefits of aligning on financial literacy and inclusion. As more initiatives come online, underserved populations will be able to establish a better financial foundation. Then, we can declare the myths to be history.
Experian is wrapping up several inspiring days at the 2024 Disability:IN Conference. We are a proud Presenting partner, and as part of our support this year, we had the honor of being the key sponsor for the NextGen Innovation Lab Pitch Competition. This initiative brings together young adults to develop innovative products or services that benefit individuals with disabilities. It provides a platform for young minds to harness their creativity and technical skills to solve real-world challenges faced by the disability community. This year, we challenged these NextGen leaders to create a product or service specifically for young adults with disabilities that can help them build their credit or improve their financial literacy. Only 10% of working aged people with disabilities consider themselves to be financially healthy, according to a recent study. Eight enthusiastic and passionate teams shared their ideas and the top two vote-getters’ pitched live, “Shark Tank” style, in front of thousands of conference attendees. The winner: Team 7’s “Experian Expedition,” which enhances the accessibility of the existing Experian app and adds new experiences such as an accessible credit card that also features braille; voice-guided, American Sign Language and closed-captioned exercises; and an incentive program for young adults as they reach various financial health milestones with cash back and coupons. We congratulate Team 7 and all of the teams for their collaboration with Experian and each other. The ideas and services developed through the NextGen iLab have the potential to make a significant impact on the disability community, enhancing accessibility, independence, and quality of life for millions. Sponsoring the NextGen iLab is just one of the many ways Experian is committed to disability inclusion. For the third consecutive year, Experian has achieved a top score in the Disability Equality Index (DEI) 2024. This accolade underscores Experian’s ongoing efforts towards inclusivity in our workplace, products and services that are accessible and beneficial to individuals of all abilities, including the Support Hub, Financial Resilience Center, Inclusion Works, and the CMO/CCO Coalition. We’re proud our efforts are recognized by Disability:IN and the American Association of People with Disabilities (AAPD). To learn more about Experian’s commitment to inclusion, check out our Power of YOU Report 2024: Driving social impact and diversity, equity and inclusion in English, Portuguese and Spanish.
In this article…