Lorem Ipsumis simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry’s standard dummy text ever since the 1500s, when an unknown printer took a galley of type and scrambled it to make a type specimen book. It has survived not only five centuries, but also the leap into electronic typesetting, remaining essentially unchanged.
A year ago, we shifted our business to remote working as the global pandemic took hold. Like the rest of the world, we had no idea how long we’d be away, but we didn’t really imagine we’d still be operating our business with a remote workforce a year later. What a year it has been. It is incredible to look back and reflect on how our lives have changed, how we were able to adapt to this new way of living and working, and really importantly, how we were able to keep innovating to help communities and businesses during this difficult time. We have captured highlights of our work and efforts in our North America annual diversity and inclusion report, 2020 Power of YOU. At Experian, the safety and well-being of our colleagues has consistently been a top priority. As such, we have been able to focus on serving consumers and clients when and where they need help the most. As a company, we expanded our benefits to take care of our employees. Coworkers jumped in to take care of each other. Our employee resource group dedicated to mental health and caregiving partnered with colleagues to create a dynamic set of tools and guides tackling different topics every week through webinars, articles and personal, candid videos from leaders. We supported each other during times of social unrest. We celebrated progress in growing our business. We logged 18,000 volunteer hours to increase financial inclusion, support frontline healthcare workers, honor active duty military and veterans, and fight hunger in underprivileged communities. We leveraged our diversity of perspectives, backgrounds and experiences to help vulnerable populations in crisis from COVID-19, including launching our United for Financial Health program. We remain steadfast and committed to equity for all. We are proud to start the new year with this wonderful look back at last year, propelling us forward to more opportunities to innovate and serve. We invite you to check out the 2020 Power of YOU Report here.
As consumer demand for the digital channel continues to increase at an exceptional rate it has created an opportunity for businesses to serve the growing ranks of connected consumers. The most important thing is for businesses to ensure they are putting the consumer at the heart of the relationship. Experian has been studying insights related to consumer behavior and business strategy throughout the Covid-19 pandemic. For the third wave of our Global Insights Report we surveyed 3,000 consumers and 900 businesses across the globe in January. We observed not only consumer demand for the digital channel increasing but that fact that these trends are persisting. We believe that what started as necessity has turned into a preference. According to the report, 38% of consumers expect to increase their online activity in the next 12 months. Furthering our belief that the preference for digital transactions persists, 60% of consumers are using a universal mobile wallet to make digital payments. We also found that the two top activities among consumers online are personal banking (58%) and ordering groceries and takeout food (56%). The report also shows that security remains at the top of consumers’ minds when they are transacting online. 55%of consumers say security is the most important factor in their digital experience – this is highest in the UK (65%), followed by Japan (64%). All in all, the new research confirms that this shift to online activity, which continues to increase with no indications of slowing down, is a contributing factor to consumers’ growing appetite for digital. In this regard, we found that businesses have taken notice and are investing more resources around the digital experience. In fact, 9 in 10 businesses have a strategy in place related to the digital customer journey. 47% of businesses have put this strategy into place since Covid-19. In addition, more than a third of businesses are increasing staff or support for digital operations and experience. Fraud is the biggest challenge among businesses. However, 55% of businesses plan to increase fraud management budgets. As we move towards a post-pandemic era, and more consumers start to prefer banking and shopping online, a digital channel strategy simply isn’t enough. There needs to be a re-imagined customer journey that connects identity, preferences, products, and service. And data and technology have the power to help transform your customer relationships.

We are excited to announce the annual launch of our Global data management research! This year, we surveyed 700 business leaders across the U.S., U.K., and Brazil to get their perspective on usage of data throughout the pandemic. There’s no question that data initiatives have been on the to-do list for over a decade now, but as the pandemic came storming in, businesses quickly realized that data management never made it to the top of the list. In other words, most businesses were not prepared for the rapid transformation they needed to sustain during the global health crisis because their data, simply, was not ready. There are three major takeaways from this year’s study: An acceleration of digital transformation has made businesses reliant on high-quality data. We find that business priorities have remained the same over the last few years: Customer experience and data security. However, these initiatives are more important than ever before, especially when it comes to digital transformation. Seventy-two percent say an acceleration to digital transformation has made their business more reliant on data and data insights. Why? With dramatic changes in customer buying behaviour during the pandemic, and most employees still working remotely, digital engagement and operations have become key to sustaining business growth during economic crisis. Our research finds that seventy-five percent of respondents say they have seen a dramatic change in their customer’s buying behavior during the pandemic. With stores closed, overwhelmed distribution and shipping warehouses, and unpredictable supply chains (bread flour, anyone?) …businesses need to leverage online platforms, like their website and social media, to stay engaged with customers. Nowadays, it’s not unusual for a brand’s customer experience to be solely digital. Furthermore, with increased online activity and non-essential employees working from home, there’s a chance consumer or operational data could be at higher risk of unwanted actions or unauthorized users. This is where data security plays an important role in keeping records, and the business, safe. From the efficiency of the customer experience online to the data that helps us analyze markets and attitudes changing at a dizzying pace…the right data has become indispensable. The need for a data-driven digital operation and customer experience has made companies realize how mature their data functions are, or where there is opportunity for improvement. Data was not ready to sustain the impact of the pandemic. For many years, we have looked at the maturity level of data quality in the market. Our hope was that this maturity level had increased to handle the new demands and desire for insight. Unfortunately for many, levels of quality data continued to fall short. Fifty-five percent of business leaders say they lack trust in their data assets, hindering their ability to be fully data driven. The level of inaccurate data has remained high over the past five years of this study. Organizations believe about a third of their customer and prospect data is inaccurate in some way. Additionally, only fifty percent believe their CRM/ERP data is clean and can be fully leveraged. Poor data quality creates several roadblocks within organizations, regardless of their maturity. While data can be inaccurate for a wide variety of reasons, such as human error or natural data decay, the impact is the same. Ninety-five percent of businesses have seen impacts related to poor data quality. This could mean that poor quality data damages the reliability of analytics (36%), negatively affects customer experience (32%), and negatively impacts reputation and customer trust (32%). These challenges are difficult to overcome in any economy, especially one facing a pandemic. Another challenging area is the inability to be agile with data. While eighty-four percent of respondents experienced greater demand for data insights, sixty-two percent admit a lack of agility in data processes hurt their response to changing business needs. Ensuring high-quality data and agility within data practices is vital to improve customer experience, streamline operations, and accelerate digital transformation. By investing in data management now, businesses can sustain success despite any future market changes that are out of their control. Investing in data now will help businesses weather the next crisis. Over the next six months, sixty-three percent of organizations see data management initiatives becoming more urgent—and the reason is resilience. Nine out of ten businesses are focused on improving data management resilience to at least some degree over the next year. Businesses are investing in several key areas of data management like improving data quality, refining data governance, moving data to the cloud, and automating data processes. With over three quarters of our respondents saying, “investing in data management initiatives today will help businesses better weather the next crisis,” organizations across industries are hopping onto the data train. This means that businesses need the right: People Processes Technology It’s important for companies to invest in the right areas of data today to recognize return on investment more quickly, build data resilience, and secure their future. During the pandemic, businesses continue to struggle with a lack of technology, data quality, and skills. Data validation software verifies data at the point of capture and can automate the data cleansing process, ensuring data pipelines are accurate and contain valuable insights. This will enable team members to analyze and manage valid data and streamline their time to focus on growth-building strategies. The right people, processes, and tools will not only help a business respond to the challenges they face in today’s environment, but also ensure a stable foundation. Now, more than ever before, have we seen the true power of data. With reliable insights, businesses have the strength to confidently pivot strategies as market shifts arise, sustain the impact of the global health crisis, and prepare for what’s ahead. Read the full report to learn how what you can do today to leverage data to respond to the current global health crisis and prepare for tomorrow. Download the research.
Related Posts
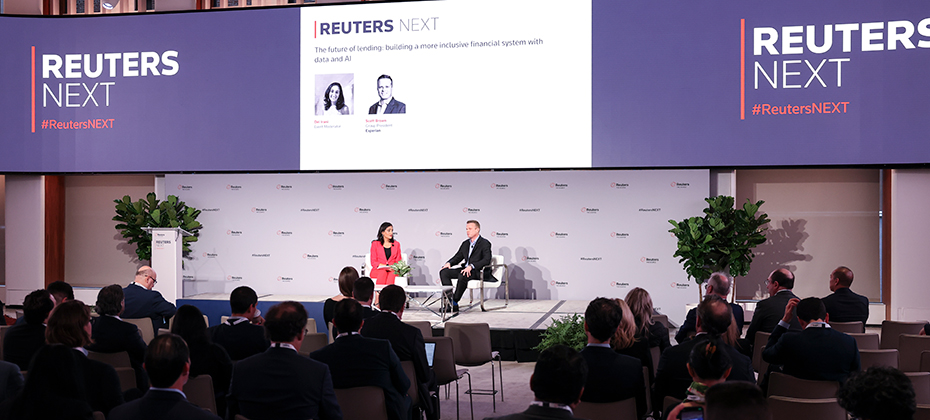
Today, we stand at the forefront of a digital revolution that is reshaping the financial services industry. And, against this backdrop, financial institutions are at vastly different levels of maturity; the world’s biggest banks are managing large-scale infrastructure migrations and making significant investments in AI while regional banks and credit unions are putting plans in place for modernization strategies, and fintechs are purpose-built and cloud native. To explore this more, I recently had the privilege of attending the annual Reuters NEXT live event in New York City. The event gathers globally recognized leaders across business, finance, technology, and government to tackle some of today’s most pressing issues. On the World Stage, I joined Del Irani, a talented anchor and broadcast journalist, to discuss the future of lending and the pivotal role of data and AI in building a more inclusive financial system. Improving financial access Our discussion highlighted the lack of access to traditional financial systems, and the impact it has on nearly 100 million people in North America alone. Globally, the problem affects over one billion people. These people, who are credit invisible, unscoreable, or have subprime credit scores, are unable to secure everyday financial products that many of us take for granted. What many don’t realize is, this is not a fringe subset of the population. Most of us, myself included, know someone who has faced the challenges of financial exclusion. Everyday Americans, including young people who are just starting out, new immigrants and people from diverse communities, often lack access to mainstream financial products. We discussed how traditional lending has a limited view of a consumer. Like looking through a keyhole, the lender’s understanding of the person in view is often incomplete and obstructed. However, with expanded data, technology, and advanced analytics, there is an opportunity to better understand the whole person, and as a result have a more inclusive financial system. At Experian, we have a unique ability to connect the power of traditional credit with alternative data, bringing a more holistic understanding of consumers and their behaviors. We are dedicated to leveraging our rich history in data and our expertise in technology to create the future of credit and ultimately bring financial power to everyone. The future of lending After spending two days with over 700 industry leaders from around the world, one thing is abundantly clear: much like the early days of the internet, today, we are at the cutting-edge of a technical revolution. Reflecting on my time at Reuters NEXT, I am particularly excited by the collective commitment to drive innovative, and smarter ways of working. We are only beginning to scratch the surface of how data and technology can transform financial services, and Experian is positioned to play a significant role. As we look to the future, I am excited about the ways we will create new opportunities for businesses and consumers alike.
We believe that financial literacy leads to empowerment. That is why Experian supports initiatives and partners with community organizations to deliver financial education. We also develop products and services that give more control to consumers over their credit profile and financial health. As part of advancing our mission of Financial Power to All®, we are proud to announce we are helping more than 5,000 Hispanic individuals nationwide by relieving $10 million dollars of consumer debt. To provide families with this boost, we joined forces with ForgiveCo, a Public Benefit Corporation (PBC), to administer the acquisition and cancellation of qualifying consumer debt for the selected recipients. Beneficiaries will also receive a one-year premium Experian membership for free that offers access to their Experian credit report in English and Spanish[i], FICO® Score[ii], bilingual educational content, and other financial resources. We hope this effort helps raise awareness of the importance of financial literacy for everyone, and that Experian has resources to help individuals reach their financial dreams. To amplify the message, we collaborated with multi-platinum, award-winning singer and songwriter Prince Royce and you can see his video here. In fact, we have been making a concerted effort the last several years to evolve our educational resources and products to better support all underserved communities. Some of our other activities include the creation of the B.A.L.L. for Life initiative that connects African American and Hispanic youth with financial education, supporting scholarships for Asian Americans through the Ascend organization, providing custom resources for Out & Equal and Born This Way Foundation for the LGBTQ+ community, supporting the NextGen Innovation Lab for Disability:IN, and sponsoring credit counseling for the military community with Operation HOPE. For resources in Spanish, Experian offers a credit e-book and consumers can access a full suite of articles at the Ask Experian blog here. [i] Only Experian credit reports are available in Spanish. All other services associated with an Experian membership are available in English only. English fluency is required for full access to Experian’s products. [ii] Credit score calculated based on FICO® Score 8 model. Your lender or insurer may use a different FICO® Score than FICO® Score 8, or another type of credit score altogether. Learn more.
Amid some of the financial challenges that underserved communities experience, members across the financial services community remain committed to championing initiatives and programs that drive greater financial inclusion. In fact, collaboration has led to the inclusion of non-debt related payment information on consumers’ credit profiles, as well as digital services that make it easier to manage money. These efforts have helped to broaden access to fair and affordable financial resources for more individuals. While significant progress has been made, there is still more work to do. However, some of the misconceptions and myths about the financial services community are hindering further advancement. Debunking these myths will accelerate progress by building trust between the financial services community and consumers. Person withdrawing money from ATM contactless Myth #1: “Financial institutions have no interest in underserved consumers or credit invisibles.” The truth is, banks and credit unions want to say “yes” to more prospective borrowers, including individuals and families from underserved communities. Beyond being the right thing to do, it’s an opportunity to potentially build lifelong relationships with a relatively untapped market. A show of good faith to communities who have largely been ignored by the financial system could lead to customer loyalty that may extend to their family and friends. That’s why participants across the financial ecosystem have been proponents of including expanded data sources—such as on-time telecom, utility and video streaming service payments—on to consumer credit reports, as well as exploring other Fair Credit Reporting Act (FCRA)-regulated data sources, including payment data on short-term small dollar loans and expanded public records data. Making this data more accessible to lenders provides a more comprehensive view of a consumer’s ability and willingness to repay outstanding debt—an actionable solution to extending credit to consumers without lenders taking on additional risk. Myth #2: “There is a lack of trustworthy financial education resources.” The financial services community and affiliated organizations recognize that empowering people with financial knowledge and skillset are critical to consumers’ financial success. In fact, banks and credit unions are partnering with nonprofits and non-governmental organizations to better understand the unique challenges and opportunities within specific communities and provide relevant tools and resources. For example, Experian’s B.A.L.L. for Life (Be A Legacy Leader) program, launched in partnership with the National Urban League, serves as a catalyst for engaging with Black communities and low-income youth through live events and digital financial education. Subject matter experts, professional athletes, celebrities, and other influencers share their experiences and expertise, covering topics such as banking, credit, financial management and investing. In addition, to help people improve their financial management, Experian partners with the National Foundation for Credit Counseling (NFCC). The NFCC connects consumers with certified financial counselors to help them address various pain points, including debt management, homeownership, student loans or small business cash flow issues. Myth #3: “Underserved communities have few opportunities to build credit and enter the mainstream financial system.” People from underserved communities, as well as younger consumers and recent immigrants are often excluded from the mainstream financial system because they lack an extensive credit history. Historically, it’s created a vicious cycle; in order to get credit, you have to have credit. Fortunately, there has been a sea change in innovative solutions to address the specific needs of these populations. These include new credit scoring models and microfinancing which provide financial services to individuals who may have been excluded from traditional banking systems. In addition, by incorporating expanded data sources, such as telecom, utility and residential rental payments onto credit reports, lenders have more visibility into consumers who may have been excluded by traditional credit scoring methods.These programs help individuals and families from underserved communities establish and build a credit history that could enable loans, or the ability to rent an apartment or open their dream business. An example is Experian Boost®, a free feature that allows Experian members to contribute their history of making utility, cellphone, insurance, residential rent and video streaming service payments directly into their Experian credit profile. By incorporating nontraditional credit data like paying utility bills on time, online banking transactions, rental payments and verified income data, more people can establish a credit profile that can potentially qualify them for a loan. More Inclusion, Fewer Myths It’s encouraging that community organizations and banks are beginning to see the economic and social benefits of aligning on financial literacy and inclusion. As more initiatives come online, underserved populations will be able to establish a better financial foundation. Then, we can declare the myths to be history.