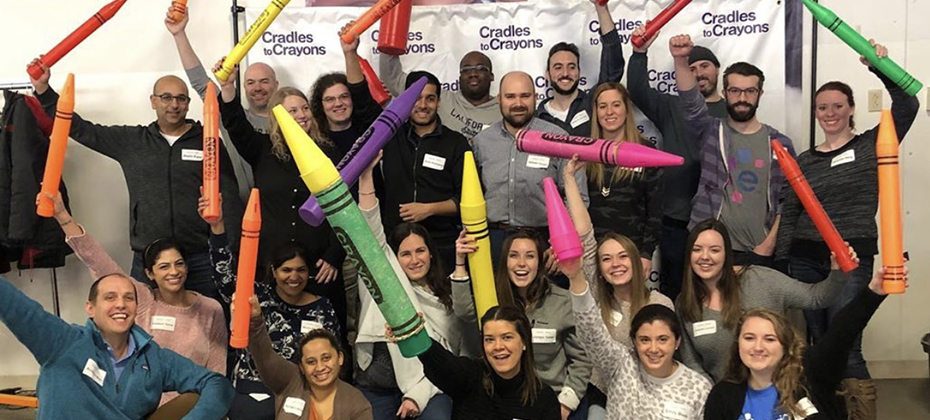
For the eighth consecutive year, the Orange County Register has named Experian as one of the Top Workplaces, with the company securing the #1 ranking for the second time in three years. The award, which is based on employee feedback in a survey of hundreds of leading companies in Orange County, recognizes our company’s culture of innovation and inclusion, and our commitment to employees and communities during the pandemic. For more than 40 years, Orange County has been at the heart of our North America operations, and as we persevere through these challenging times, we are especially honored to be recognized for our dedication to maintaining a healthy, collaborative work environment and achieving higher performance while giving back. This award demonstrates the resilience, talent and compassion of all the people who work here at Experian. Since the start of the pandemic, we have further expanded our dedication to social good by creating new opportunities to support employees and the broader community. Because we are founded on a culture of innovating through bringing together technology and data, we were able to quickly respond to COVID-19 and honor our commitment to using data for good. Maintaining company culture All our decisions are driven by our desire to lead with empathy, and ensuring our employees feel valued and protected, while simultaneously mobilizing our resources to positively impact society, creating greater levels of financial and social inclusion. Although we had technology in place to easily initiate working remotely, we supported the transition to remote working by launching initiatives dedicated to mental and physical well-being, including a COVID-19 Resource Center, enhanced sick-leave policies, increased opportunities to ensure continuity of professional development, as well as an ASPIRE to be Well guide, in partnership with our Employee Resource Groups (ERGs). Giving back Throughout the pandemic, our employees have felt compelled to help clients who were facing unprecedented and unforeseen challenges. Different groups and employees of all levels began working together to develop new products and services to help clients, customers and communities persevere. This included free credit reports for small business, adding video streaming service payments to Experian Boost, hosting #CreditChat on social media, the Experian CORE heatmap, COVID-19 U.S. Business Risk Index , Experian® Health Payer Policy Alerts and updated fraud protections through the Business Resources Website. As part of our United for Financial Health initiative, we also launched two new partnerships with non-profit organizations to empower vulnerable consumers and those marginalized by the pandemic. In collaboration with Operation HOPE, we are helping vulnerable communities improve financial health with its data, analytics, products and services. Most recently, we partnered with NAACP Empowerment Programs to offer Home Preservation Grants to African Americans at risk of losing their homes. Although COVID-19 has been a source of stress and anxiety for businesses and individuals alike, we remain committed to helping employees reach their full potential and demonstrating that values and purpose do not change in a crisis. We are honored that the Orange County Register is recognizing our tireless efforts to make a difference in the communities in which we live and work.
Almost a year worth of a global pandemic has galvanized a past of relative stability and predictability, bringing chaos and disruption and signaling a different, certainly unexpected, future. As this future unfolds, it will be the actions that business leaders and their teams take now, amidst the crisis, that will determine the fate of their organization. Navigating the current complexity and change requires the ability to effectively address the urgent needs of the present, make immediate choices, and allocate resources. The pace is fast, and actions are decisive – in fact, companies have acted 20 to 25 times faster than expected since the coronavirus pandemic started, according to McKinsey[1]. Modern decision automation facilitates technology and business strategic alignment This search for increased nimbleness and improved strategic alignment has been a recurrent topic in our conversations with clients from around the globe. What we hear is that the pandemic has boosted their search for solutions that create synergies across technology and business groups and allow for an optimal use of their IT investments. As organizations are accelerating and driving their digital transformation, they are pursuing simpler fit-for-purpose solutions to lower their costs, drive internal alignment and operational efficiencies, and help them meet and exceed all-time high customer expectations in less time. Decision automation platforms such as Experian PowerCurve bring all those elements together, taking the complexity out of the customer decision making process. This crisis has accelerated the need for automated decision management solutions that are secure, can easily scale to meet emerging needs and changes in demand, and be upgraded seamlessly to avoid getting stuck on outdated software and unnecessary long and complex IT infrastructure overhauls. That sheer need for readiness has led to more, accelerated digital transformation. McKinsey Global Survey of Executives[2] shows that companies have accelerated the digitization of their customer and supply-chain interactions and of their internal operations by three to four years. Additionally, the share of digital or digitally enabled products in their portfolios has accelerated by seven years. These findings suggest that during the crisis, companies have prioritized refocusing their offerings to solve for the needs at hand rather than made huge leaps in product development in the span of a few months. With 60% of consumers having higher expectations[3] for their digital experience than before Covid-19, businesses big and small are acutely aware they must reshape their customer journeys to come out of this crisis reinforced. That requires the ability to access and manage more data sources, more attributes, more advanced analytics faster, more easily, and through a more consistent customer experience. It ultimately requires a platform that enables decision management in a digital world. In this regard, Forrester Research states in its new report; The Forrester Wave™: Digital Decisioning Platforms, Q4 2020[4], that “Experian’s PowerCurve really shines at keeping the leaders who are accountable for business results in control of decisioning by providing transparency into the decision logic and insight into actual results.” The capability to ingest and analyze high volumes of owned, third-party, and alternative data combined with seamless and flexible customer consent and protection enables faster, more effective and accurate credit decisioning, resulting in better risk management for the organization and better outcomes from clients. Technology has been fundamental in helping weather past crises and emerge stronger each time Of the hundreds of organizations currently using our decisioning software and platforms, some are prioritizing speed, like many community banks stepping up to support consumers going through hardship in a matter of weeks. Others such as Standard Chartered leverage Experian’s credit decisioning technology and machine learning capabilities to drive financial access in underbanked communities. For global financial institutions and leading retail brands, it’s all about regaining control over how and when they deploy the most relevant credit decisions and strategies while leveraging their existing data. They especially appreciate PowerCurve’s business-user-focused tools, which have received industry recognition[5] for the way they enable organizations to design strategies, including decision logic that can leverage machine learning models pretrained on prior customer behaviors. Many found in our cloud-based pre-configured data and decisioning capabilities the best way to solve for their customers’ immediate needs. It’s the case of AU Bank in India, where they leverage our standard, ‘out-of-the-box’ applications to accelerate their own transformation and continue to redefine the banking experience for consumers in the markets they serve. Other clients with sophisticated, decision-driven business processes prefer highly configurable solutions for their business-users to help them address specific needs. Personally, I feel energized by this challenge and excited about our commitment to helping more businesses find new ways to meet and exceed today’s consumer demands. Through our decisioning platform, organizations can listen to their customers, adapt their business models, adjust their offerings and innovate to drive a strong top line so they are better positioned down the road to recovery. Our decisioning solutions span the entire customer lifecycle and are used by credit and risk managers as well as developers to increase the knowledge about customer and market needs and be ready to solve today’s challenges and take on tomorrow’s opportunities. 1 McKinsey Global Survey of Executives, October 2020. 2 How COVID-19 has pushed companies over the technology tipping point—and transformed business forever. https://www.mckinsey.com/business-functions/strategy-and-corporate-finance/our-insights/how-covid-19-has-pushed-companies-over-the-technology-tipping-point-and-transformed-business-forever 3 Experian Global Insights Report September / October 2020 https://bit.ly/GIR_sep-otc 4 The Forrester Wave™: Digital Decisioning Platforms, Q4 2020 5 Experian’s profile, The Forrester Wave™: Digital Decisioning Platforms Q4 2020” Report.
There’s no question the COVID-19 pandemic is contributing to a unique 2020 holiday season, but there are consistent truths that remain when it comes to the holidays and personal finance. While the season is known for being merry and bright, sadly, financial challenges and stress are equally common for many this time of year. According to our latest holiday spending survey, 60% of consumers feel stressed about their finances during the holiday season and half feel the extra expense of the holidays makes them hard to enjoy. More than half (52%) say COVID-19 has caused credit or financial barriers which are preventing them from doing their shopping the way they had planned. At the same time, 62% agree holiday shopping puts a strain on their finances. In an effort to alleviate some of the financial stress some may be facing, I wanted to share three ways you can protect your financial health this holiday season and prepare for a financially healthy new year: Start with a budget and a plan. It’s easy to lose track of spending and take on unexpected debt during the holidays, which is why creating a budget is an important first step to protect your financial health. Experian research shows the average American plans to spend $775 on holiday gifts this season, but your holiday budget will depend on your unique financial situation. Outline how much you can realistically afford to spend and try to factor in expenses that are sometimes overlooked, which can be a challenge. In fact, our research found four out of five consumers often run into unexpected expenses they hadn’t planned for, including buying unexpected gifts (25%), gift wrapping supplies (25%) and mailing costs for sending gifts (21%). Once you’ve outlined your budget, creating a plan for who you need to shop for and where you’re going to shop can be a helpful next step. Our survey showed 62% of consumers plan to shop more online this year due to COVID-19. If you’re planning to do more shopping from the comfort of your home this year too, tracking online sales and promotions can help you save money, and factoring in shipping costs can help keep your holiday budget on track. Setting a budget and sticking to it, and having a shopping plan to avoid impulse buying will help keep you from falling victim to the pressure of overspending around the holidays. Use credit as a financial tool. Over half of shoppers say they will use credit cards and not cash when holiday shopping. This is an 8% increase from 2019. While using credit wisely is important all year, this is especially true around the holidays. The key is strategic use of credit – whether using a card that provides low interest, rewards points, or cash back – to improve the shopping experience and stretch your dollars. Over a quarter of people say they plan to open a new credit card for the holiday season, which is a 5% increase year-over-year. The top reasons for wanting to open a new card include seeking a promotional no annual percentage rate (APR) credit card, wanting to get a retail store discount, and maximizing spending by getting a card with cashback rewards. If you’re considering applying for a new credit card, improving your credit score can help you take advantage of the best credit offers this holiday season. Experian Boost allows you to get credit for paying your telecommunications, cell phone, utility bills, and streaming services payments on time. More than 4.9 million consumers have connected to the service since March of 2019 and about 61% of those who use Experian Boost see their scores improve. When you’re ready to explore credit card options, Experian’s free Credit Match program can help you find personalized credit card offers based on your unique credit history. Remember, credit is a financial tool, debt is a financial problem. Debt you can’t repay will certainly bring down one’s holiday spirit. If you don’t have a plan for paying off your credit card, using credit may not be a good idea. Protect your identity. The holidays may be the riskiest time of the year when it comes to identity theft and credit fraud. Identity thieves of all sorts are aware that consumers spend significantly more during the holiday season. While many of us are hunting or scrolling for the perfect gifts for friends and family, fraudsters are hard at work too. The number of consumers surveyed who have been identity theft victims during past holiday shopping seasons jumped to 24% from 12% in 2019. The holidays are always a ripe time for cybercriminals with the increased online traffic and this is especially true against the backdrop of COVID-19. To protect yourself from identity theft while shopping online, avoid using public WiFi networks, create strong passwords for your online accounts, and only shop on secure websites you are familiar with. If you are shopping at a store, be sure to cover your credit card information when you enter it, or your personal information if you are applying at the point of sale. Shoulder surfers can use their phones to take a quick photo or video to steal your identity. Also avoid leaving your purse or wallet, or any documents in your car. Identity thieves stalk parking lots looking for opportunity that is just a broken window away. Credit cards offer more protection for both online and in-person purchases than your debit card or cash, so consider using credit for your purchases. If fraud occurs, the money is not gone from your checking account and you can file a claim with your card issuer. Pay the balance in full right away to avoid interest charges. Checking your credit report often can help you spot fraudulent activity. You can get a free credit report from all three bureaus at AnnualCreditReport.com through April 2021. Identity theft monitoring is an easy way to monitor your financial accounts and credit report to identify possible fraud such as a credit card account opened in your name. While the holidays may look a little different this year when it comes to protecting your financial health the same rules still apply. For more information about how to protect your credit history in 2020 and beyond, visit www.askexperian.com or join our weekly CreditChat every Wednesday on Twitter at noon PST/3 p.m. EST.
At Experian, our mission is to increase financial inclusion by empowering consumers. Through our corporate responsibility work, we have always been committed to using our resources to help more people improve their financial health through non-profit partnerships, data analytics, products and services, volunteering and educational programmes. Now, we have an opportunity to reach even more people in hugely underserved communities. Experian has launched the global United for Financial Health project to empower vulnerable people to improve their financial health through education and action. Through the United for Financial Health programme, Experian is partnering with non-profit organizations across the globe to deliver tools and resources to help those affected the most, and certainly, COVID-19 has amplified the need. We have already launched our first three partnerships in the U.S: Operation HOPE – an organisation whose aim is to uplift disenfranchised youth and adults from poverty to thriving in a credit ecosystem. One of the goals of the partnership is to help ethnic minority groups who are struggling to raise and sustain a 700-credit score or higher. By helping people raise their credit scores we can shift their mindset from one of “survival” to “thriving” and make a real difference in their lives. For some, a higher score may mean the ability to purchase a new car, have a credit card, own a home, or simply save money for their family. Black Girl Ventures – a non-profit that advocates for Black and Brown women entrepreneurs and their small businesses. Our partnership will provide financial resources to help scale its BGV Style Pitch Competition and Amplify BGV Programs and we are a proud sponsor of BGV’s new weekly podcast, “From Hustling to Handling, How to Stay in Business.” Together, we will curate entrepreneurial education content to assist a broader audience with knowledge and best practices related to financial literacy and wealth management. NAACP Empowerment Programs – part of the largest and most pre-eminent civil rights organization in the U.S. Our partnership creates The Home Preservation Grant, which will provide grants to African American homeowners at risk of losing their homes because of COVID-19-related hardship. In the UK, we are delighted to launch a new partnership with the charity National Numeracy. Numeracy is the strongest predictor of a person’s financial literacy and is therefore crucial to their financial health. However, poor numeracy is widespread, and disproportionately affects low-income communities where people are most at risk of marginalization from the COVID-19 pandemic. Thankfully, confidence and competence with numbers is within everyone’s grasp, with the right support. Working together, we can inspire and support over 60,000 people to take positive steps towards building their confidence and competence with numbers, helping many of those most affected by this crisis take their next step towards improved financial health. We have already made good progress in a relatively short space of time and will continue to invest our energy into building further partnerships to reach more people in need of support. This is just the beginning of our journey, but we are confident that we can make a huge difference to millions of people in communities across the globe.
I still remember buying my first home in Southern California in my mid 20’s. After going through countless open houses and unfamiliar living rooms, I found a home that met my needs. I decided to take the plunge, put an offer in, and hope for the best. It was a roller coaster of emotions – excitement, fear, joy, and pride. Owning a home is considered a mark of financial achievement. It not only builds generational wealth but also contributes to the generational vibrancy of communities. For many, the COVID-19 pandemic has pushed that dream further out of reach or threatened to take it away. That’s why we are thrilled to announce the launch of the Home Preservation Grant. We are partnering with the NAACP Empowerment Programs for this pilot program, which will provide up to $10,000 in grants to select African American homeowners at risk of losing their homes because of COVID-19-related hardship. The Home Preservation Grant is part of our United for Financial Health program here at Experian, which aims to empower and protect vulnerable consumers to improve their financial health through education and action. For this pilot, we are targeting homeowners in the Atlanta, Ga. area and we plan to expand the program to other cities across America in the future. The application process is open now and ends on December 8. Grant recipients will be announced on December 14, providing what we hope will be some much needed relief in time for the holidays.
2020 has been a year that has significantly impacted us all and the shockwaves are likely to challenge us for some time to come. One of the big disappointments for the data and tech industry is the postponement or cancellation of a number of major events – including the likes of Women in Data, which Experian was a proud Gold sponsor in 2019. Although we are not able to celebrate the Women in Data flagship event in person this year, we are thrilled to be an official partner of the very first WiD Week. This is a fantastic opportunity that will allow us to virtually gather together, support each other, and learn while in a safe online environment, driven by content that the Women in Data community needs right now. We are particularly excited to be hosting a session on Tuesday 24 November, which will focus on our support of Girls in Data. In this session, Experian’s Emily Capewell and Louise Maynard-Atem will be providing some thoughts on their involvement with the recent data challenge we hosted during the last lockdown. The data challenge was designed to help inspire young girls and boys to pursue a career in STEM. Louise will also be speaking on Thursday about her experience of 2020 and how we can action change as we head into 2021. This will be one of six short stories to mark Women in Data’s sixth birthday. We are extremely excited to be involved with WiD Week and while it will be slightly different this year, we hope our involvement can help empower and encourage more women into the data industry, supporting the next generation of data scientists who can help shape the future. You can find out more about WiD Week here.
For the past several years, Experian has been on a journey to help drive financial inclusion for millions of people around the world. This has required significant focus on how we operate, who we partner with, and the products and solutions we offer. Four years ago, when we decided to partner with and invest in Finicity, a leading financial data aggregator based in Salt Lake City, we did so on our strong belief in consumer-permissioned data and our shared vision with their leadership team. At the time, we knew Finicity’s commitment to empower consumers and drive the digital revolution fit perfectly with our priorities. Over the years, this has proven to be true time and time again as we’ve leveraged Finicity’s technology capabilities to create enormous opportunity for our clients and improve financial access for consumers. One example is our partnership on Experian Boost. With the support of Finicity’s infrastructure, more than 4.9 million consumers have connected to Experian Boost to contribute their on-time payments for their telecommunications, utility, streaming service and cell phones directly to their Experian credit reports. Through Experian Boost, and access to real-time consumer-permissioned data, we are increasing financial inclusion by helping lenders identify more consumers who can pay responsibly. In an equally powerful testament to the power of consumer-permissioned data, our partnership with Finicity is helping streamline the homebuying experience for consumers and lenders. As a distribution partner of Finicity’s Verification Solutions, we are delivering Verification of Assets (VOA), Verification of Income (VOI) and Verification of Income and Employment (VOIE) to the mortgage market. This innovative digitization of data and analytics is streamlining experiences for borrowers and is a critically important step in modernizing the mortgage process. Additionally, we have clients successfully utilizing Finicity’s Verification Solutions in automotive underwriting, personal lending, tenant screening and other sectors. Earlier this week, Mastercard closed its acquisition of Finicity. This move, along with the overall trajectory of market demand, is testament to the fact that we clearly invested in the right capability, the right team and the right vision at the right time. But our journey together isn’t over, it has just been reinforced and will continue with Finicity even under new ownership. Our commitment to working with Finicity does not change with this news, it is only enhanced. Our drive to accelerate digital lending, empower consumers and drive more consumer-permissioned data solutions is higher than ever. We will continue to partner with Finicity, now part of the Mastercard family, as a central component of our strategy. We look forward to a continued strong relationship with this new, combined entity as we continue to bring innovative solutions for consumers and businesses to the table.
Tens of millions of workers in the U.S. found themselves unemployed earlier this year, as the COVID-19 pandemic caused job loss rates not seen since the Great Depression. While average Americans were reaching out to their state agencies seeking assistance, fraudsters saw unprecedented opportunity. It may be difficult to imagine why someone would take advantage of a system striving to help those in need, but cybercriminals often thrive in times of crisis. At Experian, we took notice as we began to hear from states about a significant uptick in fraudsters wrongfully claiming benefits. When it comes to innovation, we strive to be agile and nimble so we can adapt to the changing needs of consumers and businesses. As a result of COVID-19, one of those emerging needs is to join the fight against unemployment insurance fraud. That’s why Experian has partnered with the Unemployment Insurance (UI) Integrity Center to help mitigate unemployment insurance fraud. Together, we will provide state agencies with a centralized platform to verify identities that are applying for unemployment insurance. The new partnership will combine Experian’s Precise ID® solution, which integrates identity analytics with advanced fraud risk models to distinguish various types of fraud, with the UI Center’s Identity Verification (IDV) capability. In short, when state agencies submit claims, the IDV solution will return ID theft scoring and associated cause codes, enabling them to assess whether a claim may be fraudulent. This can be easily implemented by any state UI agency through the Center’s Integrity Data Hub. While mitigating fraud is top of mind, security is a top priority as well. The platform was designed and built using the latest National Institute of Standards and Technology IT security standards to ensure the security of sensitive data. With the number of unemployment claims remaining high, it’s clear that state agencies must maximize their time and resources. Fortunately, the solution powered by Experian’s Precise ID will be available to state agencies at no cost through UI Integrity Center, operated by the National Association of State Workforce Agencies (NASWA) in partnership with and funded by the U.S. Department of Labor. This is one of many steps we’re taking at Experian to combat fraud, and we will continue to innovate and adapt on the road to recovery ahead of us. As we move forward together, Experian is committed to leveraging innovation and technology to protect consumers and help businesses meet the challenges of 2020 and beyond.
We know small businesses are critical to the vibrancy of our economy and communities. Watching how hard the COVID-19 pandemic has affected them and their founders has been troubling. Here at Experian, we created new tools to help small businesses navigate this uncertain time. But we want to do more, and help businesses survive and thrive even in “normal” times. That’s why I’m especially excited about our newest partnership with Black Girl Ventures (BGV). This is part of our United for Financial Health program, which aims to empower vulnerable consumers to improve their financial health and protect them from fraud and identity theft. Through this partnership,we will provide resources, tools and services to Black and Brown women entrepreneurs to enable them and their small businesses to grow and prosper. We know that long-standing inequities have created barriers for women, especially women of color. Our partnership will provide financial resources to help scale its BGV Style Pitch Competition and Amplify BGV Programs and we are a proud sponsor of BGV’s new weekly podcast, “From Hustling to Handling, How to Stay in Business.” Together, we will curate entrepreneurial education content to assist a broader audience with knowledge and best practices related to financial literacy and wealth management. The negative financial impact on these women and their businesses has had a reverberating effect across communities of color. Our United for Financial Health program is one of the many ways we are staying true to our mission to support all consumers and clients through their financial health journey, in normal and extraordinary times. This partnership with BGV will fuel the economic recovery by reaching millions of Black and Brown women entrepreneurs and, in turn, supporting the communities they serve.
As businesses across the globe have started to see their operations stabilize, they will be tested once again as the world faces another resurgence of the Covid-19 but this time consumer expectations will be much higher. According to the latest Experian’s Global Insights Report, 60% of consumers have higher expectations of their digital experience than before Covid-19. The study which surveyed 3,000 consumers and 900 businesses in 10 countries, including: Australia, Brazil, France, Germany, India, Japan, Singapore, Spain, the United Kingdom and the United States, found that while many consumers may have stayed loyal to businesses they frequented before COVID-19 initially, that may no longer be the case. High expectations for security and convenience compounded by the increased demand for online payments, banking and shopping are pushing businesses to re-imagine the customer journey and the investments needed to drive future growth. In fact, the study found that one in three consumers are only willing to wait 30 seconds or less before abandoning an online transaction, specifically when accessing their financial accounts. This means that businesses have an increasingly short time frame to prove the experience will be safe and convenient. Businesses have no choice but to invest in their digital presence and experience. We believe the cost of doing nothing will be greater than what it will cost to invest in the customer journey. While half of the businesses we surveyed have either mostly or completely resumed operations since Covid-19 began, only 24% are deliberately making changes to their digital customer journey. This is not enough. The integration of data, analytics and technology is the key to enable businesses to quickly adapt decisioning strategies to minimize risk, preserve valuable relationship and remain fair and compliant. In order to strengthen digital transformation, Experian recommends that retail banks, payment providers and retailers consider the following: Understanding the customer Businesses need to understand their customers more than ever before. They need to understand their behaviors, preferences, and financial situation. Each transaction creates hundreds of different touchpoints that financial institutions and retailers need to accommodate across all devices. The tricky part is using the right technology to put all the datapoints together and to link them into one single-view of the customer. Use of AI to improve and automate customer decisions Being able to make the right decision is more important than ever. Today’s economic conditions are unprecedented, and unfortunately we don’t have historic data to count on. Therefore, we need to use data and technology better than before. In the area of artificial intelligence, businesses are strengthening the security of mobile and digital channels, new credit risk analytics and artificial intelligence (AI) models and increasing digital customer acquisition and engagement. Strengthening security of mobile and digital channels Businesses need to provide not only a convenient experience but also a secure one. In order to improve security, businesses need to use a multi-level approach where they can easily access and layer fraud solutions to catch more fraud and reduce friction for genuine consumers. Discover more insights from our longitudinal study of the impact of Covid-19 on businesses and consumers.
I was recently invited to a panel discussion as a part of Money 20/20 titled Do Credit Scores Still Matter? Closing the Chasm through Data and Innovation with Lauryn Nwankpa, Head of Social Impact at Dave and Jay Moon, General Manager of Credit at Credit Sesame. We discussed how important data and innovation are right now to ensure that consumers get access to credit that they need. As the largest credit bureau in the country, and in service of our mission to be the consumers’ bureau, we at Experian have a responsibility both to consumers seeking credit and to lenders who seek to assess the risk that a loan applicant represents. As part of this, we’ll continue to extract value from the data that lenders are used to getting from us and we innovate by providing new forms of data that can help the many Americans who either face barriers or sometimes pay more for credit because of a lack of credit history or having a credit file that’s too thin. I’m especially passionate about this as I myself was an immigrant and a thin-file customer at one point. When I came to this country, it was incredibly hard for me to develop a credit profile that I felt accurately reflected my financial situation and the (lack of) risk that I, as a borrower, would represent. But I was lucky as my first lender at the time was patient, just as I needed to be. They spent months seeking additional information about my situation, eventually enough to extend a firm offer of credit. It is not only immigrants who may face this or similar challenges. The impact of COVID-19 has created a difficult economic reality for many Americans. At Experian, we’re dedicated to having a culture of continuous innovation, from the way we work to the solutions we create to help consumers on the road to recovery. Especially during times of economic uncertainty, finding innovative means to effectively assess the creditworthiness of these consumers is critical. That’s exactly what we focus on at Experian in order to help consumers gain financial access and stability. Alternative data plays a critical role in achieving this. We’re finding new ways to use consumer-permissioned and alternative credit data in the credit scoring process, which can help lenders identify consumers who are excluded from the traditional credit ecosystem, but who can fulfill their financial obligations. I’ve seen firsthand how our data and technology can help transform the way businesses operate and have spoken to many consumers who leveraged our innovative services to help them thrive in society. Consumers want to be in the driver’s seat of their credit journey and we’re seeing a greater openness to providing data, which in turn enables lenders to make more informed decisions. This change is disrupting the status quo. Experian Boost is a great example of this. It’s a free and first-of-its-kind financial tool that empowers consumers to add positive telecom, utility and Netflix payment histories directly into their Experian credit file for an opportunity to instantly increase their FICO Score and access quality credit. More than 2.5 million have seen their scores improve with Experian Boost. So, do credit scores still matter? My answer is that credit reports are more relevant than ever. They matter more than the score alone as they detail a consumer’s financial track record and deliver a historical view of how a consumer is managing and repaying debt over time. This information helps lenders determine who can fulfill their financial obligations and ensures consumers continue to have access to credit so I don’t believe credit reports are going anywhere. As we navigate the road to recovery, it will be critical that all of us in the financial ecosystem work together to safeguard consumers and to maintain the integrity and openness of the credit market. The credit report, augmented by consumer-consented and alternative data, is a foundational pillar to achieve both of those objectives.
People’s engagement with financial information and their understanding of how organisations use it to make decisions about the products and services they can access has been growing for many years. Experian has played a role in this journey. We were the first to allow people to view their credit report at any time and see their Experian Credit Score with the launch of CreditExpert in September 2003. It has allowed people to view their own information through a lender’s eyes, so they can understand how to improve their situation. We’re excited to announce the next huge leap forward – the launch of Experian Boost in the UK. Now for the very first time, people can instantly increase their credit score to help them access more financial products and services at better rates. Experian Boost is a free service which allows people to use a secure Open Banking platform to share their everyday transactions – from council tax to digital entertainment subscriptions, such as Netflix and Spotify. These payments have never been factored into a credit score before, so adding them should broaden access to financial services. Our analysis shows that more than 50% of people will see their credit score increase from using Experian Boost. But, crucially, the service will not make people’s score go down when they sign up to Boost. People are also in total control of their data. If they wish, they can withdraw their information with a few clicks, and they are still free to re-join at any time. But by keeping Boost activated on their Experian account they can build a stronger payment history which could help them get their credit card, loan or mortgage they want. We’re confident this is going to be a significant moment in how people represent their financial profile to organisations. Five million people have signed up for Boost in the US since it launched last year, with three million of those seeing their score increase. At Experian, we strive to put people in control of their financial data and the launch of Boost is entirely in line with this goal. Now it’s over to you – give your credit score a Boost.
Related Posts
Experian’s groundbreaking generative AI-powered tool, Experian Assistant, has earned the prestigious 2025 BIG Innovation Award in the Products for Financial Services category. This recognition underscores Experian’s commitment to pushing the boundaries of innovation by helping businesses achieve success and enhancing consumer experiences. The BIG Innovation Awards, celebrated since 2011, honor organizations and solutions that redefine excellence through creativity and measurable impact. Experian Assistant was recognized for transforming how financial institutions approach data and analytics, enabling faster, smarter decision-making that enhances customer experiences and operational efficiency. Redefining Financial Services Integrated with the Experian Ascend Platform™, Experian Assistant functions as a 24/7 data expert, enabling financial institutions to optimize their credit and fraud models with ease. Using natural language processing (NLP), the virtual assistant guides users providing insights, recommendations and coding assistance. The impact is transformative: Experian Assistant cuts model-development timelines from months to just days— and even hours in some cases. By helping users analyze credit and fraud data, adjust model attributes and streamline workflows, it empowers organizations to innovate faster and make data-driven decisions with confidence. Powered by agentic AI technology, Experian Assistant reimagines how data scientists and analysts approach their work. It accelerates insights, fosters collaboration and empowers businesses to deliver exceptional customer experiences while reducing the time and resources needed to bring new initiatives to market. Driving Results Across Industries While tailored for financial services, Experian Assistant’s capabilities extend across industries. Businesses can leverage its tools for data exploration, model deployment, performance monitoring and faster time-to-market for new offerings. With Experian Assistant, users gain a powerful edge in scoring more consumers, optimizing processes and enhancing overall customer satisfaction. Recognized Excellence The 2025 BIG Innovation Awards spotlight trailblazers evaluated on creativity, impact and results by seasoned business leaders. This accolade solidifies Experian Assistant’s position as a game-changing solution in financial services and beyond.
We are thrilled that for the sixth consecutive year, Experian has earned a score of 100 on the Human Rights Campaign Foundation’s (HRCF) 2025 Corporate Equality Index (CEI). This recognition underscores our commitment to LGBTQ+ workplace equality. We are honored to join the ranks of 765 U.S. businesses that have been awarded the HRCF’s Equality 100 Award, celebrating our leadership in fostering an inclusive workplace. Experian’s dedication to supporting the LGBTQ+ community is reflected in several key initiatives: Name Change Process: We have a process for transgender and non-binary consumers to update their names on credit reports, ensuring their identities are accurately represented. LGBTQ+ Allyship 101 Training: This new training program is available to all Experian employees, promoting allyship and understanding within our workforce. Pride ERG Parenting Committee: Launched to support parents, grandparents and guardians of LGBTQ+ individuals, this committee provides valuable resources and community. Transgender Resource Guide: This guide supports employees who are transitioning at work, offering education and resources for colleagues and managers. Partnerships: We collaborate with organizations such as Out & Equal, GenderCool, The Trevor Project and Born This Way Foundation’s Channel Kindness to provide financial health, mental health and other resources to empower both our internal and external communities. At Experian, we are proud to be part of this movement towards greater equality and inclusion. We remain dedicated to fostering a workplace where every employee feels respected, valued and empowered to bring their authentic selves to work. Learn more about how we drive social impact in English, Portuguese and Spanish.
Achieving Top Workplace recognition for 12 consecutive years is no small feat, yet Experian North America has done just that. Named a Top Workplace by the Orange County Register once again, this milestone reflects not just policies or benefits but what truly makes Experian exceptional: our people. As Hiq Lee, Chief People Officer at Experian North America, notes, this honor is a testament to the remarkable contributions of our team. Experian’s employees shape an environment where innovation, inclusivity, and purpose thrive. More Than Work What sets Experian apart is our engagement with the world and community. Through initiatives like the Experian Volunteer Leadership Network and partnerships with organizations such as the Octane Foundation for Innovation and the Hispanic Chamber of Commerce of Orange County Education Foundation, our impact extends beyond the workplace. In 2024, we earned additional recognitions, including being named one of the World’s Best Workplaces™ by Fortune and Great Place to Work®. We were also recognized as one of the Best Workplaces for Parents, Millennials, and in Technology. The Secret to Success Our success lies in focusing on people. Experian is a place where careers are built, ideas are encouraged, and employees feel valued. Initiatives such as, Employee Resource Groups foster belonging, Mental Health First Aiders provide support, and technology hackathons inspire creativity. Innovation at the Core Innovation continues to drive our success. By leveraging technologies like artificial intelligence and machine learning, we are redefining decision-making and fraud prevention. This commitment to innovation empowers businesses and consumers worldwide, aligning with our mission to promote financial inclusivity. Looking Ahead For Experian, being a Top Workplace for more than a decade isn’t a finish line—it’s a springboard. With an ongoing commitment to our employees and communities, we continue to evolve, creating better experiences for our team, clients, and the world.
The rise of Generative AI (GenAI) is fueling a new wave of sophisticated fraud, transforming the financial services landscape. Experian’s 2024 Global Identity & Fraud Report highlights the challenges businesses face, and the strategies needed to protect consumers while maintaining seamless digital experiences. Based on insights from more than 1,000 business and fraud leaders, and 4,000 consumers worldwide, the report identifies three key forces shaping fraud prevention: GenAI-Powered Fraud: Fraudsters use AI to craft highly personalized attacks, exploiting vulnerabilities across the customer journey. Evolving Regulations: Stricter government requirements demand rapid adaptation of fraud prevention strategies. Customer Expectations: Consumers prioritize secure, efficient services. Many abandon brands after poor account-opening or transactional experiences. A Multi-Layered Defense The report emphasizes the need for a multi-layered approach to combat fraud effectively. Businesses are increasing investments in AI, machine learning, and data-sharing networks to detect and prevent fraud in real-time. “Fraud operates across borders and targets various points in the customer journey,” said Greg Wright, Experian’s Executive Vice President of Identity and Fraud. “Businesses must leverage advanced analytics and alternative data to stay ahead of these evolving threats.” Balancing Security and Experience Consumers value security, but demand convenience. Striking the right balance is critical, as many switch providers after experiencing delays or cumbersome processes. Businesses can succeed by: Using Advanced Analytics: Leveraging AI-driven insights to prevent fraud while maintaining smooth customer experiences. Orchestrating Fraud Prevention: Integrating tools to provide a 360-degree view of customers, ensuring fraud detection is seamless and comprehensive. The Path Forward The rise of GenAI fraud underscores the need for global collaboration and innovation. By adopting advanced technologies and prioritizing customer-centric solutions, businesses can protect consumers while fostering trust. Experian’s 2024 report offers actionable insights for navigating these challenges. Download the full report to learn how to outpace fraudsters while delivering secure, seamless experiences.
The advertising ecosystem has seen significant transformation over the past few years, with increased privacy regulation, changes in available signals, and the rise of channels like connected TV and retail media. These changes are impacting the way that consumers interact with brands and how brands understand and continue to deliver relevant messages to consumers with precision. Experian has been helping marketers navigate these changes, and as a result, our marketing data and identity solutions underpin much of today’s advertising industry. We’re committed to empowering marketers and agencies to understand and reach their target audiences, across all channels. Today, we are excited to announce our acquisition of Audigent—a leading data and activation platform in the advertising industry. With Audigent’s combination of first-party publisher data, inventory and deep supply-side distribution relationships, publishers, big and small, can empower marketers to better understand their customers, expand the reach of their target audiences and activate those audiences across the most impactful inventory. I am excited to bring together Audigent’s supply-side network as a natural extension to our existing demand-side capabilities. Audigent’s ability to combine inventory with targeted audiences using first-party, third-party and contextual signals provides the best of all worlds, allowing marketers to deliver campaigns centered on consumer choices, preferences, and behaviors. The addition of Audigent further strengthens our strategy to be the premier independent provider of marketing data and identity, ultimately creating more relevant experiences for consumers. To learn more about Experian and Audigent, visit https://www.experian.com/marketing/ and https://audigent.com/.
Modernizing the conversation around credit and financial literacy is a key commitment for Experian, especially for young adults. That’s why we partner with organizations like the Singleton Foundation to produce “Your World on Money,” to meet young people where they are, with engaging, easy-to-understand video shorts about credit, budgeting, and saving and more. We’re thrilled this commitment and creativity has earned both Gold and Bronze Anthem Awards, which recognize excellence in social good, celebrate the impactful work of organizations and initiatives that are driving positive change. Financial literacy is often not taught in schools, and the language around credit and personal finance can be intimidating. By normalizing these conversations, we hope to inspire confidence and action, helping young adults make informed financial decisions as they navigate life’s milestones. Our United for Financial Health partnership with the Singleton Foundation continues with our new series, the Finance Couch, where college students join our experts on a coach in the middle of a Los Angeles campus to answer their money questions. And our Anthem Award-winning series, HeartBroke, helps couples whose relationships are tested with financial issues to determine if they can work through it or end up HeartBroke(n).
Great Place to Work and Fortune have named Experian as one of the 25 World’s Best Workplaces™ 2024. This recognition highlights more than an award—it shows a commitment to our strong People First culture. Experian Chief People Officer Jacky Simmonds shares insights on how our people across the globe cultivate this culture, staying ahead of the curve through a unique blend of inclusivity, empathy, and a shared purpose. What does it mean to you, and to Experian, to be named among Fortune’s World’s Best Places to Work? At Experian, we have long aspired to be one of the best companies in the world to work for, and over the past few years, we have made this a priority. Our journey has been marked by a commitment to putting our people first and fostering the collaborative and inclusive culture that sets us apart. This recognition reflects the common values that we share across our many countries and cultures and the dedication of our colleagues across our business. We spend so much of our time at work, so I think it’s important that every interaction – from the interview process to joining and every daily interaction – is a positive one where people are welcoming, supportive and generally just really nice people to work with. Reaching this milestone gives all of us at Experian some recognition, but also it is inspiring as we continue to strive to attract top talent who share our values, share our purpose and make every day an enjoyable one. How does Experian create an environment where employees feel empowered to innovate and contribute ideas that drive real impact? To fulfill our mission of bringing Financial Power to All™, we need as many voices, experiences and backgrounds as possible, so we can represent our clients’ differing needs. This culture of inclusion drives our innovations. We have employee-led initiatives, such as internal Hackathons that bring together these diverse perspectives to develop products and services like Experian Boost, Experian Go, Experian Smart Money Digital Checking Account, Experian Support Hub, and Transforme-se so we can serve the communities in which we live and work. How has Experian adapted to changing employee expectations since the pandemic, and what steps has the company taken to support employee well-being and work-life balance? We know that our people really value the ability to have flexible work model, so they can work to fulfill their role in a way that works for them. For some this is fully remote, for others it is hybrid so a balance of remote and in office, and for others in office, where their role requires it fully. We know from the feedback that we get that our people appreciate that we trust them and they have flexibility to deal with varying commitments that we all have outside of work. We also know that since the pandemic there has been an increased focused on wellbeing. Sponsored by our Chief Financial Officer, we embarked upon an initiative to invest in how we support people who may need additional support. We are very proud of our Mental Health First Aiders programme, which has trained around 400 colleagues across the world representing 23 countries and 28 languages and helping their teammates access resources. These volunteers receive consistent, ongoing and updated training. What specific initiatives or programmes at Experian do you believe set the company apart in terms of supporting professional growth and career development? We have invested in a number of things that we believe really make the difference. The first is developing great leaders at every level. Today’s leaders have many more challenges, many different age groups, a balance of remote and in person working, together with teams based in many different locations. Great leaders build great teams, so we think it’s important to invest in their development. That’s we built a leadership development portal – The Leadership Exchange – that has a wide range of resources to support them, including development programmes tailored to their needs. We also want to ensure that everyone at every level can develop their skills and progress their careers. So we launched our annual Global Careers Week, Experian University, and built a world-class digital curriculum so everyone can access the form of development they need based on their role or aspirations. There really is something for everyone. This way, we help our teams stay ahead of trends and ensure our business is equipped with the skills needed for the future. Looking forward, what are key goals or priorities for further enhancing Experian’s culture and employee experience? We’re truly proud of this amazing recognition, but we always strive to get better and acknowledge there’s always more to be done. We see an opportunity to make things easier in the way we leverage advanced technologies like AI to further enhance employee experience. For example, more personalised learning pathways, improved tools for productivity and collaboration. We make sure we don’t lose the human touch, but we also want to make the most of these innovations so we stay relevant with our largely tech populations. Being named one of the world’s best workplaces reflects Experian’s unwavering commitment to be recognized for having a great culture where people can do their best work with people they enjoy working with. Learn more about what makes Experian a World’s Best Workplace in the People section of our Annual Report and the Experian Power of YOU Report 2024: Driving social impact and diversity, equity and inclusion, available in English, Portuguese and Spanish.
While the credit reporting industry is designed to help lenders and creditors minimize risk and assess consumers’ ability and willingness to repay outstanding debt, let’s be clear: the consumer is our main priority. Every lending decision and action is made with the consumers’ best interest in mind. Because consumers rely on credit and other loan products to purchase homes and cars, pay for college, afford goods and services, and even bridge the gap during emergencies, the credit reporting industry has been at the forefront of broadening access to fair and affordable financial resources. Risk-based pricing has made it possible for more consumers to access credit, particularly those with limited-to-no credit history or subprime credit profiles. Previously, lenders may have opted not to extend credit to consumers considered higher risk; but more and more, lenders are empowered to tailor borrowing terms based on a consumer’s credit history. In addition, because lenders don’t have to absorb unforeseen risk, lower borrowing costs can be maintained for all consumers. Experian has long advocated for expanded data sources, such as rent and utilities payments, to be incorporated onto consumer credit reports and considered in lending decisions. In 2019, we launched a product that empowers consumers to add positive payment history for utilities, telecoms and video streaming services—and eventually residential rent—directly into their Experian credit report. Our efforts coincide with legislation, such as S.2417 – the Credit Access and Inclusion Act, introduced by Senator Tim Scott (R-SC) in 2021, which encourages the reporting of consumer payment history, including rent, utilities, and telecom services, to the nationwide credit reporting agencies. This is key to broadening access to fair and affordable credit for underserved consumers. The industry needs to continue to explore other avenues that can help consumers improve their financial health, such as the role that buy now, pay later information can play in increasing financial inclusion. Empowering consumers to take control Beyond legislation or the use of expanded data, many non-profit and community based organizations are championing initiatives that drive greater financial inclusion. Organizations such as Inclusiv, Jump$tart Coalition for Personal Financial Literacy, HomeFree-USA, National Urban League and the Society for Financial Education & Personal Development, among others, are helping individuals and households from underserved communities navigate the mainstream financial system and take control of their financial lives. Experian and other financial institutions are partnering with non-profit organizations with deep roots in communities, allowing them to connect with community leaders and individuals on a more personal level. Every individual enters the credit ecosystem at a different stage so it’s important that banks and financial institutions listen to the specific challenges they’re experiencing. For example, individuals may be searching for credit monitoring and alerts, budgeting tools or ways to put more money back into their wallets, such as finding cost-efficient options for auto insurance. Providing individuals and households with the financial knowledge and access to tools better positions them to become financially independent. The credit reporting industry continues to provide more resources and transparency to help improve consumers’ financial health. All individuals deserve the opportunity to establish and build their credit so they are able to elevate and maintain their financial status.
Today at Money 20/20 in Las Vegas, Experian unveiled Experian Assistant, a groundbreaking toolset that transforms analytics and modeling for financial institutions. By leveraging Generative AI (GenAI), this revolutionary solution slashes model development turning months-long processes into days—or even hours. Positioned as a game-changer, Experian Assistant offers businesses the equivalent of a seasoned expert, guiding them through complex use cases with ease and redefining how financial organizations approach data-driven insights. Revolutionizing Modeling with Generative AI Experian Assistant marks a significant leap forward in how businesses handle the modeling lifecycle. Integrated into the Experian Ascend Technology Platform™, Experian Assistant is designed to streamline data analytics processes, enhance accuracy, and promote efficiency. This debut underscores Experian’s commitment to responsible AI innovation, ensuring that organizations benefit from advanced analytics without compromising on privacy or ethical standards. “Many financial institutions are looking to invest in new generative AI use cases, often focused on banker specific support,” said Craig Focardi, Principal Analyst at Celent. “Experian Assistant focuses on developer support to accelerate the development lifecycle by having a digital model building consultant available to users.” Empowering Data Scientists and Analysts With its powerful natural language processing (NLP) capabilities, Experian Assistant is reshaping how data scientists and analysts approach complex tasks. Traditionally, navigating large datasets and building models required extensive technical expertise. But now, Experian Assistant allows users to query data, write code, and build models in plain language—democratizing access to sophisticated analytics. The tool not only boosts productivity but also fosters collaboration and accessibility. This innovation will drive financial inclusion by broadening access to data-driven insights and responsible use of data across organizations. Developed in Collaboration with Leading Financial Institutions A standout feature of Experian Assistant is its development in close partnership with the world’s largest financial institutions. This collaboration ensures that the tool is finely tuned to real-world challenges, delivering deep insights into Experian’s data assets. By optimizing analytics processes, businesses can achieve proven cost savings, enhanced data visibility, and faster product deployment. Continental Finance Company, for example, reduced data-building time by a remarkable 75% after adopting Experian Assistant. This kind of impact highlights the tool’s ability to accelerate model development while maintaining strict data privacy standards—a vital consideration for financial institutions. Advanced Compliance and Transparency In today’s highly regulated environment, businesses must not only meet compliance standards but also provide transparency into their processes. Experian Assistant is designed with these needs in mind, offering advanced features that support regulatory reporting, identity management, risk assessments, and transaction monitoring. A Competitive Edge through GenAI With more than a decade of AI expertise, Experian is leading the charge in responsible AI development. At Money 20/20, Experian Assistant stood out as a testament to this leadership. The tool is positioned to offer financial institutions a competitive edge, improving risk assessment, enhancing customer experiences, and promoting financial inclusion. As the financial services industry continues to evolve, businesses that embrace GenAI solutions like Experian Assistant will be better positioned to succeed. This groundbreaking tool is not just an enhancement—it’s a fundamental shift in how analytics and modeling are conducted, offering the speed, accuracy, and transparency that today’s market demands.
People rely on credit cards, personal loans, mortgages and auto loans, among other financial products to buy homes, fund college educations, weather temporary income disruptions and finance billions of daily transactions for goods and services. Credit is the cornerstone of the pursuit of our financial ambitions. That’s why the credit reporting industry is deeply committed to broadening access to fair and affordable financial resources for all consumers, particularly for individuals and households from underserved communities. The commitment is underscored by the continual effort to evolve the credit reporting system and incorporate new data sets to provide lenders a more comprehensive view of consumers’ ability and capacity to repay outstanding debt. Although progress has been made to extend credit to more prospective borrowers across the risk spectrum, if we want to continue to broaden the scope, we need to encourage the consistent reporting of additional predictive data sources to help lenders assess consumers’ creditworthiness. A proven track record but there’s more work to do Over the past century, the credit reporting industry transitioned from an opaque system founded on relationships to one rooted in data. Lenders lean on past payment history on similar loans (i.e., auto loans, mortgages, credit cards, etc.) as a reliable predictor of a borrower’s future loan payment performance—it’s a way for them to mitigate risk and say “yes” to more borrowers. And it works. The comprehensive reporting of past loan performance, coupled with increasingly sophisticated statistical prediction models, as well as the adoption of risk-based pricing, accelerated the extension of credit to more consumers. Yet, according to research from Experian and Oliver Wyman, millions of Americans lack access to mainstream credit because they are credit invisible, unscorable or have a subprime credit score. It’s particularly challenging for younger individuals, newly arrived immigrants and historically underserved communities, such as racial and ethnic minorities. At times it can be a catch-22; in order to get credit, you have to have credit. More predictive data is key At Experian, we’ve long understood that expanding the universe of creditworthy borrowers requires more data. In addition to some of the more conventional tradelines, such as mortgages, auto loans and credit cards, we have to explore expanded data sources that are predictive of a prospective borrower’s credit risk. For instance, more consumers are using buy now, pay later (BNPL) products, and nearly every consumer makes recurring monthly payments for rent, utilities, cell phones and even video streaming services, yet oftentimes, these data points are not consistently reported to the credit reporting agencies nor considered during lending decisions. Collectively, the industry and regulators, need to do more to encourage the consistent reporting and inclusion of expanded data onto consumers’ credit reports. In fact, based on our research, we’ve found that some of the aforementioned expanded data sources can empower lenders to assess the credit risk of a significantly larger pool of consumers. These expanded data sources have been shown to be highly accurate predictors of future loan payment behavior. And, when expanded data is combined with advanced analytics, up to 96% of the population can be scored, including an estimated 65% of credit invisibles.1 Broadening access to fair and affordable credit for more consumers means leaning into combining conventional tradelines with expanded Fair Credit Report Act-regulated data sources. The more information lenders have available to them about prospective borrowers’ past payment performance the more empowered they are to minimize risk and more confidently extend credit. Pushing for more data is the best path forward.
In an era where financial transactions occur at the click of a button, the significance of accurately verifying and authenticating consumers’ identities cannot be overstated. From online purchases to mobile banking, ensuring secure and reliable digital connections and safeguarding consumers’ information are table stakes for any business operating in the digital ecosystem. Unfortunately, some advocacy groups are calling for stricter regulatory guidelines that may impede business’ ability to effectively and efficiently protect a consumer’s financial information and identity. We’re, of course, referring to the push to classify credit header data— identifying information, such as name, current and former addresses, phone number and Social Security number, found at the top of credit reports—as a consumer report under the Fair Credit Reporting Act (FCRA). Subjecting credit header information to the FCRA will unnecessarily limit its permitted use, and effectively make it more difficult—and potentially impossible—for banks and other businesses to use the information to authenticate and verify consumers’ identities. It’s an unintended consequence that will surely compromise the security of our digital identities. Foundational to fraud prevention Credit header data plays a pivotal role in helping businesses detect suspicious activity and stay ahead of increasingly sophisticated fraud schemes. With credit header information, banks and other financial institutions cross-reference loan applications against transactions from hundreds of thousands of contributors to spot anomalies and thwart fraudsters before they inflict harm. In fact, many of the industry’s most advanced fraud prevention tools and signals rely on credit header data to verify the legitimacy of any given transaction. Keep in mind, the transactions we’re referring to are transactions of consequence. For instance, opening a new bank account, applying for a loan or transferring money. This level of activity carries inherent risk, and without proper vigilance, could result in significant financial or reputational harm to consumers and businesses. But it’s not only lenders that leverage credit header data, the use cases for credit header data are broad. Government agencies and businesses in the public sector, law enforcement, and some pharmacies use the information to issue one-time passcodes for identification purposes, find missing persons, or verify consumers’ identities prior to prescriptions being filled. Credit header data is already regulated Some of the concern surrounding credit header data centers on consumer privacy, and rightfully so. Protecting consumers’ privacy should be central to the use of sensitive information; however, credit header data is already regulated by the Gramm-Leach-Bliley Act. In fact, for more than 25 years, the Gramm-Leach-Bliley Act specifically provides that the permissible use of credit header data includes fraud prevention, while also mandating consumer privacy and data protection. Subjecting credit header data to additional FCRA regulation, which does not clearly allow for fraud prevention, could make it impractical or impossible for many businesses to use it for that purpose. Not only is additional regulation unnecessary, but it potentially creates a contradictory web of regulations that increases the compliance burden and confusion for many businesses. This ultimately thwarts the purpose of GLBA by delaying fraud prevention efforts and potentially raising costs for consumers. Credit header data is far more than information included at the top of consumers’ credit reports, it is a linchpin that powers many of the most advanced fraud prevention and identify verification tools in the market. Before any further regulation is considered, we have to acknowledge the role that credit header data plays in keeping consumers’ information safe and how any changes may impact the safety and soundness of our digital economy.
Experian continues to affirm its leadership in financial technology, earning the 7th spot on the 2024 IDC FinTech Rankings. This is the third consecutive year that the company has ranked among the top 10 providers, reinforcing its position as a key player in the FinTech space. The IDC FinTech Rankings assess the top 100 financial technology providers based on revenues generated in 2023 from financial services and FinTech sectors. In addition to this notable achievement, Experian has been awarded the 2024 IDC Real Results Award for Bank Deposit Transformation. This award highlights Experian’s innovation in driving measurable and impactful changes within the financial services industry. The recognition is particularly focused on the company’s success in helping banks transform their deposit processes through advanced fraud prevention technologies. Experian’s Ascend Fraud Sandbox: A Game-Changer A key factor behind this award is Experian’s Ascend Fraud Sandbox, a groundbreaking tool that offers financial institutions a comprehensive platform for fraud detection and prevention. The Ascend Fraud Sandbox empowers organizations to analyze data, identify new fraud patterns, and quickly build, test, and deploy models. This technology enables banks to enhance their fraud detection capabilities, leading to higher approval rates for online deposit accounts and reduced fraud-related losses. The sandbox operates with over 10 billion identity and fraud events, which include applications, login activities, and transactions. It also continuously incorporates tens of millions of new events each day. This expansive dataset allows banks to stay ahead of increasingly sophisticated fraud attempts, especially those driven by artificial intelligence (AI). Experian’s success in Bank Deposit Transformation demonstrates the company’s ability to help financial institutions improve their processes while simultaneously enhancing fraud protection. By providing advanced fraud-prevention and identity-protection technologies, Experian enables its customers to optimize their operations, reduce risks, and achieve better financial outcomes. Recognition of Experian’s Innovation This dual recognition—ranking 7th in the IDC FinTech Rankings and winning the Real Results Award—further solidifies Experian’s standing as a leader in technology. These accolades underscore its capacity to offer data, technology, and scalable solutions that allow financial institutions to make informed business decisions at the necessary speed to remain competitive in an evolving market. Now in its 21st year, the IDC FinTech Rankings evaluate technology providers based on the revenue they generate from financial institutions, including banks, insurers, and capital markets firms. With both the FinTech Rankings and the Real Results Award in hand, Experian continues to deliver innovative solutions that help financial institutions navigate the complexities of modern finance with confidence.