In May 2020, Experian launched Sure Profile and became the first company with an offering to fight synthetic identity fraud that’s integrated into the credit profile with market-leading assurance. In fact, we are so confident in our solution that we’ll share in loan losses on assured profiles if we get it wrong, a first for the industry. Recently, International Data Corporation (IDC) highlighted Sure Profile in the report, IDC, Synthetic Identity Fraud Update: Effects of COVID-19 and a Potential Cure from Experian (doc #US46690220, July 2020) stating “IDC Financial Insights believes that Experian’s Sure Profile has the potential to have market disrupting effects in the battle against SIF (synthetic identity fraud).” According to McKinsey, synthetic identity fraud is the fastest growing financial crime in the United States, accounting for 10% to 15% of lender losses each year. Synthetic identity fraud occurs when fraudsters combine real and fake information to create “Frankenstein IDs” which are then used to obtain credit or to add these identities as authorized users to existing credit accounts. Then, financial institutions report the identities to credit reporting agencies. A new record with the false information is created and subsequently, the synthetic identity can be used to generate other fake accounts. It is a significant problem that Juniper Research expects will lead to $48 billion in annual online payment fraud losses by 2023. IDC recommends that financial institutions consider Sure Profile when researching how to fight synthetic identity fraud. For institutions that use an analytical platform to detect synthetic identities, IDC suggests examining Sure Profile to see how it can supplement their models, or even replace them. “Synthetic identity fraud is a massive problem for banks, and I believe that the effects of COVID-19 will exacerbate the problem. However, at the same time, Experian launched a new offering that I believe will be a game changer for how banks attack the synthetic identity problem.” — Steven D’Alfonso, research director, IDC Financial Insights Sure Profile validates identities, detects profiles that have an increased risk for synthetic identity fraud and helps cover resulting losses for assured profiles. Leveraging the capabilities of the Experian Ascend Identity Platform™, it uses data to drive advanced analytics, including newly developed machine learning models that predict the likelihood of synthetic identity behavior. Sure Profile provides lenders a simple approach to define and detect synthetic identities early in the originations process. To learn more, check out Experian’s Sure Profile.

As financial uncertainty persists, you may find yourself turning to your credit cards to get through this challenging time. While credit cards can be a valuable financial tool when used wisely, they can also be a source of financial stress if you find yourself charging more than you’re able to pay back. Not managing your debt well can also affect your credit utilization, a term you’ve probably heard of but may not know much about. Simply put, credit utilization measures the amount of available credit you’re using on your credit cards. It’s a ratio of your outstanding balance to your overall credit limit. So, what does it mean for your credit score? Let’s unpack some myths and facts that may help you understand the importance of credit utilization, as well as ways to calculate and manage your utilization. Myths vs. Facts Myth: Credit utilization has no impact on your credit score if you pay your bills on time. Fact: In FICO’s most commonly used credit-scoring model, debt and credit utilization account for 30% of your overall score, second only to your payment history. This means the closer you are to your credit card limit, the lower your credit score might be. Aim to keep your utilization per credit card as low as possible to safeguard your score. As your utilization ratio approaches 30 percent of your limits, your scores will begin to decrease much more rapidly. People with the best scores generally have utilization of less than 10 percent, and you never want it to exceed 30%. Myth: If you max out a credit card, you should take out a new card to free up your overall credit limit and improve your utilization ratio. Fact: There are two types of credit utilization measurement: per-card and overall. Per-card utilization looks at your ratio of debt to credit limit on an individual card basis. Overall utilization takes your total utilization across all cards into account. Credit scoring models take both per-card and overall utilization into account, so having just one maxed out card could hurt your credit score. Opening a new account also introduces several aspects that may actually increase your risk. There is a new inquiry. A brand new account has been added to your credit report that you haven’t started to pay on, yet. And because scores require three to six months of activity before being included in score calculations, it’s not helping your scores. In fact, the risk associated with opening a new account may outweigh any potential benefit of reducing your utilization rate. Myth: Once you pay off a credit card, your credit score will improve. Fact: While your credit score could see improvements if you pay off a credit card, the impact may not be immediate. Your lender reports your account status about once a month, so it could be several weeks before your report is updated. Scores calculated after your report is updated will reflect the paid off amount. Depending on when you made a payment, it could take a full billing cycle before your credit report is updated and your credit score reflects those changes. Now that we’ve established the basics of credit utilization and how it can impact your score, consider how to keep it in check. Calculate your utilization The first step to getting your utilization rate in a good place is to determine your current utilization percentage. You can calculate your utilization rate by: Adding up the total balances on all credit cards Adding up the total credit limit across credit cards Dividing the total balance (from step 1) by the total credit limit (from step 2) Multiplying this number by 100 to see your credit utilization ratio as an easy-to-read percentage Manage your utilization Thirty percent utilization is not a goal or target. This is a common misconception about credit utilization. Thirty percent is a number you should strive to stay as far below as possible. It represents a mathematical limit at which your scores will begin to plummet. The lower your utilization rate, the better. Paying your balance in full is ideal, but that’s not always practical. As a general rule of thumb, aim to keep your utilization as low as possible to minimize its impact on your credit score. If you’re wondering how to lower your credit utilization ratio, consider the following strategies: Make multiple payments throughout the month. Instead of allowing the balance to accumulate, pay down your debt in increments throughout the month to ensure the amount on your billing statement doesn’t close in on your limit. Time your payments, and make sure you pay in full each month. Time your payments ahead of your statement closing date, so your most up-to-date credit utilization information is calculated into your score. It’s ideal to pay the balance due in full. If you can’t pay it in full, pay as much as you can to keep your utilization as low as possible. Keeping open credit accounts. Even if you don’t intend to use them much, closing accounts with zero balances can lower your overall credit utilization. You need to make a small purchase from time to time to show activity in the account, though. Accounts with no activity reported will be excluded from scores after a period of time. If you don’t use the card, it could still be on your credit report but not be helping your credit scores. If you’re concerned about making payments on time, connect with your lender to determine the best path forward. Check out my recent post on deferment and forbearance relief options for more information.
Experian is a proud member of the Better Identity Coalition, which is committed to working alongside policymakers to improve digital security, identity verification, privacy and convenience for everyone. Together, we’re seeking innovative ways to empower Americans to take control of their identities and conduct online business securely. On September 11, 2020, a bipartisan group of House members led by Congressman Bill Foster, introduced the “Improving Digital Identity Act of 2020” to modernize and digitize our essential government identity infrastructure. Through the Better Identity Coalition, Experian supports this bill and the steps it’s taking to help improve digital identity, security and privacy for Americans. As a result of the impact of the COVID-19 pandemic, consumers and businesses have quickly adapted to doing nearly everything digitally, but most government-issued identity credentials, such as drivers’ licenses and passports, were not created to be verified online. The “Improving Digital Identity Act” creates a comprehensive approach across federal, state and local government to address critical shortcomings in identity tools that today make it easy for fraudsters to prey on Americans. The bill creates a framework of standards that new identity solutions should follow to ensure privacy. The bill also allows for federal grants to be given to states to jumpstart modernization of the systems that provide driver’s licenses or other types of credentials to enable digital identity verification, in accordance with the NIST framework. It’s important that the bill gets passed to bring the United States up to speed on digital identity and help fix government-issued identity problems. In addition to supporting bills like the “Improving Digital Identity Act of 2020,” Experian is working hard to develop new innovations to make digital commerce safer for consumers and businesses. Our most recent innovation, Sure Profile makes us the first company with an offering to fight synthetic identity fraud that’s integrated into the credit profile with market-leading assurance. In fact, we are so confident in our solution that we’ll share in loan losses on assured profiles if we get it wrong. Experian is also proud to be the only credit bureau in the initial rollout of the Social Security Administration’s new electronic Consent Based Social Security Verification service. Our inclusion ensures our clients have the tools to more easily detect online fraud while also better recognizing legitimate consumers.
This blog is written by Rachel Duncan, HR Director, at Experian. At Experian, we encourage our employees to bring their whole selves to work and have created a culture of inclusion that helps to fuel our continued product innovation. We understand the incredible value in having a truly diverse workforce and this means removing barriers and working through challenges we all may face in and outside the workplace. That’s why we are proud to be supporting Stonewall’s ‘Trans Rights Are Human Rights’ campaign today to help reform the Gender Recognition Act (GRA) 2004. We believe that all trans people should be protected and supported with legal and policy framework that enables them to live with dignity, privacy and respect, free from fear, isolation and discrimination. The GRA was introduced in 2004 to allow trans people to apply for legal recognition of gender in which they live. However, the process in doing so is expensive, intrusive and takes a very long time. To apply for a Gender Recognition Certificate (GRC), which allows someone to legally change their gender, the individual will have to overcome many psychological challenges and it can be very emotionally taxing. It’s estimated that just 12% of trans people have a GRC, despite 92% of trans people stating in the National LGBT Survey (2018) that they would be interested in getting one. GRA reform is therefore a key step in allowing legal gender recognition to become accessible to this marginalised community. The reform requests the removal of having to disclose a psychiatric report or proof of diagnosis in order to obtain legal recognition. It moves to allow trans people the human right to decide their gender for themselves and protect all trans and non-binary people’s rights to privacy and to family life. As well as this, non-binary people should be able to legally change their gender to reflect who they are including amending their birth certificate to reflect this. The reform should also include the removal of the spousal veto. This veto allows for the spouse of a trans person the decision as to whether they can change their gender and gives control over to someone who may not have their best interests at heart. We are fully committed in ensuring LGBTQ inclusion which means, as well as evolving our own internal policies and practices, we must also contribute to external debates that campaign for equality. Our Experian Pride network has been instrumental in helping us drive change throughout the business, whilst also educating and raising awareness amongst our colleagues about the LGBTQ community. This includes supporting a collaboration with Stonewall and our HR teams to create our new ‘Transitioning at Work’ policy, along with raising money for transgender charity, Mermaids. Experian is part of a growing group of leading businesses who have joined forces to support trans equality, so we hope that together we can make a real difference to the lives of trans people across the UK. See our interview with Lewis Hayden, Service Desk Specialist and Experian Pride Network Member.
The COVID-19 pandemic reshaped Americans’ personal and financial lives. If you find yourself in a situation that could make fulfilling your credit card, loan, or mortgage payments challenging, you may be wondering what relief options are available to help navigate these changes. The good news is there are options if you need financial support during this time. However, it can be difficult to know where to start. The two primary relief avenues are deferment and forbearance. While different in practice, these terms are often used synonymously, even by those within the credit industry. While similar at first glance, there are significant differences between forbearance and deferment agreements. While both are intended to pause or reduce payments for a certain period, there are variances when it comes to how you must repay the delayed payments. It’s important to understand how these two options work when speaking with your lender, so you can choose the best path for your personal financial situation. Whichever avenue you take, remember that deferment and forbearance are both temporary measures and shouldn’t be used as permanent solutions. Pausing Payments with Deferments You may have seen the term deferment in the news more recently with mortgage relief and student loan deferral options. So, what exactly is deferment? Through this option payments are put on pause and deferred until a later date. This is a longer-term strategy that enables you to pay back your loan over time, when your financial situation puts you in a position to do so responsibly. Interest can sometimes accrue during a deferment period, depending on the type of loan and the lender you’re working with, so it is important to talk with your lender to fully understand your agreement terms. Periods of deferment vary in length – in some cases lasting as long as your financial situation requires. You should opt for deferment if your financial situation or an unexpected event, such as being let go from your job, creates an undue burden that makes it impractical or impossible to keep up with regular payments. Temporary Relief with Forbearance The other option to discuss with your lender is forbearance. Whereas deferment allows you to pay back a loan over time, forbearance is a relief strategy that typically requires the borrower to pay a lump sum and accrued interest at the end of the forbearance period. For example, if you paused payments for five months, at the end of those five months, you would pay your lender the total of paused payments and the accrued interest. If you’re seeking forbearance for federal student loans, there are two different types of forbearance: mandatory and discretionary. With mandatory forbearance, lenders are required to pause payments if a borrower meets a set of financial criteria that could prevent them from making payments on time. Eligibility for mandatory forbearance includes: enrolment in a medical or dental residency program, payments on your federal student loans being greater than 20% of your total monthly gross income, and other circumstances that could hinder your ability to make payments. Confirm whether you’re eligible with your lender. Discretionary forbearance means the lender makes the decision at their discretion to put payments in forbearance based on your unique financial situation. Forbearance is generally a shorter-term option and the avenue to take if you don’t qualify for deferment. Consider forbearance in times of true financial crises, such as an unexpected medical bill, that would temporarily inhibit you from making a monthly payment. How to Work with Your Lender on Relief Options While discussing these options with your lender, it is critical to have a full understanding of what the agreement will entail – from interest rates to your timeline for payment – to ensure you’re in the best position to fulfill the agreement with your lenders once your payments resume.
While consumers throughout the U.S. continue to manage the impacts of COVID-19, aside from health and wellbeing, one of the most salient concerns has been around the health of consumers’ finances. With many falling under some form of stay-at-home order since the onset of the pandemic, local economies have been jolted and some consumers may be feeling the financial impacts. As part of Experian’s commitment to improve the financial health of Americans and educate on debt and credit, we focused our research efforts to analyze internal and external data to show how consumer finances have changed in recent months. Through our initial review, we found that certain measures of consumer finances, on average, had improved since the onset of the pandemic. Whether due to the unprecedented government stimulus, or changes in spending, consumers saw a reduction in average debt and increased average credit scores. Though the data is rapidly changing and the true financial implications of the pandemic may be partially obscured by governmental stimulus efforts, we wanted to take a snapshot and highlight how consumers are faring in the moment. By providing these insights, we can use data for good, helping organizations, experts, and others apply learnings that may positively guide efforts in the future for the benefit of all. Our Main Findings from January 2020 to May 2020: The average VantageScore has increased by 5 points Total average consumer debt total declined by 1% Average consumer credit card balances have decreased by 14% The average credit utilization ratio has dropped 5 percentage points These findings offer an important snapshot of consumers five-months into the COVID-19 pandemic stay-at-home orders. Though initially positive, we want to keep an eye on these trends as they could change over time as government policies and stimulus efforts are amended to adjust to future conditions. To continue providing relevant insights on prevailing trends in consumer finances, we will work to maintain updated research content as the data become available. You can find links to our most recent research below, and check back at Experian.com/research for updated articles over the coming weeks. Our Most Recent Research Articles: COVID-19 Impact: Changes to Consumer Debt and Credit COVID-19: Consumers Reduce Overall Debt During Pandemic COVID-19: Credit Utilization Drops as Consumers Cut Spending
We are excited to share that Experian is proudly supporting MIT’s Solve initiative, which is focused on helping to solve global challenges. We are committing up to $100,000 for the Good Jobs & Inclusive Entrepreneurship and Learning for Girls & Women challenges. Each promotes the financial health of workers, businesses, and communities affected by COVID-19. At Experian, we feel it is our responsibility to help create a better future for the societies where we work. Today, communities, businesses, and individuals are being confronted with difficult challenges because of COVID-19. We are developing solutions to some of the financial problems that are being faced due to the pandemic. Our key focus is helping people improve their financial health and get better credit, which will help them secure essential services and achieve their goals of owning a home, starting a business, or reaching other ambitions. Some of our accomplishments include Experian Boost having already been used by more than 4 million Americans to try and boost their credit scores; our social innovation programs, focused on delivering societal benefits, which have reached 14 million people; and our employee volunteerism – with employees volunteering 54,000 hours to provide support to people through our financial education and community programs. Through Experian’s Social Innovation funding program, we develop innovative products that aim to offer societal benefits. Our dedication to social innovation will be on display as we support MIT’s Solve Challenge, which focuses on innovation in the social impact space. This competition is open to tech-based entrepreneurs across the globe and is focused on developing solutions to create lasting change. Each year, MIT receives thousands of applicants for this program. Our challenge is specifically related to solving financial health issues which have arisen for consumer groups as a result of COVID-19. We will be splitting the $100,000 prize money to accelerate up to four ideas into market, and we will also provide other assistance such as our in-house expertise and resources. This will include mentoring and potentially data or analytics to support the delivery of the most innovative solutions. Innovation is at the core of this challenge, which is a key focus at Experian. We have been frequently recognised as one of the most innovative companies in the world and feel that our mission and vision will help make this initiative successful. Our people, data, and analytics will support the delivery of the most innovative solutions that are meeting the challenges in today’s challenging landscape. We are proud to be part of MIT’s Solve Challenge and look forward to working with the winners to help create solutions for those most in need.
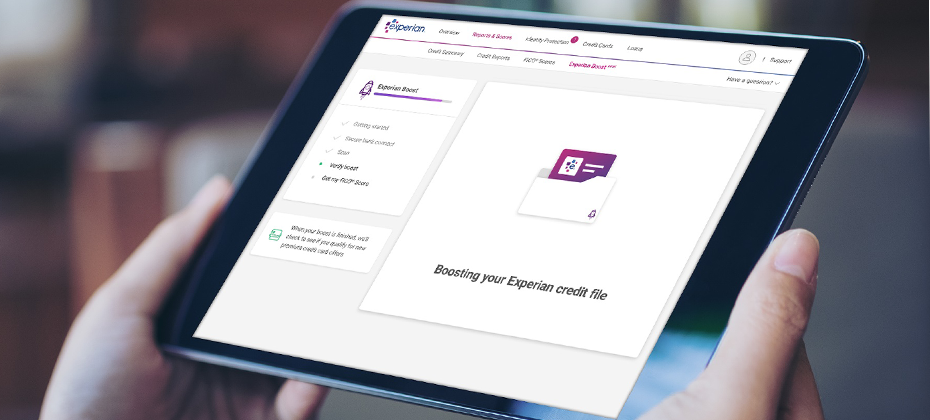
Many of us have turned to streaming services to help us cope during this time of COVID-19. Being able to escape with some good entertainment while still maintaining our social distance is invaluable right now. Television streaming has skyrocketed 85% since March; I’ve certainly contributed to that increase. Now, subscribing to that streaming service can do more than entertain, it can improve a consumer’s financial health. Starting today, Netflix® customers can possibly improve their FICO® Score by adding their positive payment history through Experian Boost. Experian Boost™† is the innovation we launched in 2019 that can help consumers improve their credit score instantly. So far, approximately four million consumers have connected their utility and telecom bills to Experian Boost, leading to more than 29 million points added to FICO® Scores nationwide. This addition makes sense. Experian Boost already allows consumers to receive credit for paying their cable bills, so paying for a video streaming service on time should also help prove creditworthiness. It’s critical that we meet consumers where they are and adapt to help them in their current position, especially during a pandemic. Anticipating and prioritizing consumer needs is our focus and drives our innovation. After all, we’re consumers too. I’m proud of how our team uses their personal experience and their roles at Experian to create opportunity for millions of people to improve their financial health, especially during these uncertain times. Our job is to help consumers, and that doesn’t stop with their credit score. That’s why we’re also launching new free features available to everyone within the CreditWorks Basic and Premium products. The free tools provide personal insights and resources that can help consumers better save money and manage their financial profile. For more information about Experian Boost go to: www.experian.com/Boost. Experian and the Experian trademarks used herein are trademarks or registered trademarks of Experian and its affiliates. The use of any other trade name, copyright, or trademark is for identification and reference purposes only and does not imply any association with the copyright or trademark holder of their product or brand. Other product and company names mentioned herein are the property of their respective owners. †Results may vary. Some may not see improved scores or approval odds. Not all lenders use Experian credit files, and not all lenders use scores impacted by Experian Boost. Credit score calculated based on FICO® Score 8 model. Your lender or insurer may use a different FICO® Score than FICO® Score 8, or another type of credit score altogether. Learn more.
We sit in a pivotal position in the societies where we work. For us at Experian, using our data and expertise to create a better tomorrow is more than an opportunity. It’s a responsibility. We are pleased to announce we have published our annual Sustainable Business Report 2020, which outlines Experian’s dedication to social and environmental issues and details our corporate responsibility performance. In the report, we also highlight Experian’s target to reach 100 million additional people globally by 2025 with social innovation products and services. Additionally, the Sustainable Business Report focuses on our ambition to become carbon neutral by 2030. By utilizing renewable energy, reducing the carbon impact of business travel, and investing in high-quality carbon offsets, we reduced our carbon footprint by 8% last year and cut the carbon intensity of our business by 14% per $1,000 of revenue compared with the previous year. Additionally, 29% of Experian’s worldwide energy was also renewable. We are excited to share a few key takeaways from this year’s Sustainable Business Report: Experian employees volunteered 54,500 hours in and outside of work time to support their communities. This included over 3,500 hours in March 2020 to support communities as the COVID-19 crisis took hold. In Brazil, we have supported the introduction of new legislation enabling millions of consumers to benefit from the use of ‘positive’ data about the credit and other bills they pay on time. Experian Boost helped over 1.5 million Americans improve their credit scores, collectively boosting their FICO® scores by more than 17 million points. Prove ID-Link helped 7.5 million people in India prove their identity. As a result, more people are able to open a bank account and access credit for the first time. Learn more by viewing or downloading our full Sustainable Business Report here.
“What does a credit bureau do?” is one of the most common questions I’ve answered throughout the years – both at conferences and cookouts. Admittedly, it can be difficult understanding the different roles of credit bureaus, credit score companies, and lenders. Amid COVID-19, it’s important for us to define our purpose and help guide you toward the right resources for financial help. As the consumers’ bureau, Experian is committed to examining financial questions and helping consumers, businesses, and lenders navigate this transitional fiscal landscape. It’s important for you to know your financial options and how to separate fact from fiction, especially during times of crisis. Here are answers to some of the most common questions about credit. Do credit bureaus make lending decisions? This is one of the rare instances in credit reporting for which there is a simple answer. No, credit bureaus do not make lending decisions. Lenders – such as banks, mortgage companies, credit unions, and credit card issuers – help consumers borrow money and they make the lending decisions. The credit bureaus are responsible for working closely with lenders to provide information that helps them make informed and responsible lending decisions. At Experian, we equip lenders with accurate and complete data about consumers’ and small businesses’ credit activity and payment history, which enables lenders to develop a full picture of a borrower’s financial health. During COVID-19, it is important for there to be open lines of communication between consumers and lenders about upcoming payments and payment plans. Some lenders are offering deferments and other workable accommodations to ensure consumers do not fall behind on their payments. It is important for consumers to contact their lenders to understand what options are available to them. Do credit bureaus control my credit score (and whether it goes up or down)? Credit bureaus, like Experian, do not determine your credit score. Credit scores are calculated based on third-party credit-scoring models, like those developed by FICO or VantageScore Solutions. These models use information from your credit reports, including credit activity sourced from credit bureaus, to calculate a credit score. The scoring models are proprietary to the companies that develop them. In the most fundamental terms, the credit bureaus are responsible for compiling the credit reports. The scoring companies create algorithms that calculate the score. Credit scores reflect the information in your credit report at the moment the credit score is calculated. The scores will change to reflect changes in your credit report. You control how you use credit, so you play an important role in determining whether your scores trend upward or slip downward. If you consistently make good credit decisions, your scores will trend upward over time. Reviewing your credit report helps you manage your credit and gives you a full picture of what lenders see. Monitoring your credit report is as important as reviewing bills and bank statements, as your credit is an integral part of your overall financial health. Additionally, with an increase in phishing and cyberscams as a result of COVID-19, it’s especially important to stay informed about your credit report, so that you can dispute anything you believe may be inaccurate and ensure that there is no evidence of fraud that could impact your score. Are lending decisions based solely on my credit score? No, credit scores are just one factor in lenders’ decision-making process. Lenders consider additional information when making a decision, such as employment status, income and information about a consumer’s assets and liabilities. In the wake of COVID-19, lenders may start to tighten their credit standards – meaning consumers may need a higher score to receive a loan. Because of this, it is important to be proactive and take action to mitigate any potential negative impact on your credit score. If you’re worried you may miss a payment, contact your lender to discuss your options. Through April 2021, Experian has partnered with our peer credit bureaus to offer a weekly free credit score at https://www.annualcreditreport.com/. This additional measure will allow consumers to access their credit reports frequently and talk to their lenders with the most updated information possible. How are credit bureaus working with the government during COVID-19? At Experian, we fully supported the signing of the Coronavirus Aid, Relief, and Economic Security Act (CARES Act), which provides relief to Americans through expanded unemployment coverage and by providing grants and loans to small businesses. The CARES Act also provided important guidance to lenders about how to work with consumers affected by COVID-19. Experian is working with lenders to ensure appropriate accommodations are made to protect consumers. Additionally, the credit reporting industry has developed reporting standards for lenders to use during emergency periods, such as COVID-19. These reporting standards allow lenders flexibility when reporting accommodations made to consumers who are experiencing hardships due to the pandemic. For additional questions regarding COVID-19 debt and credit relief options, view Experian’s full list of financial and non-financial institutions’ websites where you can find information on relief measures: COVID-19 (Coronavirus) Credit Card and Debt Relief.
We are delighted to have completed the acquisition of a 60% stake in Arvato Financial Solutions Risk Management Division (AFS RM), expanding our presence in Germany, Austria, and Switzerland (DACH) and bringing Germany’s second largest credit bureau into Experian. It is an incredibly exciting moment for us both and marks a significant step forward in Experian EMEA’s growth ambitions. Together, we form a powerful new partnership in Europe’s economic powerhouse. With AFS RM’s local expertise and sector knowledge of industries like e-commerce, telecoms and insurance, and our global experience and innovation in data, analytics, software, and technology platforms, we will redefine what’s possible for our customers. AFS RM brings market presence with high-quality risk, fraud and identity management products and solutions tailored for key industries. We bring scale, expertise, and innovative products like Experian One and Ascend Analytics on Demand. Together, we will offer the best new technologies into these markets, delivering broad coverage and innovation that enables existing and new customers to make better, faster decisions, ultimately delivering greater access to finance for people across the region. Our new partnership will be branded Experian, which is just one of the ways we’re welcoming AFS RM to the Experian family. I’m delighted it will be led by Kai Kalchthaler as CEO, Experian DACH, who will ensure we help businesses find and fulfill their potential, so they can go further with us. Watch how we’re redefining possible, today, tomorrow, together here.
Juniper Research released their Online Payment Fraud 2020-2024 report in May highlighting key trends in digital fraud, it’s implications on businesses and consumers as well as a competitive analysis for advanced solutions available to secure digital payments. Experian is proud to have contributed to the research and its CrossCore solution considered on their Fraud Detection & Prevention Leaderboard. Key takeaways: We’re in the middle of a payment revolution with mobile payments on the rise. Nearly half the world will be using digital wallets by 2024, with transaction values to increase by almost 60% to over $9 trillion in 2024. Omnichannel expectations are creating new challenges for online payments as new technologies for creating convenience are being exploited by cybercriminals, but it’s preventable. Juniper Research forecasts a $25.5 billion eCommerce transaction fraud loss in 2019, a 17% increase in 2018. By 2024, this will double to almost $50.5 billion. The Fraud Detection & Prevention Leaderboard is an assessment based on a combination of quantitative and qualitative measures but not considered a ranking or exhaustive list of solutions on the market. Experian’s flagship solution, CrossCore, just released its latest advanced features and offers unique functionality that lives up to its layered approach for mitigating fraud and authenticating customers. CrossCore is an integrated digital identity and fraud risk platform that combines rich data assets from Experian with identity insights and capabilities from its curated partner ecosystem. Through sophisticated orchestration, it applies advanced analytics to give businesses confidence in every transaction. CrossCore combines risk-based authentication, identity proofing, and fraud detection into a single cloud platform to make real-time risk decisions throughout the customer lifecycle. The platform is designed to help clients differentiate between their good and bad customers, without disrupting good customers, or increasing customer friction in their attempts to stop fraud. Key profile features: Our partner network, some of which we don’t publicly disclose, cover a variety of categories including, behavioural biometrics (Biocatch), traditional biometrics (Daon), document verification (Mitek, Acuant, Onfido), call centre risk assessments (TrustID, NextCaller), email verification (Emailage), Alternative Data (Ekata, Global Data Consortium, HelloSoda, Pipl), Mobile Phone Verification (Boku/Danal) and Chargeback Management (Chargebacks911). Customers include banks, eCommerce merchants and retail companies, telecommunications providers, travel providers, health providers, insurance companies, and public sector organizations. Advanced Decisioning: CrossCore is designed to leverage the complete raw output in our partner network to perform advanced analytics via Experian’s native machine learning infrastructure. This approach includes a hybrid of Unsupervised models (to generate features), Supervised generic or custom models per use case, and a business rules infrastructure. This provides high levels of accuracy to the client, leading to significantly reduced friction and operational costs. Find out how Experian’s capabilities compare and hear from our experts on how to balance security with convenient customer experiences.
Related Posts
Experian’s groundbreaking generative AI-powered tool, Experian Assistant, has earned the prestigious 2025 BIG Innovation Award in the Products for Financial Services category. This recognition underscores Experian’s commitment to pushing the boundaries of innovation by helping businesses achieve success and enhancing consumer experiences. The BIG Innovation Awards, celebrated since 2011, honor organizations and solutions that redefine excellence through creativity and measurable impact. Experian Assistant was recognized for transforming how financial institutions approach data and analytics, enabling faster, smarter decision-making that enhances customer experiences and operational efficiency. Redefining Financial Services Integrated with the Experian Ascend Platform™, Experian Assistant functions as a 24/7 data expert, enabling financial institutions to optimize their credit and fraud models with ease. Using natural language processing (NLP), the virtual assistant guides users providing insights, recommendations and coding assistance. The impact is transformative: Experian Assistant cuts model-development timelines from months to just days— and even hours in some cases. By helping users analyze credit and fraud data, adjust model attributes and streamline workflows, it empowers organizations to innovate faster and make data-driven decisions with confidence. Powered by agentic AI technology, Experian Assistant reimagines how data scientists and analysts approach their work. It accelerates insights, fosters collaboration and empowers businesses to deliver exceptional customer experiences while reducing the time and resources needed to bring new initiatives to market. Driving Results Across Industries While tailored for financial services, Experian Assistant’s capabilities extend across industries. Businesses can leverage its tools for data exploration, model deployment, performance monitoring and faster time-to-market for new offerings. With Experian Assistant, users gain a powerful edge in scoring more consumers, optimizing processes and enhancing overall customer satisfaction. Recognized Excellence The 2025 BIG Innovation Awards spotlight trailblazers evaluated on creativity, impact and results by seasoned business leaders. This accolade solidifies Experian Assistant’s position as a game-changing solution in financial services and beyond.
We are thrilled that for the sixth consecutive year, Experian has earned a score of 100 on the Human Rights Campaign Foundation’s (HRCF) 2025 Corporate Equality Index (CEI). This recognition underscores our commitment to LGBTQ+ workplace equality. We are honored to join the ranks of 765 U.S. businesses that have been awarded the HRCF’s Equality 100 Award, celebrating our leadership in fostering an inclusive workplace. Experian’s dedication to supporting the LGBTQ+ community is reflected in several key initiatives: Name Change Process: We have a process for transgender and non-binary consumers to update their names on credit reports, ensuring their identities are accurately represented. LGBTQ+ Allyship 101 Training: This new training program is available to all Experian employees, promoting allyship and understanding within our workforce. Pride ERG Parenting Committee: Launched to support parents, grandparents and guardians of LGBTQ+ individuals, this committee provides valuable resources and community. Transgender Resource Guide: This guide supports employees who are transitioning at work, offering education and resources for colleagues and managers. Partnerships: We collaborate with organizations such as Out & Equal, GenderCool, The Trevor Project and Born This Way Foundation’s Channel Kindness to provide financial health, mental health and other resources to empower both our internal and external communities. At Experian, we are proud to be part of this movement towards greater equality and inclusion. We remain dedicated to fostering a workplace where every employee feels respected, valued and empowered to bring their authentic selves to work. Learn more about how we drive social impact in English, Portuguese and Spanish.
Achieving Top Workplace recognition for 12 consecutive years is no small feat, yet Experian North America has done just that. Named a Top Workplace by the Orange County Register once again, this milestone reflects not just policies or benefits but what truly makes Experian exceptional: our people. As Hiq Lee, Chief People Officer at Experian North America, notes, this honor is a testament to the remarkable contributions of our team. Experian’s employees shape an environment where innovation, inclusivity, and purpose thrive. More Than Work What sets Experian apart is our engagement with the world and community. Through initiatives like the Experian Volunteer Leadership Network and partnerships with organizations such as the Octane Foundation for Innovation and the Hispanic Chamber of Commerce of Orange County Education Foundation, our impact extends beyond the workplace. In 2024, we earned additional recognitions, including being named one of the World’s Best Workplaces™ by Fortune and Great Place to Work®. We were also recognized as one of the Best Workplaces for Parents, Millennials, and in Technology. The Secret to Success Our success lies in focusing on people. Experian is a place where careers are built, ideas are encouraged, and employees feel valued. Initiatives such as, Employee Resource Groups foster belonging, Mental Health First Aiders provide support, and technology hackathons inspire creativity. Innovation at the Core Innovation continues to drive our success. By leveraging technologies like artificial intelligence and machine learning, we are redefining decision-making and fraud prevention. This commitment to innovation empowers businesses and consumers worldwide, aligning with our mission to promote financial inclusivity. Looking Ahead For Experian, being a Top Workplace for more than a decade isn’t a finish line—it’s a springboard. With an ongoing commitment to our employees and communities, we continue to evolve, creating better experiences for our team, clients, and the world.
The rise of Generative AI (GenAI) is fueling a new wave of sophisticated fraud, transforming the financial services landscape. Experian’s 2024 Global Identity & Fraud Report highlights the challenges businesses face, and the strategies needed to protect consumers while maintaining seamless digital experiences. Based on insights from more than 1,000 business and fraud leaders, and 4,000 consumers worldwide, the report identifies three key forces shaping fraud prevention: GenAI-Powered Fraud: Fraudsters use AI to craft highly personalized attacks, exploiting vulnerabilities across the customer journey. Evolving Regulations: Stricter government requirements demand rapid adaptation of fraud prevention strategies. Customer Expectations: Consumers prioritize secure, efficient services. Many abandon brands after poor account-opening or transactional experiences. A Multi-Layered Defense The report emphasizes the need for a multi-layered approach to combat fraud effectively. Businesses are increasing investments in AI, machine learning, and data-sharing networks to detect and prevent fraud in real-time. “Fraud operates across borders and targets various points in the customer journey,” said Greg Wright, Experian’s Executive Vice President of Identity and Fraud. “Businesses must leverage advanced analytics and alternative data to stay ahead of these evolving threats.” Balancing Security and Experience Consumers value security, but demand convenience. Striking the right balance is critical, as many switch providers after experiencing delays or cumbersome processes. Businesses can succeed by: Using Advanced Analytics: Leveraging AI-driven insights to prevent fraud while maintaining smooth customer experiences. Orchestrating Fraud Prevention: Integrating tools to provide a 360-degree view of customers, ensuring fraud detection is seamless and comprehensive. The Path Forward The rise of GenAI fraud underscores the need for global collaboration and innovation. By adopting advanced technologies and prioritizing customer-centric solutions, businesses can protect consumers while fostering trust. Experian’s 2024 report offers actionable insights for navigating these challenges. Download the full report to learn how to outpace fraudsters while delivering secure, seamless experiences.
The advertising ecosystem has seen significant transformation over the past few years, with increased privacy regulation, changes in available signals, and the rise of channels like connected TV and retail media. These changes are impacting the way that consumers interact with brands and how brands understand and continue to deliver relevant messages to consumers with precision. Experian has been helping marketers navigate these changes, and as a result, our marketing data and identity solutions underpin much of today’s advertising industry. We’re committed to empowering marketers and agencies to understand and reach their target audiences, across all channels. Today, we are excited to announce our acquisition of Audigent—a leading data and activation platform in the advertising industry. With Audigent’s combination of first-party publisher data, inventory and deep supply-side distribution relationships, publishers, big and small, can empower marketers to better understand their customers, expand the reach of their target audiences and activate those audiences across the most impactful inventory. I am excited to bring together Audigent’s supply-side network as a natural extension to our existing demand-side capabilities. Audigent’s ability to combine inventory with targeted audiences using first-party, third-party and contextual signals provides the best of all worlds, allowing marketers to deliver campaigns centered on consumer choices, preferences, and behaviors. The addition of Audigent further strengthens our strategy to be the premier independent provider of marketing data and identity, ultimately creating more relevant experiences for consumers. To learn more about Experian and Audigent, visit https://www.experian.com/marketing/ and https://audigent.com/.
Modernizing the conversation around credit and financial literacy is a key commitment for Experian, especially for young adults. That’s why we partner with organizations like the Singleton Foundation to produce “Your World on Money,” to meet young people where they are, with engaging, easy-to-understand video shorts about credit, budgeting, and saving and more. We’re thrilled this commitment and creativity has earned both Gold and Bronze Anthem Awards, which recognize excellence in social good, celebrate the impactful work of organizations and initiatives that are driving positive change. Financial literacy is often not taught in schools, and the language around credit and personal finance can be intimidating. By normalizing these conversations, we hope to inspire confidence and action, helping young adults make informed financial decisions as they navigate life’s milestones. Our United for Financial Health partnership with the Singleton Foundation continues with our new series, the Finance Couch, where college students join our experts on a coach in the middle of a Los Angeles campus to answer their money questions. And our Anthem Award-winning series, HeartBroke, helps couples whose relationships are tested with financial issues to determine if they can work through it or end up HeartBroke(n).
Great Place to Work and Fortune have named Experian as one of the 25 World’s Best Workplaces™ 2024. This recognition highlights more than an award—it shows a commitment to our strong People First culture. Experian Chief People Officer Jacky Simmonds shares insights on how our people across the globe cultivate this culture, staying ahead of the curve through a unique blend of inclusivity, empathy, and a shared purpose. What does it mean to you, and to Experian, to be named among Fortune’s World’s Best Places to Work? At Experian, we have long aspired to be one of the best companies in the world to work for, and over the past few years, we have made this a priority. Our journey has been marked by a commitment to putting our people first and fostering the collaborative and inclusive culture that sets us apart. This recognition reflects the common values that we share across our many countries and cultures and the dedication of our colleagues across our business. We spend so much of our time at work, so I think it’s important that every interaction – from the interview process to joining and every daily interaction – is a positive one where people are welcoming, supportive and generally just really nice people to work with. Reaching this milestone gives all of us at Experian some recognition, but also it is inspiring as we continue to strive to attract top talent who share our values, share our purpose and make every day an enjoyable one. How does Experian create an environment where employees feel empowered to innovate and contribute ideas that drive real impact? To fulfill our mission of bringing Financial Power to All™, we need as many voices, experiences and backgrounds as possible, so we can represent our clients’ differing needs. This culture of inclusion drives our innovations. We have employee-led initiatives, such as internal Hackathons that bring together these diverse perspectives to develop products and services like Experian Boost, Experian Go, Experian Smart Money Digital Checking Account, Experian Support Hub, and Transforme-se so we can serve the communities in which we live and work. How has Experian adapted to changing employee expectations since the pandemic, and what steps has the company taken to support employee well-being and work-life balance? We know that our people really value the ability to have flexible work model, so they can work to fulfill their role in a way that works for them. For some this is fully remote, for others it is hybrid so a balance of remote and in office, and for others in office, where their role requires it fully. We know from the feedback that we get that our people appreciate that we trust them and they have flexibility to deal with varying commitments that we all have outside of work. We also know that since the pandemic there has been an increased focused on wellbeing. Sponsored by our Chief Financial Officer, we embarked upon an initiative to invest in how we support people who may need additional support. We are very proud of our Mental Health First Aiders programme, which has trained around 400 colleagues across the world representing 23 countries and 28 languages and helping their teammates access resources. These volunteers receive consistent, ongoing and updated training. What specific initiatives or programmes at Experian do you believe set the company apart in terms of supporting professional growth and career development? We have invested in a number of things that we believe really make the difference. The first is developing great leaders at every level. Today’s leaders have many more challenges, many different age groups, a balance of remote and in person working, together with teams based in many different locations. Great leaders build great teams, so we think it’s important to invest in their development. That’s we built a leadership development portal – The Leadership Exchange – that has a wide range of resources to support them, including development programmes tailored to their needs. We also want to ensure that everyone at every level can develop their skills and progress their careers. So we launched our annual Global Careers Week, Experian University, and built a world-class digital curriculum so everyone can access the form of development they need based on their role or aspirations. There really is something for everyone. This way, we help our teams stay ahead of trends and ensure our business is equipped with the skills needed for the future. Looking forward, what are key goals or priorities for further enhancing Experian’s culture and employee experience? We’re truly proud of this amazing recognition, but we always strive to get better and acknowledge there’s always more to be done. We see an opportunity to make things easier in the way we leverage advanced technologies like AI to further enhance employee experience. For example, more personalised learning pathways, improved tools for productivity and collaboration. We make sure we don’t lose the human touch, but we also want to make the most of these innovations so we stay relevant with our largely tech populations. Being named one of the world’s best workplaces reflects Experian’s unwavering commitment to be recognized for having a great culture where people can do their best work with people they enjoy working with. Learn more about what makes Experian a World’s Best Workplace in the People section of our Annual Report and the Experian Power of YOU Report 2024: Driving social impact and diversity, equity and inclusion, available in English, Portuguese and Spanish.
While the credit reporting industry is designed to help lenders and creditors minimize risk and assess consumers’ ability and willingness to repay outstanding debt, let’s be clear: the consumer is our main priority. Every lending decision and action is made with the consumers’ best interest in mind. Because consumers rely on credit and other loan products to purchase homes and cars, pay for college, afford goods and services, and even bridge the gap during emergencies, the credit reporting industry has been at the forefront of broadening access to fair and affordable financial resources. Risk-based pricing has made it possible for more consumers to access credit, particularly those with limited-to-no credit history or subprime credit profiles. Previously, lenders may have opted not to extend credit to consumers considered higher risk; but more and more, lenders are empowered to tailor borrowing terms based on a consumer’s credit history. In addition, because lenders don’t have to absorb unforeseen risk, lower borrowing costs can be maintained for all consumers. Experian has long advocated for expanded data sources, such as rent and utilities payments, to be incorporated onto consumer credit reports and considered in lending decisions. In 2019, we launched a product that empowers consumers to add positive payment history for utilities, telecoms and video streaming services—and eventually residential rent—directly into their Experian credit report. Our efforts coincide with legislation, such as S.2417 – the Credit Access and Inclusion Act, introduced by Senator Tim Scott (R-SC) in 2021, which encourages the reporting of consumer payment history, including rent, utilities, and telecom services, to the nationwide credit reporting agencies. This is key to broadening access to fair and affordable credit for underserved consumers. The industry needs to continue to explore other avenues that can help consumers improve their financial health, such as the role that buy now, pay later information can play in increasing financial inclusion. Empowering consumers to take control Beyond legislation or the use of expanded data, many non-profit and community based organizations are championing initiatives that drive greater financial inclusion. Organizations such as Inclusiv, Jump$tart Coalition for Personal Financial Literacy, HomeFree-USA, National Urban League and the Society for Financial Education & Personal Development, among others, are helping individuals and households from underserved communities navigate the mainstream financial system and take control of their financial lives. Experian and other financial institutions are partnering with non-profit organizations with deep roots in communities, allowing them to connect with community leaders and individuals on a more personal level. Every individual enters the credit ecosystem at a different stage so it’s important that banks and financial institutions listen to the specific challenges they’re experiencing. For example, individuals may be searching for credit monitoring and alerts, budgeting tools or ways to put more money back into their wallets, such as finding cost-efficient options for auto insurance. Providing individuals and households with the financial knowledge and access to tools better positions them to become financially independent. The credit reporting industry continues to provide more resources and transparency to help improve consumers’ financial health. All individuals deserve the opportunity to establish and build their credit so they are able to elevate and maintain their financial status.
Today at Money 20/20 in Las Vegas, Experian unveiled Experian Assistant, a groundbreaking toolset that transforms analytics and modeling for financial institutions. By leveraging Generative AI (GenAI), this revolutionary solution slashes model development turning months-long processes into days—or even hours. Positioned as a game-changer, Experian Assistant offers businesses the equivalent of a seasoned expert, guiding them through complex use cases with ease and redefining how financial organizations approach data-driven insights. Revolutionizing Modeling with Generative AI Experian Assistant marks a significant leap forward in how businesses handle the modeling lifecycle. Integrated into the Experian Ascend Technology Platform™, Experian Assistant is designed to streamline data analytics processes, enhance accuracy, and promote efficiency. This debut underscores Experian’s commitment to responsible AI innovation, ensuring that organizations benefit from advanced analytics without compromising on privacy or ethical standards. “Many financial institutions are looking to invest in new generative AI use cases, often focused on banker specific support,” said Craig Focardi, Principal Analyst at Celent. “Experian Assistant focuses on developer support to accelerate the development lifecycle by having a digital model building consultant available to users.” Empowering Data Scientists and Analysts With its powerful natural language processing (NLP) capabilities, Experian Assistant is reshaping how data scientists and analysts approach complex tasks. Traditionally, navigating large datasets and building models required extensive technical expertise. But now, Experian Assistant allows users to query data, write code, and build models in plain language—democratizing access to sophisticated analytics. The tool not only boosts productivity but also fosters collaboration and accessibility. This innovation will drive financial inclusion by broadening access to data-driven insights and responsible use of data across organizations. Developed in Collaboration with Leading Financial Institutions A standout feature of Experian Assistant is its development in close partnership with the world’s largest financial institutions. This collaboration ensures that the tool is finely tuned to real-world challenges, delivering deep insights into Experian’s data assets. By optimizing analytics processes, businesses can achieve proven cost savings, enhanced data visibility, and faster product deployment. Continental Finance Company, for example, reduced data-building time by a remarkable 75% after adopting Experian Assistant. This kind of impact highlights the tool’s ability to accelerate model development while maintaining strict data privacy standards—a vital consideration for financial institutions. Advanced Compliance and Transparency In today’s highly regulated environment, businesses must not only meet compliance standards but also provide transparency into their processes. Experian Assistant is designed with these needs in mind, offering advanced features that support regulatory reporting, identity management, risk assessments, and transaction monitoring. A Competitive Edge through GenAI With more than a decade of AI expertise, Experian is leading the charge in responsible AI development. At Money 20/20, Experian Assistant stood out as a testament to this leadership. The tool is positioned to offer financial institutions a competitive edge, improving risk assessment, enhancing customer experiences, and promoting financial inclusion. As the financial services industry continues to evolve, businesses that embrace GenAI solutions like Experian Assistant will be better positioned to succeed. This groundbreaking tool is not just an enhancement—it’s a fundamental shift in how analytics and modeling are conducted, offering the speed, accuracy, and transparency that today’s market demands.
People rely on credit cards, personal loans, mortgages and auto loans, among other financial products to buy homes, fund college educations, weather temporary income disruptions and finance billions of daily transactions for goods and services. Credit is the cornerstone of the pursuit of our financial ambitions. That’s why the credit reporting industry is deeply committed to broadening access to fair and affordable financial resources for all consumers, particularly for individuals and households from underserved communities. The commitment is underscored by the continual effort to evolve the credit reporting system and incorporate new data sets to provide lenders a more comprehensive view of consumers’ ability and capacity to repay outstanding debt. Although progress has been made to extend credit to more prospective borrowers across the risk spectrum, if we want to continue to broaden the scope, we need to encourage the consistent reporting of additional predictive data sources to help lenders assess consumers’ creditworthiness. A proven track record but there’s more work to do Over the past century, the credit reporting industry transitioned from an opaque system founded on relationships to one rooted in data. Lenders lean on past payment history on similar loans (i.e., auto loans, mortgages, credit cards, etc.) as a reliable predictor of a borrower’s future loan payment performance—it’s a way for them to mitigate risk and say “yes” to more borrowers. And it works. The comprehensive reporting of past loan performance, coupled with increasingly sophisticated statistical prediction models, as well as the adoption of risk-based pricing, accelerated the extension of credit to more consumers. Yet, according to research from Experian and Oliver Wyman, millions of Americans lack access to mainstream credit because they are credit invisible, unscorable or have a subprime credit score. It’s particularly challenging for younger individuals, newly arrived immigrants and historically underserved communities, such as racial and ethnic minorities. At times it can be a catch-22; in order to get credit, you have to have credit. More predictive data is key At Experian, we’ve long understood that expanding the universe of creditworthy borrowers requires more data. In addition to some of the more conventional tradelines, such as mortgages, auto loans and credit cards, we have to explore expanded data sources that are predictive of a prospective borrower’s credit risk. For instance, more consumers are using buy now, pay later (BNPL) products, and nearly every consumer makes recurring monthly payments for rent, utilities, cell phones and even video streaming services, yet oftentimes, these data points are not consistently reported to the credit reporting agencies nor considered during lending decisions. Collectively, the industry and regulators, need to do more to encourage the consistent reporting and inclusion of expanded data onto consumers’ credit reports. In fact, based on our research, we’ve found that some of the aforementioned expanded data sources can empower lenders to assess the credit risk of a significantly larger pool of consumers. These expanded data sources have been shown to be highly accurate predictors of future loan payment behavior. And, when expanded data is combined with advanced analytics, up to 96% of the population can be scored, including an estimated 65% of credit invisibles.1 Broadening access to fair and affordable credit for more consumers means leaning into combining conventional tradelines with expanded Fair Credit Report Act-regulated data sources. The more information lenders have available to them about prospective borrowers’ past payment performance the more empowered they are to minimize risk and more confidently extend credit. Pushing for more data is the best path forward.
In an era where financial transactions occur at the click of a button, the significance of accurately verifying and authenticating consumers’ identities cannot be overstated. From online purchases to mobile banking, ensuring secure and reliable digital connections and safeguarding consumers’ information are table stakes for any business operating in the digital ecosystem. Unfortunately, some advocacy groups are calling for stricter regulatory guidelines that may impede business’ ability to effectively and efficiently protect a consumer’s financial information and identity. We’re, of course, referring to the push to classify credit header data— identifying information, such as name, current and former addresses, phone number and Social Security number, found at the top of credit reports—as a consumer report under the Fair Credit Reporting Act (FCRA). Subjecting credit header information to the FCRA will unnecessarily limit its permitted use, and effectively make it more difficult—and potentially impossible—for banks and other businesses to use the information to authenticate and verify consumers’ identities. It’s an unintended consequence that will surely compromise the security of our digital identities. Foundational to fraud prevention Credit header data plays a pivotal role in helping businesses detect suspicious activity and stay ahead of increasingly sophisticated fraud schemes. With credit header information, banks and other financial institutions cross-reference loan applications against transactions from hundreds of thousands of contributors to spot anomalies and thwart fraudsters before they inflict harm. In fact, many of the industry’s most advanced fraud prevention tools and signals rely on credit header data to verify the legitimacy of any given transaction. Keep in mind, the transactions we’re referring to are transactions of consequence. For instance, opening a new bank account, applying for a loan or transferring money. This level of activity carries inherent risk, and without proper vigilance, could result in significant financial or reputational harm to consumers and businesses. But it’s not only lenders that leverage credit header data, the use cases for credit header data are broad. Government agencies and businesses in the public sector, law enforcement, and some pharmacies use the information to issue one-time passcodes for identification purposes, find missing persons, or verify consumers’ identities prior to prescriptions being filled. Credit header data is already regulated Some of the concern surrounding credit header data centers on consumer privacy, and rightfully so. Protecting consumers’ privacy should be central to the use of sensitive information; however, credit header data is already regulated by the Gramm-Leach-Bliley Act. In fact, for more than 25 years, the Gramm-Leach-Bliley Act specifically provides that the permissible use of credit header data includes fraud prevention, while also mandating consumer privacy and data protection. Subjecting credit header data to additional FCRA regulation, which does not clearly allow for fraud prevention, could make it impractical or impossible for many businesses to use it for that purpose. Not only is additional regulation unnecessary, but it potentially creates a contradictory web of regulations that increases the compliance burden and confusion for many businesses. This ultimately thwarts the purpose of GLBA by delaying fraud prevention efforts and potentially raising costs for consumers. Credit header data is far more than information included at the top of consumers’ credit reports, it is a linchpin that powers many of the most advanced fraud prevention and identify verification tools in the market. Before any further regulation is considered, we have to acknowledge the role that credit header data plays in keeping consumers’ information safe and how any changes may impact the safety and soundness of our digital economy.
Experian continues to affirm its leadership in financial technology, earning the 7th spot on the 2024 IDC FinTech Rankings. This is the third consecutive year that the company has ranked among the top 10 providers, reinforcing its position as a key player in the FinTech space. The IDC FinTech Rankings assess the top 100 financial technology providers based on revenues generated in 2023 from financial services and FinTech sectors. In addition to this notable achievement, Experian has been awarded the 2024 IDC Real Results Award for Bank Deposit Transformation. This award highlights Experian’s innovation in driving measurable and impactful changes within the financial services industry. The recognition is particularly focused on the company’s success in helping banks transform their deposit processes through advanced fraud prevention technologies. Experian’s Ascend Fraud Sandbox: A Game-Changer A key factor behind this award is Experian’s Ascend Fraud Sandbox, a groundbreaking tool that offers financial institutions a comprehensive platform for fraud detection and prevention. The Ascend Fraud Sandbox empowers organizations to analyze data, identify new fraud patterns, and quickly build, test, and deploy models. This technology enables banks to enhance their fraud detection capabilities, leading to higher approval rates for online deposit accounts and reduced fraud-related losses. The sandbox operates with over 10 billion identity and fraud events, which include applications, login activities, and transactions. It also continuously incorporates tens of millions of new events each day. This expansive dataset allows banks to stay ahead of increasingly sophisticated fraud attempts, especially those driven by artificial intelligence (AI). Experian’s success in Bank Deposit Transformation demonstrates the company’s ability to help financial institutions improve their processes while simultaneously enhancing fraud protection. By providing advanced fraud-prevention and identity-protection technologies, Experian enables its customers to optimize their operations, reduce risks, and achieve better financial outcomes. Recognition of Experian’s Innovation This dual recognition—ranking 7th in the IDC FinTech Rankings and winning the Real Results Award—further solidifies Experian’s standing as a leader in technology. These accolades underscore its capacity to offer data, technology, and scalable solutions that allow financial institutions to make informed business decisions at the necessary speed to remain competitive in an evolving market. Now in its 21st year, the IDC FinTech Rankings evaluate technology providers based on the revenue they generate from financial institutions, including banks, insurers, and capital markets firms. With both the FinTech Rankings and the Real Results Award in hand, Experian continues to deliver innovative solutions that help financial institutions navigate the complexities of modern finance with confidence.