Experian, the global information services company, has agreed to join FDATA in support of its Open Banking initiatives around the world. The commitment includes membership in the UK, US, and EMEA. It reflects Experian’s strategy for rolling out Open Banking services across its global footprint that includes South America, South East Asia including Australia and South Africa. Access to Open Banking will complement the organisation’s network of credit bureaux, identity verification, and automated decision services that it already provides to consumers and businesses. Open Banking enables Experian to provide additional insight into consumers’ and businesses’ financial wellbeing. Lisa Fretwell, Managing Director of Data Services at Experian, said: “Joining FDATA helps us to exchange knowledge, thought leadership, and drive innovation at a time when we are increasing our strategic commitment and investment plans for Open Banking. This will also include the UK’s Open Finance initiative.” Experian helps consumers and businesses to engage with and understand their finance through combining its bureau data with insights generated from Open Banking. Its consumer services business engages with more than 7 million consumers in the UK and more than 30 million in the U.S, empowering people to manage their money and access services at the best available rates. Meanwhile, Experian also works with a range of businesses – from financial services to utilities, and insurance to the public sector – so is well placed to drive successful Open Banking initiatives. Working with FDATA and its members will further improve Experian’s prospects of encouraging governments and regulators to commit to delivering the highest possible standards in Open Banking. “Our membership will help us gain insights into policy issues that affect Open Banking and drive initiatives so consumers and businesses can gain greater access to fair and affordable credit,” said Paul Haddon, Vice President of Governance & Strategic Initiatives. ”Our launch of adding consumer-permissioned data to Experian credit reports called Experian Boost is a great example of how we are innovating and improving financial access for millions of people.” Launched in 2019, Experian Boost allows consumers to add positive payment history for telecommunications and utility bills to their Experian credit reports, which can possibly increase their credit scores instantly. Gavin Littlejohn, FDATA Global Chair, added, “FDATA is delighted at Experian’s decision to broaden the scope of their membership, a strategy that aligns a significant global footprint with FDATA’s ongoing expansion and engagement in multiple markets. A first step in the journey towards Open Finance, Open Banking is undergoing international proliferation. FDATA shapes and influences this dialogue at the earliest possible stages for the good of the consumer and the health of the ecosystem, providing invaluable insights from across market landscapes with regard to delivery and holding markets accountable for ongoing performance. These efforts rest on the pillars of rich, living repositories of comprehensive research, white papers and opinion pieces and, a proven history of successful lobbying and intervention on behalf of the membership. The addition of Experian’s voice to the FDATA membership extends the collaborative capability of the combined membership, enhancing the synergy between the members themselves. The unprecedented economic crisis brought about by the COVID-19 pandemic has seen a surge of innovative responses from the Fintech community throughout the global ecosystem. FDATA is uniquely placed to facilitate these conversations between industry, governments, and regulators, encouraging the potential of products and services to yield the best possible outcomes for SMEs and populations as a whole.”
At Experian, we’re dedicated to innovation and the COVID-19 pandemic has been an impetus for further innovation. Our driving force of successful innovation is our employees. We foster a culture of continuous innovation, from the way we work to the solutions we create. Global Hackathon As part of our effort to mitigate the impact of the pandemic, we’re launching Experian’s first-ever Global Hackathon. Taking place between June 1 and 5, we’ve invited all our employees to get involved and connect, share knowledge and find new ways to help our clients and consumers on the road to recovery from the COVID-19 pandemic. Mitigating COVID-19 Crisis Through Our Innovations In addition to the Global Hackathon, we’ve committed vast resources to develop innovative technologies and new sources of data and analytics to drive solutions that help people, businesses and society at large. For example, to aid in the United States re-opening efforts, Experian has made available a free interactive U.S. map showing populations at-risk of being most susceptible to developing severe cases of COVID-19. The Experian COVID-19 Outlook and Response Evaluator (CORE) tool is intended to help guide healthcare organizations and government agencies as they plan for COVID-19 recovery in the months ahead. The map leverages de-identified data such as pre-existing conditions and social determinants of health to form a comprehensive picture that predicts possible pandemic impact on communities. To help essential organizations during the pandemic, Experian also created At-Risk Audiences, which leverage our data assets to identify groups of individuals that are most likely to be impacted. These new privacy-compliant segments, offered free of charge, are designed to help these organizations find and communicate with at-risk populations, enabling them to deliver essential services as quickly as possible. In the UK, we’re working side-by-side with the government. As part of this, we’re building models to help predict how this disease will spread in local populations and predict the effectiveness of various treatment therapies. In Brazil, we’ve organized a coalition of universities, data companies and technology leaders to launch Covid Radar with the purpose of working together to minimize the impacts generated by the COVID-19 pandemic and contribute to the recovery of Brazil’s economy. The Covid Radar integrates companies to the hospitals and communities that need donations of ventilators, personal protection equipment, or other supplies. In addition to providing case monitoring and disease forecasting. The COVID-19 crisis has forced innovation and change on a scale and pace we wouldn’t normally see. We remain relentlessly focused on helping vulnerable communities, strengthening the resilience of businesses, and playing an important role in helping consumers and the world economy get back to strength. As part of our global innovation program, we’re hosting a global hackathon to help our employees create new ways to help our clients and consumers on the road to recovery from the COVID-19 pandemic. As one of the world’s most innovative companies, we’re doing everything at Experian we can to provide our unique insights back to key stakeholders so they can prioritize help those who need it most urgently.
Small businesses are the backbone of our nation’s economy, generating 44% of the nation’s overall revenue. When they take a hit, we all feel it. But as good neighbors – and frequent patrons – we can find a path toward keeping these small businesses on their feet and reopening their doors as soon as possible. At Experian, our obligation is to fight for small businesses that have been impacted by COVID-19. Main Street America reported in April that “COVID-19 has had a devastating impact on small businesses’ revenue…Approximately 35.7 million Americans employed by small businesses are at risk of unemployment as result of the COVID-19 crisis.” That is why we moved quickly to support the signing of the Coronavirus Aid, Relief, and Economic Security Act (CARES Act), providing relief to Americans through expanded unemployment coverage and by distributing grants and loans to small businesses. Acknowledging the unprecedented financial difficulties many are facing, lenders have established relief options for customers unable to make scheduled payments. In an effort to safeguard consumers against potential delinquency and protect credit, the CARES Act calls for creditors to adjust reporting systems for those taking advantage of these relief options. Simply put, your small business’s credit score shouldn’t be your biggest concern these days, and the CARES Act works to ensure that. We know there’s more work to be done to help small businesses navigate these challenging times. We’ve outlined the following steps to keep your business’s credit on track during the pandemic, taking advantage of resources and services we recently launched: Call Your Lender: If a customer or small business is unable to pay a bill, the most critical action they can take is to call their lender and inquire about available assistance programs. If consumers are able to get an accommodation, they can stop a missed payment from negatively impacting their credit. Business Resources Website: Experian has launched a website to help businesses prepare to manage increased attacks, push toward digital banking and understand regulatory changes as businesses find their footing in this evolving financial services landscape. Credit Report Access for All: Experian is offering all consumers access to a free credit report, FICO score and credit monitoring through our CreditWorks product, which also provides access to Experian Boost, a financial tool that has helped more than 2 million consumers increase their credit score to date. This is in addition to the free weekly credit score we are offering in coordination with our peers through annualcrediteport.com. COVID-19 U.S. Business Risk Index: Experian has launched a new service to help lenders and government organizations understand how to make lending options available to the business segments that need it most. This, in turn, directly helps small businesses gain access to capital they need. The public tool includes a risk simulator broken down by state to keep business owners updated on how COVID-19 is affecting specific industries in a particular region. As a nation, we have learned many lessons from the 2008 financial crisis. One vital lesson that sticks with us at Experian is that we’re better at tackling challenges as a collective financial industry, with transparency and a lending hand. At Experian, we’re committed to helping small businesses land back on their feet, and we’ll be there when the backbone of our economy needs additional support down the road.
To combat a growing threat that’s expected to drive $48 billion in annual online payment fraud losses by 20231, Experian® has announced the launch of Sure Profile™. Experian is the first company with an offering to combat synthetic identity fraud that is integrated into the credit profile with market-leading assurance. We are proud to be the first in our industry to actually put “skin-in-the-game” by sharing in fraud losses with our clients if the losses occur on assured profiles. Experian’s new offering validates consumer identities, detects profiles that have an increased risk for synthetic identity fraud and helps cover losses resulting from synthetic identity fraud for assured profiles. Leveraging the capabilities of the Experian Ascend Identity Platform™, Sure Profile utilizes Experian’s industry-leading data assets and data quality to drive advanced analytics that set a higher level of protection for lenders. Powered by newly developed machine learning and AI models, Sure Profile offers lenders a streamlined approach to define and detect synthetic identities early in the originations process. Experian’s Sure Profile differentiates between real people and potentially risky applicants, so lenders can confidently increase application approvals with less risk. We expect to authenticate most credit applications through Sure Profile. In the cases where the identity can’t be assured, the company will deliver additional fraud risk indicators, so that lenders can take the right next steps to verify the potential borrower’s identity and prevent fraud. To date, detecting synthetic identities has been a significant challenge for lenders because there’s not an industry standard or a single definition that can be used to establish the legitimacy of an identity. In addition, understanding the financial impact of synthetics has been difficult for lenders as losses tied to synthetic identity fraud are typically categorized as defaults or “bad debt.” With Sure Profile, we are reinforcing our position as a leader by creating a standard set of criteria to define a synthetic identity. Experian has always been a leader in combatting fraud, and with Sure Profile, we’re proud to deliver an industry-first fraud offering integrated into the credit profile that mitigates lender losses while protecting millions of consumers’ identities. Our investments in innovation, AI and machine learning and our data quality are enabling us to lead the way in identity protection and help protect consumers and lenders alike.
We are delighted to have announced our proposed acquisition of a 60% stake in Arvato Financial Solutions Risk Management division. Bringing together Experian’s global data expertise with AFS Risk Management’s market and sector experience will create a uniquely innovative organisation that can offer the best of both companies to the Germany, Austria & Switzerland (DACH) region. For us in Experian EMEA this is an incredibly exciting moment. Germany is Europe’s economic powerhouse and there is a huge opportunity to bring our Decisioning and Analytics expertise and products like Ascend Analytics on Demand to benefit existing and new clients of both organisations. Not only that, we have the privilege to work with a well-respected, established organisation like AFS Risk Management, with its deep focus on customer service, high-quality products, and solutions tailored for key industries like e-commerce, telecoms and insurance; and with the Bertelsman Group, one of Europe’s leading media groups. Following completion, our intention is to make a new, joint entity, made up of the best of Experian and AFS Risk Management, delivering broad coverage and a strong product and innovation roadmap across the DACH region. Clients of both organisations will quickly be able to benefit from the strengths each partner brings – as we deliver the best new technologies into the region, enabling them to make better, faster decisions, and ultimately delivering greater access to finance for people across the region. The acquisition now enters the EU’s standard competition review process.
As the COVID-19 pandemic continues to disrupt lives across the globe, fraudsters continue to take advantage of the vulnerable situation. The opportunistic nature of fraudsters means that times of crisis and pandemics open up additional breeding grounds for fraud and identity theft. Our latest CrossCore® release has never been more relevant for businesses than right now. Confidently recognizing consumers and safeguarding digital transactions is always a difficult balance – but now more critical than ever. With CrossCore, businesses can limit fraud losses and reduce unnecessary customer friction, at a time when safe and convenient access to financial services is essential. This new version of CrossCore, our integrated digital identity and fraud risk platform, combines risk-based authentication, identity proofing, and fraud detection into a single, cloud-based platform. This means that businesses have the capabilities and technology they need to rapidly respond to an ever-changing environment. With flexible decisioning orchestration, advanced analytics, and pre-integrated identity and fraud services, businesses can make real-time risk decisions throughout the customer lifecycle. And they can do all of this through simple self-service. We know there’s no silver bullet when it comes to fighting fraud, which is why we continue to develop our curated partner ecosystem. This gives companies access to all the technology and capabilities they need, in one place – whether it be Experian’s, our partners’, or their own. We combine this with advanced analytics and our own rich data assets plus a built-in strategy design and enhanced workflow giving fraud and compliance teams more control to adjust strategies based on evolving threats. This helps improve efficiency and reduce operational costs. Updates to the new version include the ability for clients to submit dynamic API request payloads, apply progressive risk assessments, apply parallel logic, enable self-service workflow configurations, and provide an online business intelligence (BI) module to view transactional volume reports. These updates will give CrossCore users a simpler way to manage complex orchestration; faster more scalable performance; and key performance indicators in near real-time, all while enabling a personalized and seamless experience for their true customers. More than 250 clients worldwide use CrossCore today, including capabilities from our third-party partners. To start leveraging best-in-class, pre-integrated identity and fraud services through simple self-service learn more about the Experian CrossCore platform.
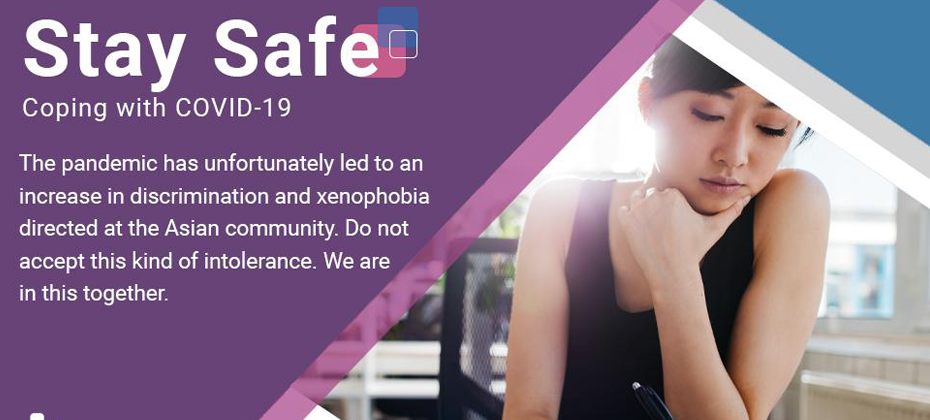
Today kicks off Asian Pacific American Heritage Month. The Experian Asian American Employee Resource Group (ERG) is proud to recognize this special month by sharing how Experian is supporting a national campaign to address the adversity facing some of our most at-risk communities right now. Experian has joined ten non-profits and more than 80 companies from across industries and sectors nationally to support the #AscendTogether action agenda. It includes promoting inclusion, raising awareness of vulnerable groups, denouncing bias, supporting frontline healthcare workers, COVID-19 victims and families, and donating funds and resources to support vulnerable populations and impacted businesses. Led by Pan-Asian leadership nonprofit Ascend, this effort is designed to bring about unity at a time when fear about COVID-19 has led to rise of intolerance and racist acts, particularly against the Asian and Asian-American community. Experian is proud to step up as a leader in our industry to participate in this effort. As executive co-sponsors of Experian’s Asian American ERG, we hope you will join us in our efforts to be a champion for diverse communities, especially during this time. You can learn more about #AscendTogether here. Written by: Dacy Yee, Chief Customer Officer ECS Direct-to-Consumer and Jimmy Cheung, Senior Vice President of Technology and Engineering
With the impact of COVID-19, we’re certainly in uncharted territory. Many people are struggling with high unemployment, which is resulting in missed credit card, utility, and rent payments. In response, Experian is joining forces with the other U.S. credit reporting agencies, to offer free weekly credit reports to all Americans for the next year via AnnualCreditReport.com. A credit report allows people to monitor their finances and better understand their overall financial health. We’re proud our industry is uniting to make this possible for all U.S. consumers starting today. Credit reports are updated constantly, so the ability for an individual to look at their report weekly is helpful to monitor for lender updates and ensure there is no fraudulent or unfamiliar activity. During these difficult times, this is especially important. In addition to the free weekly credit report at AnnualCreditReport.com, Experian also offers consumers free access to their credit report, FICO score, and ongoing credit monitoring at Experian.com. This is a no-charge product. We want to give consumers multiple options to access and manage their credit report. At Experian, we’re committed to enabling fair and responsible lending through the power of our data. As the consumer’s bureau, our goal is to not only help consumers build credit but to get better access to credit. All of us are working diligently every day to keep our data as accurate, relevant, and secure as possible so that lenders can use the data to responsibly extend credit to people who need it most especially when the economy returns to strength. What You Can Do Now The most vital action someone can take if they are unable to pay a bill is to talk with their lender and inquire about assistance programs that may be available. If a consumer receives an accommodation it will have minimal impact on their credit score if their account is in good standing and if there hasn’t been previous delinquencies reported We remain committed to informing, guiding, and protecting people during these unprecedented times. Beyond our offer for free credit reports, we’ve created a dedicated website, with links to multiple resources and materials to help the community learn about credit and other important personal finance topics. We encourage everyone to visit the Experian COVID-19 Resources & Credit Education. Take care and stay healthy.
The pandemic’s full economic impact is still unfolding, and I can assure you we have not stopped evaluating and evolving our COVID-19 response nor our thinking about economic recovery for consumers and businesses alike. In the last month, we’ve been driven by two major priorities. The first is the health and safety of our employees. On top of that, we have placed a laser focus on putting our resources to work to help people and businesses during these uncertain times. While we have all been adjusting to our ‘new normal’ working environment, our employees in North America have not slowed down. In fact, they have worked hard to create solutions and tools designed specifically to help people successfully navigate the evolving financial landscape. From free credit reports to complementary ‘payer alerts’ for healthcare organizations to consumer credit education, we’ve launched a wide-range of initiatives. Here are a few highlights I’d like to share with you: FOR CONSUMERS: Experian Credit Report and Score: Consumers can sign up and access their FICO® Score, Experian credit report, and ongoing credit monitoring through Experian’s free CreditWorks product. Consumers can also sign up to Experian Boost, a free financial tool that has helped more than 2 million consumers increase their credit score. Consumer Resources Website: As the consumer’s credit bureau, Experian’s commitment is to inform, guide and protect its consumers and customers during uncertain times. One way the company is doing this is through this dedicated website, with links to multiple resources and materials to help the community learn about credit and other important personal finance topics. COVID-19 and Your Credit Report: Being fully committed to helping consumers and lenders during this unprecedented period, Experian has created this dedicated blog page with ongoing and updated information pertaining to how COVID-19 may impact consumers’ creditworthiness and – ultimately – what people should do to preserve it. The blog will be updated with relevant news as Experian announces new solutions and tactics. #CreditChat: In response to the urgent and rapid changes associated with COVID-19, Experian is accelerating and enhancing its financial education programming to help consumers protect their financial health. With expected delays in bill payments, unprecedented layoffs, hiring freezes and related hardships, Experian seeks to aid consumers in understanding how the credit reporting system and personal finance overall will move forward in this landscape. Experian has launched an eight-week series of #CreditChat conversations surrounding COVID-19 on Wednesdays at 3 pm ET on Twitter and live video credit chats every Friday at 12:30 pm ET on Facebook Live. FOR BUSINESSES: Free Experian Business Credit Report: Experian is offering all American-owned small businesses free access to their Experian business credit report through May 1, 2020, to help small business owners impacted by the COVID-19 pandemic. By accessing a free business credit report now, small business owners can understand where their credit score stands and look for the best lending options for their business before they obtain funding. COVID-19 U.S. Business Risk Index: To further help small businesses gain access to capital they need, Experian launched its free COVID-19 U.S. Business Risk Index to assist lenders and government organizations in understanding how to make lending options available to the business segments that need it the most. This new risk index can help business risk professionals better understand the impact that the pandemic may have on commercial operations based on several key factors. This methodology combines business risk, anticipated impact on business industries and real-time COVID-19 case data to help businesses better simulate various impact scenarios down to the state level to help develop relevant strategies. Experian® Health Payer Policy Alerts: This is a free comprehensive list of COVID-19 and telehealth payer policy alerts for United States hospitals, medical groups, pharmacies and specialty healthcare service organizations. Payer policy alerts are provided by commercial, Medicare and Medicaid payers and summarize changes to medical coverage policies from those organizations. This public service to the healthcare community will continue to be updated and remain free as long as alerts related to the COVID-19 pandemic continue to be distributed. At-Risk Audiences: In an effort to help essential organizations, such as healthcare and government agencies, provide resources to those most in need during the COVID-19 pandemic, Experian is leveraging its data assets, free of charge, to identify groups of individuals that are most likely to be impacted. Experian developed new audience segments that are built in a privacy-compliant manner and designed to help these organizations find and communicate with at-risk populations, enabling them to deliver essential services as quickly as possible. Business Resources Website: This newly launched website was developed to help businesses prepare to manage increased attacks, continue to push toward digital banking, and understand regulatory changes as businesses find their footing in this evolving financial services landscape. FOR COMMUNITIES IN NEED: First Responders First: Experian North America is supporting first responder workers by donating funds for personal protective equipment (PPE) to COVID-19 for hotspots in New York City and New Orleans through the nonprofit organization, First Responders First. These funds will provide essential supplies, equipment and resources such as masks, gowns, gloves and more to those on the frontline. Heart of Experian Giving Opportunity: Experian is leading this effort in which employees can assist by making a donation to First Responders First through Experian’s Heart of Experian giving opportunity. Experian will match employee donations up to the annual limit of $500 per employee, while funds last. This donation is the latest support the company has provided to help minimize exposure for those most at risk. For example, in California, the company also donated 12,000 masks to the Hoag Medical Group. I’m proud of the work we’re doing at Experian to help those impacted by this crisis. We remain dedicated to our employees, consumers, businesses and communities – and we will continue to innovate and develop new offerings to help those in need. Craig Boundy CEO, Experian North America
As I reflect on the impact COVID-19 has had on my work and family life, I’m reminded of the things I once took for granted. My day-to-day routine has evolved into one of working from home, helping to take care of my toddler, and at times, doing so while on conference calls, sorting out the next grocery delivery, and writing this blog. While it’s a challenge, I’ve come to appreciate and value many of the things I’ve once taken for granted. But I also understand, I’m not the only person experiencing change. Across the globe, lives have been upended. The impact of the COVID-19 outbreak has been far-reaching and felt by hundreds of millions of people; whether due to family members that have fallen ill, job loss, shortened working hours or their children out of school. COVID-19 is an existential challenge that no one industry or entity can single-handedly address; we all need to play our part. Some companies, such as Fanatics, Ford, General Motors and Tesla, have shifted production efforts to focus on manufacturing medical resources, including personal protective equipment and ventilators. Others are donating free meals and resources to help consumers across the globe manage during this unprecedented time. Much like these organizations, Experian is committed to helping consumers and businesses navigate our current environment. We’ve expanded our financial education programming with the goal of helping consumers maintain good credit and protect their financial health. We’ve also offered small businesses free access to their Experian business credit report to help them better gauge their financial options and understand what capital is available to them. But as the world continues to combat the pandemic, we, like others, must look for new and additional ways to help. As essential organizations extend outreach efforts for those impacted by the outbreak, we believe data and technology can help them identify the groups that are most at-risk. With finite resources and limited bandwidth, it’s important for these organizations to communicate with at-risk populations and provide essential products and services as quickly as possible. With this urgency in mind, Experian developed At-Risk audience segments, which it is making available free of charge to essential organizations, such as government agencies, healthcare providers and non-governmental organizations, to help combat the fallout of the COVID-19 outbreak. The segments are built in a privacy-compliant manner and provide insights to help essential organizations reach those most in need. Organizations can use the information to determine where to allocate emergency funds, as well as redirect healthcare resources. Because the situation associated with the pandemic is changing seemingly every day and is impacting individuals in different ways and times, we also instituted a daily survey of the general population to gain insights around shifting consumer sentiment as a result of COVID-19. The insights from the survey will help organizations understand consumer sentiment during this difficult time and begin the process to identify at-risk populations. As of April 8, 2020, the survey found that: 73 percent of Baby Boomers are concerned about visiting the doctor and/or would hold off seeking care. 60 percent of Americans are concerned about filling prescriptions and/or accessing healthcare resources. 64 percent of Americans are concerned about their ability to access food and other essentials. COVID-19 has impacted consumers and businesses across the globe. As we all adapt to the new environment, we need to work together and collaborate to find ways to combat the fallout. Experian will not be stopping here, and we are committed to developing new ways to use our resources, data, technology, and creativity to help be part of the solution.

Recently, I had the privilege to serve on a panel during a joint workshop held by the Consumer Financial Protection Agency (CFPB) and the Federal Trade Commission (FTC) to examine the accuracy of credit reports and how to best serve consumers. During the workshop and in following written comments, I shared Experian’s commitment to advance accuracy in consumer credit information and our perspective on how the current regulatory environment supports our efforts to achieve continual improvements. At the workshop, we heard concerns about how inaccuracies in credit reports can impact consumers and businesses in terms of denial of credit or higher-priced credit. For Experian, these are real concerns. Our role as a credit reporting agency is to help facilitate fair and affordable credit to consumers and small businesses, and that’s why data accuracy is mission-critical and central to our corporate values. Since the workshop was held in Washington, DC, it’s no surprise that many stakeholders turned to the topic of reforming the existing regulatory system. Some stakeholders focused on making systemic changes in law and regulation, such as by setting very strict matching standards when credit bureaus receive and issue credit reports. But experience shows us that the current legal and regulatory standards are, indeed, appropriate and we don’t need a sledgehammer to hit a nail. Such actions would have unintended negative consequences and are unnecessary when all stakeholders share the goal of ensuring access to credit. In fact, the central theme I reinforced at the workshop was that the CFPB’s existing supervisory and examination authority, combined with market demand, industry investment and consumer expectations are the most effective ways to continually improve accuracy of credit reports. Let me explain how my over 30 years of experience with Experian leads me to this conclusion. Consumer reporting agencies, like Experian, are regulated by the Federal Fair Credit Reporting Act (FCRA). The FCRA requires that consumer reporting agencies “follow reasonable procedures to assure maximum possible accuracy” when assembling credit reports. Notably, this standard does not set an accuracy rate but appropriately recognizes the complexity brought about by a system with thousands of stakeholders (lenders, users of credit reports, and credit reporting companies reporting billions of pieces of information on hundreds of millions of consumers). It’s been more than eight years since we last saw comprehensive studies to determine the accuracy of credit reports. The two most cited are reports from the Policy and Economic Research Council (“PERC”) and FTC. One of the key findings in both studies was the percentage of consumers that were impacted by material errors in their credit report. In other words, errors that resulted in credit score changes that impacted the interest rate a consumer would pay on a loan. Both studies found that a small percentage of credit reports, 0.5% in the PERC Study and 2.2% in the FTC report, had material errors. While the percentages do represent many consumers (a minimum of 2.5 million to 4.4 million consumers) they also highlight the important need for continuous improvement so that material and consequential errors are the focus of innovation in data integrity. We don’t need to throw the baby out with the bathwater, we need to hone in on targeted and discrete changes. That’s my job at Experian, and I’m passionate about it. In addition to the “maximum possible accuracy” standard, market incentives provide another powerful mechanism to ensure improved data accuracy. Users of credit reports – ranging from banks to employers to government agencies – rely on accurate data to make critical decisions every day about loans, employment access, government benefits, and other important matters. Lenders need accurate data to perform sound risk assessments and provide terms tailored to the borrower’s appropriate risk level. As a result, credit reporting agencies compete to have the most reliable and accurate data. The same is true of lenders reporting data on their customers, as they have incentives to maintain good consumer relationships. Further, if inaccurate data is reported by a lender or maintained by a credit reporting agency, we all spend more time responding to consumer disputes instead of investing in new products and services to help consumers. It’s easy to see why inaccurate data just isn’t good for business! Since the FTC and PERC accuracy studies were completed, the regulatory environment for credit reporting has drastically changed. In 2012, the CFPB began to supervise and examine the credit reporting industry. This regulatory authority allows the CFPB to see the entire credit ecosystem that is composed of not only credit bureaus, but also lenders, other users of credit reports, and entities that furnish data to credit bureaus. CFPB’s comprehensive and continuous examination procedures include directly reviewing the policies, procedures, and practices of major credit reporting agencies. These steps include reviewing how data furnishers are screened, steps taken to minimize the likelihood of incorrect information on a report, measures to prevent duplicative information, and any programs designed to assess the accuracy of consumer information. These actions allow the CFPB to understand the metrics of accuracy and how it improves over time, and to apply the FCRA on a dynamic basis that can meet any challenges unforeseen when the law was originally passed. The CFPB’s supervisory authority thus serves as a powerful tool to holistically address data accuracy. In a 2017 supervisory report, the CFPB stated that “Credit reporting agencies have made significant advances to promote greater accuracy, the oversight of furnishers, and enhancements to the dispute resolution function.” It’s also important that there are ongoing discussions among the credit bureaus about how to move accuracy forward. To that end, joint efforts by the credit reporting agencies pursuant to an agreement with a group of state attorneys general, resulted in a joint working group to look at what can be done collectively to agree on improvements to accuracy. Recent changes include the delayed reporting of medical debt to allow time for insurance to process payments, and the removal of judgment and tax lien information, which did not meet new, elevated standards. The joint working group continues to explore new ways of increasing the accuracy of credit data. A broad, flexible, yet demanding legal structure, combined with strong market incentives and a robust and effective supervisory program, all work together to foster an environment to best serve consumers. As the consumer’s bureau, Experian is committed to playing a leading role in furthering a strong and accurate credit reporting system.
As I sit here on the day of the launch of the most comprehensive small business stimulus program in our nation’s history in response to the COVID-19 pandemic, my mind turns to the small business owners. Starting today, business owners can start applying for loans that are forgivable under the Small Business Administration’s $350 billion Paycheck Protection Program as long as those businesses maintain payroll to most of their staff and use the funds for eligible expenses. You’ve heard that small businesses are the heartbeat of the U.S. economy, the statistics back that up – small business represents a 47% of all employees and generate 43.5% of the Gross Domestic Product (GDP). More than their contributions to our economy, small business owners and their employees are the pillars of our communities, providing products, services, entertainment, and more. After the last few weeks, I think we can all appreciate the role small business plays in each of our lives. We, at Experian, take our purpose very seriously – creating a better tomorrow by creating opportunities for businesses to succeed. One thing we can count on in America is that small business owners rise to a challenge, it’s in the foundation of this great nation. Small business owners have the passion, fortitude, and downright grit to take them through the most challenging times – this time will be no exception. But I also know that now and then a little help is needed, and right now we need to help small business owners who are dealing with the immediate implications of the COVID-19 pandemic. Beginning today, an unprecedented level of government support will be made available through the Small Business Administration and other government bodies. At Experian, we applaud the signing of the Coronavirus Aid, Relief, and Economic Security Act (CARES Act) as it’s a great step toward economic recovery. The CARES Act provides grants and loans to small businesses with an unprecedented loan forgiveness program. We also feel an obligation to do our part to ensure that small businesses, who are dealing with the immediate implications of this economic crisis, have additional resources at their disposal to make informed decisions at this critical time. That’s why I’m proud to share that we have made available to every small business in the United States free access to their Experian Business Credit report until May 1st. Small business owners can get their reports at www.freecompanycredit.com. We also feel a deep obligation to our clients, the lenders, trade creditors, utilities, insurance underwriters, and more as they strive to support small businesses during this time. To further help small businesses gain access to capital they need, Experian also launched its free COVID-19 U.S. Business Risk Index to assist lenders and government organizations in understanding how to make lending options available to the business segments that need it the most. This new risk index can help business risk professionals better understand the impact that the pandemic may have on commercial operations based on several key factors. We also hope that our data and advanced analytics enable our clients to offer fair and responsible lending to small businesses that need it most during this time. I’ll close by urging the small business community to please take advantage of accessing your free Experian business credit report while continuing to show the grit and innovative spirit that has helped make America the most robust economy in the world. I’ll leave you with one of my favorite quotes, from Arianna Huffington, “Fearlessness is not the absence of fear. It’s the mastery of fear. It’s about getting up one more time than we fall down.” Sincerely, Hiq Lee
Related Posts
Experian’s groundbreaking generative AI-powered tool, Experian Assistant, has earned the prestigious 2025 BIG Innovation Award in the Products for Financial Services category. This recognition underscores Experian’s commitment to pushing the boundaries of innovation by helping businesses achieve success and enhancing consumer experiences. The BIG Innovation Awards, celebrated since 2011, honor organizations and solutions that redefine excellence through creativity and measurable impact. Experian Assistant was recognized for transforming how financial institutions approach data and analytics, enabling faster, smarter decision-making that enhances customer experiences and operational efficiency. Redefining Financial Services Integrated with the Experian Ascend Platform™, Experian Assistant functions as a 24/7 data expert, enabling financial institutions to optimize their credit and fraud models with ease. Using natural language processing (NLP), the virtual assistant guides users providing insights, recommendations and coding assistance. The impact is transformative: Experian Assistant cuts model-development timelines from months to just days— and even hours in some cases. By helping users analyze credit and fraud data, adjust model attributes and streamline workflows, it empowers organizations to innovate faster and make data-driven decisions with confidence. Powered by agentic AI technology, Experian Assistant reimagines how data scientists and analysts approach their work. It accelerates insights, fosters collaboration and empowers businesses to deliver exceptional customer experiences while reducing the time and resources needed to bring new initiatives to market. Driving Results Across Industries While tailored for financial services, Experian Assistant’s capabilities extend across industries. Businesses can leverage its tools for data exploration, model deployment, performance monitoring and faster time-to-market for new offerings. With Experian Assistant, users gain a powerful edge in scoring more consumers, optimizing processes and enhancing overall customer satisfaction. Recognized Excellence The 2025 BIG Innovation Awards spotlight trailblazers evaluated on creativity, impact and results by seasoned business leaders. This accolade solidifies Experian Assistant’s position as a game-changing solution in financial services and beyond.
We are thrilled that for the sixth consecutive year, Experian has earned a score of 100 on the Human Rights Campaign Foundation’s (HRCF) 2025 Corporate Equality Index (CEI). This recognition underscores our commitment to LGBTQ+ workplace equality. We are honored to join the ranks of 765 U.S. businesses that have been awarded the HRCF’s Equality 100 Award, celebrating our leadership in fostering an inclusive workplace. Experian’s dedication to supporting the LGBTQ+ community is reflected in several key initiatives: Name Change Process: We have a process for transgender and non-binary consumers to update their names on credit reports, ensuring their identities are accurately represented. LGBTQ+ Allyship 101 Training: This new training program is available to all Experian employees, promoting allyship and understanding within our workforce. Pride ERG Parenting Committee: Launched to support parents, grandparents and guardians of LGBTQ+ individuals, this committee provides valuable resources and community. Transgender Resource Guide: This guide supports employees who are transitioning at work, offering education and resources for colleagues and managers. Partnerships: We collaborate with organizations such as Out & Equal, GenderCool, The Trevor Project and Born This Way Foundation’s Channel Kindness to provide financial health, mental health and other resources to empower both our internal and external communities. At Experian, we are proud to be part of this movement towards greater equality and inclusion. We remain dedicated to fostering a workplace where every employee feels respected, valued and empowered to bring their authentic selves to work. Learn more about how we drive social impact in English, Portuguese and Spanish.
Achieving Top Workplace recognition for 12 consecutive years is no small feat, yet Experian North America has done just that. Named a Top Workplace by the Orange County Register once again, this milestone reflects not just policies or benefits but what truly makes Experian exceptional: our people. As Hiq Lee, Chief People Officer at Experian North America, notes, this honor is a testament to the remarkable contributions of our team. Experian’s employees shape an environment where innovation, inclusivity, and purpose thrive. More Than Work What sets Experian apart is our engagement with the world and community. Through initiatives like the Experian Volunteer Leadership Network and partnerships with organizations such as the Octane Foundation for Innovation and the Hispanic Chamber of Commerce of Orange County Education Foundation, our impact extends beyond the workplace. In 2024, we earned additional recognitions, including being named one of the World’s Best Workplaces™ by Fortune and Great Place to Work®. We were also recognized as one of the Best Workplaces for Parents, Millennials, and in Technology. The Secret to Success Our success lies in focusing on people. Experian is a place where careers are built, ideas are encouraged, and employees feel valued. Initiatives such as, Employee Resource Groups foster belonging, Mental Health First Aiders provide support, and technology hackathons inspire creativity. Innovation at the Core Innovation continues to drive our success. By leveraging technologies like artificial intelligence and machine learning, we are redefining decision-making and fraud prevention. This commitment to innovation empowers businesses and consumers worldwide, aligning with our mission to promote financial inclusivity. Looking Ahead For Experian, being a Top Workplace for more than a decade isn’t a finish line—it’s a springboard. With an ongoing commitment to our employees and communities, we continue to evolve, creating better experiences for our team, clients, and the world.
The rise of Generative AI (GenAI) is fueling a new wave of sophisticated fraud, transforming the financial services landscape. Experian’s 2024 Global Identity & Fraud Report highlights the challenges businesses face, and the strategies needed to protect consumers while maintaining seamless digital experiences. Based on insights from more than 1,000 business and fraud leaders, and 4,000 consumers worldwide, the report identifies three key forces shaping fraud prevention: GenAI-Powered Fraud: Fraudsters use AI to craft highly personalized attacks, exploiting vulnerabilities across the customer journey. Evolving Regulations: Stricter government requirements demand rapid adaptation of fraud prevention strategies. Customer Expectations: Consumers prioritize secure, efficient services. Many abandon brands after poor account-opening or transactional experiences. A Multi-Layered Defense The report emphasizes the need for a multi-layered approach to combat fraud effectively. Businesses are increasing investments in AI, machine learning, and data-sharing networks to detect and prevent fraud in real-time. “Fraud operates across borders and targets various points in the customer journey,” said Greg Wright, Experian’s Executive Vice President of Identity and Fraud. “Businesses must leverage advanced analytics and alternative data to stay ahead of these evolving threats.” Balancing Security and Experience Consumers value security, but demand convenience. Striking the right balance is critical, as many switch providers after experiencing delays or cumbersome processes. Businesses can succeed by: Using Advanced Analytics: Leveraging AI-driven insights to prevent fraud while maintaining smooth customer experiences. Orchestrating Fraud Prevention: Integrating tools to provide a 360-degree view of customers, ensuring fraud detection is seamless and comprehensive. The Path Forward The rise of GenAI fraud underscores the need for global collaboration and innovation. By adopting advanced technologies and prioritizing customer-centric solutions, businesses can protect consumers while fostering trust. Experian’s 2024 report offers actionable insights for navigating these challenges. Download the full report to learn how to outpace fraudsters while delivering secure, seamless experiences.
The advertising ecosystem has seen significant transformation over the past few years, with increased privacy regulation, changes in available signals, and the rise of channels like connected TV and retail media. These changes are impacting the way that consumers interact with brands and how brands understand and continue to deliver relevant messages to consumers with precision. Experian has been helping marketers navigate these changes, and as a result, our marketing data and identity solutions underpin much of today’s advertising industry. We’re committed to empowering marketers and agencies to understand and reach their target audiences, across all channels. Today, we are excited to announce our acquisition of Audigent—a leading data and activation platform in the advertising industry. With Audigent’s combination of first-party publisher data, inventory and deep supply-side distribution relationships, publishers, big and small, can empower marketers to better understand their customers, expand the reach of their target audiences and activate those audiences across the most impactful inventory. I am excited to bring together Audigent’s supply-side network as a natural extension to our existing demand-side capabilities. Audigent’s ability to combine inventory with targeted audiences using first-party, third-party and contextual signals provides the best of all worlds, allowing marketers to deliver campaigns centered on consumer choices, preferences, and behaviors. The addition of Audigent further strengthens our strategy to be the premier independent provider of marketing data and identity, ultimately creating more relevant experiences for consumers. To learn more about Experian and Audigent, visit https://www.experian.com/marketing/ and https://audigent.com/.
Modernizing the conversation around credit and financial literacy is a key commitment for Experian, especially for young adults. That’s why we partner with organizations like the Singleton Foundation to produce “Your World on Money,” to meet young people where they are, with engaging, easy-to-understand video shorts about credit, budgeting, and saving and more. We’re thrilled this commitment and creativity has earned both Gold and Bronze Anthem Awards, which recognize excellence in social good, celebrate the impactful work of organizations and initiatives that are driving positive change. Financial literacy is often not taught in schools, and the language around credit and personal finance can be intimidating. By normalizing these conversations, we hope to inspire confidence and action, helping young adults make informed financial decisions as they navigate life’s milestones. Our United for Financial Health partnership with the Singleton Foundation continues with our new series, the Finance Couch, where college students join our experts on a coach in the middle of a Los Angeles campus to answer their money questions. And our Anthem Award-winning series, HeartBroke, helps couples whose relationships are tested with financial issues to determine if they can work through it or end up HeartBroke(n).
Great Place to Work and Fortune have named Experian as one of the 25 World’s Best Workplaces™ 2024. This recognition highlights more than an award—it shows a commitment to our strong People First culture. Experian Chief People Officer Jacky Simmonds shares insights on how our people across the globe cultivate this culture, staying ahead of the curve through a unique blend of inclusivity, empathy, and a shared purpose. What does it mean to you, and to Experian, to be named among Fortune’s World’s Best Places to Work? At Experian, we have long aspired to be one of the best companies in the world to work for, and over the past few years, we have made this a priority. Our journey has been marked by a commitment to putting our people first and fostering the collaborative and inclusive culture that sets us apart. This recognition reflects the common values that we share across our many countries and cultures and the dedication of our colleagues across our business. We spend so much of our time at work, so I think it’s important that every interaction – from the interview process to joining and every daily interaction – is a positive one where people are welcoming, supportive and generally just really nice people to work with. Reaching this milestone gives all of us at Experian some recognition, but also it is inspiring as we continue to strive to attract top talent who share our values, share our purpose and make every day an enjoyable one. How does Experian create an environment where employees feel empowered to innovate and contribute ideas that drive real impact? To fulfill our mission of bringing Financial Power to All™, we need as many voices, experiences and backgrounds as possible, so we can represent our clients’ differing needs. This culture of inclusion drives our innovations. We have employee-led initiatives, such as internal Hackathons that bring together these diverse perspectives to develop products and services like Experian Boost, Experian Go, Experian Smart Money Digital Checking Account, Experian Support Hub, and Transforme-se so we can serve the communities in which we live and work. How has Experian adapted to changing employee expectations since the pandemic, and what steps has the company taken to support employee well-being and work-life balance? We know that our people really value the ability to have flexible work model, so they can work to fulfill their role in a way that works for them. For some this is fully remote, for others it is hybrid so a balance of remote and in office, and for others in office, where their role requires it fully. We know from the feedback that we get that our people appreciate that we trust them and they have flexibility to deal with varying commitments that we all have outside of work. We also know that since the pandemic there has been an increased focused on wellbeing. Sponsored by our Chief Financial Officer, we embarked upon an initiative to invest in how we support people who may need additional support. We are very proud of our Mental Health First Aiders programme, which has trained around 400 colleagues across the world representing 23 countries and 28 languages and helping their teammates access resources. These volunteers receive consistent, ongoing and updated training. What specific initiatives or programmes at Experian do you believe set the company apart in terms of supporting professional growth and career development? We have invested in a number of things that we believe really make the difference. The first is developing great leaders at every level. Today’s leaders have many more challenges, many different age groups, a balance of remote and in person working, together with teams based in many different locations. Great leaders build great teams, so we think it’s important to invest in their development. That’s we built a leadership development portal – The Leadership Exchange – that has a wide range of resources to support them, including development programmes tailored to their needs. We also want to ensure that everyone at every level can develop their skills and progress their careers. So we launched our annual Global Careers Week, Experian University, and built a world-class digital curriculum so everyone can access the form of development they need based on their role or aspirations. There really is something for everyone. This way, we help our teams stay ahead of trends and ensure our business is equipped with the skills needed for the future. Looking forward, what are key goals or priorities for further enhancing Experian’s culture and employee experience? We’re truly proud of this amazing recognition, but we always strive to get better and acknowledge there’s always more to be done. We see an opportunity to make things easier in the way we leverage advanced technologies like AI to further enhance employee experience. For example, more personalised learning pathways, improved tools for productivity and collaboration. We make sure we don’t lose the human touch, but we also want to make the most of these innovations so we stay relevant with our largely tech populations. Being named one of the world’s best workplaces reflects Experian’s unwavering commitment to be recognized for having a great culture where people can do their best work with people they enjoy working with. Learn more about what makes Experian a World’s Best Workplace in the People section of our Annual Report and the Experian Power of YOU Report 2024: Driving social impact and diversity, equity and inclusion, available in English, Portuguese and Spanish.
While the credit reporting industry is designed to help lenders and creditors minimize risk and assess consumers’ ability and willingness to repay outstanding debt, let’s be clear: the consumer is our main priority. Every lending decision and action is made with the consumers’ best interest in mind. Because consumers rely on credit and other loan products to purchase homes and cars, pay for college, afford goods and services, and even bridge the gap during emergencies, the credit reporting industry has been at the forefront of broadening access to fair and affordable financial resources. Risk-based pricing has made it possible for more consumers to access credit, particularly those with limited-to-no credit history or subprime credit profiles. Previously, lenders may have opted not to extend credit to consumers considered higher risk; but more and more, lenders are empowered to tailor borrowing terms based on a consumer’s credit history. In addition, because lenders don’t have to absorb unforeseen risk, lower borrowing costs can be maintained for all consumers. Experian has long advocated for expanded data sources, such as rent and utilities payments, to be incorporated onto consumer credit reports and considered in lending decisions. In 2019, we launched a product that empowers consumers to add positive payment history for utilities, telecoms and video streaming services—and eventually residential rent—directly into their Experian credit report. Our efforts coincide with legislation, such as S.2417 – the Credit Access and Inclusion Act, introduced by Senator Tim Scott (R-SC) in 2021, which encourages the reporting of consumer payment history, including rent, utilities, and telecom services, to the nationwide credit reporting agencies. This is key to broadening access to fair and affordable credit for underserved consumers. The industry needs to continue to explore other avenues that can help consumers improve their financial health, such as the role that buy now, pay later information can play in increasing financial inclusion. Empowering consumers to take control Beyond legislation or the use of expanded data, many non-profit and community based organizations are championing initiatives that drive greater financial inclusion. Organizations such as Inclusiv, Jump$tart Coalition for Personal Financial Literacy, HomeFree-USA, National Urban League and the Society for Financial Education & Personal Development, among others, are helping individuals and households from underserved communities navigate the mainstream financial system and take control of their financial lives. Experian and other financial institutions are partnering with non-profit organizations with deep roots in communities, allowing them to connect with community leaders and individuals on a more personal level. Every individual enters the credit ecosystem at a different stage so it’s important that banks and financial institutions listen to the specific challenges they’re experiencing. For example, individuals may be searching for credit monitoring and alerts, budgeting tools or ways to put more money back into their wallets, such as finding cost-efficient options for auto insurance. Providing individuals and households with the financial knowledge and access to tools better positions them to become financially independent. The credit reporting industry continues to provide more resources and transparency to help improve consumers’ financial health. All individuals deserve the opportunity to establish and build their credit so they are able to elevate and maintain their financial status.
Today at Money 20/20 in Las Vegas, Experian unveiled Experian Assistant, a groundbreaking toolset that transforms analytics and modeling for financial institutions. By leveraging Generative AI (GenAI), this revolutionary solution slashes model development turning months-long processes into days—or even hours. Positioned as a game-changer, Experian Assistant offers businesses the equivalent of a seasoned expert, guiding them through complex use cases with ease and redefining how financial organizations approach data-driven insights. Revolutionizing Modeling with Generative AI Experian Assistant marks a significant leap forward in how businesses handle the modeling lifecycle. Integrated into the Experian Ascend Technology Platform™, Experian Assistant is designed to streamline data analytics processes, enhance accuracy, and promote efficiency. This debut underscores Experian’s commitment to responsible AI innovation, ensuring that organizations benefit from advanced analytics without compromising on privacy or ethical standards. “Many financial institutions are looking to invest in new generative AI use cases, often focused on banker specific support,” said Craig Focardi, Principal Analyst at Celent. “Experian Assistant focuses on developer support to accelerate the development lifecycle by having a digital model building consultant available to users.” Empowering Data Scientists and Analysts With its powerful natural language processing (NLP) capabilities, Experian Assistant is reshaping how data scientists and analysts approach complex tasks. Traditionally, navigating large datasets and building models required extensive technical expertise. But now, Experian Assistant allows users to query data, write code, and build models in plain language—democratizing access to sophisticated analytics. The tool not only boosts productivity but also fosters collaboration and accessibility. This innovation will drive financial inclusion by broadening access to data-driven insights and responsible use of data across organizations. Developed in Collaboration with Leading Financial Institutions A standout feature of Experian Assistant is its development in close partnership with the world’s largest financial institutions. This collaboration ensures that the tool is finely tuned to real-world challenges, delivering deep insights into Experian’s data assets. By optimizing analytics processes, businesses can achieve proven cost savings, enhanced data visibility, and faster product deployment. Continental Finance Company, for example, reduced data-building time by a remarkable 75% after adopting Experian Assistant. This kind of impact highlights the tool’s ability to accelerate model development while maintaining strict data privacy standards—a vital consideration for financial institutions. Advanced Compliance and Transparency In today’s highly regulated environment, businesses must not only meet compliance standards but also provide transparency into their processes. Experian Assistant is designed with these needs in mind, offering advanced features that support regulatory reporting, identity management, risk assessments, and transaction monitoring. A Competitive Edge through GenAI With more than a decade of AI expertise, Experian is leading the charge in responsible AI development. At Money 20/20, Experian Assistant stood out as a testament to this leadership. The tool is positioned to offer financial institutions a competitive edge, improving risk assessment, enhancing customer experiences, and promoting financial inclusion. As the financial services industry continues to evolve, businesses that embrace GenAI solutions like Experian Assistant will be better positioned to succeed. This groundbreaking tool is not just an enhancement—it’s a fundamental shift in how analytics and modeling are conducted, offering the speed, accuracy, and transparency that today’s market demands.
People rely on credit cards, personal loans, mortgages and auto loans, among other financial products to buy homes, fund college educations, weather temporary income disruptions and finance billions of daily transactions for goods and services. Credit is the cornerstone of the pursuit of our financial ambitions. That’s why the credit reporting industry is deeply committed to broadening access to fair and affordable financial resources for all consumers, particularly for individuals and households from underserved communities. The commitment is underscored by the continual effort to evolve the credit reporting system and incorporate new data sets to provide lenders a more comprehensive view of consumers’ ability and capacity to repay outstanding debt. Although progress has been made to extend credit to more prospective borrowers across the risk spectrum, if we want to continue to broaden the scope, we need to encourage the consistent reporting of additional predictive data sources to help lenders assess consumers’ creditworthiness. A proven track record but there’s more work to do Over the past century, the credit reporting industry transitioned from an opaque system founded on relationships to one rooted in data. Lenders lean on past payment history on similar loans (i.e., auto loans, mortgages, credit cards, etc.) as a reliable predictor of a borrower’s future loan payment performance—it’s a way for them to mitigate risk and say “yes” to more borrowers. And it works. The comprehensive reporting of past loan performance, coupled with increasingly sophisticated statistical prediction models, as well as the adoption of risk-based pricing, accelerated the extension of credit to more consumers. Yet, according to research from Experian and Oliver Wyman, millions of Americans lack access to mainstream credit because they are credit invisible, unscorable or have a subprime credit score. It’s particularly challenging for younger individuals, newly arrived immigrants and historically underserved communities, such as racial and ethnic minorities. At times it can be a catch-22; in order to get credit, you have to have credit. More predictive data is key At Experian, we’ve long understood that expanding the universe of creditworthy borrowers requires more data. In addition to some of the more conventional tradelines, such as mortgages, auto loans and credit cards, we have to explore expanded data sources that are predictive of a prospective borrower’s credit risk. For instance, more consumers are using buy now, pay later (BNPL) products, and nearly every consumer makes recurring monthly payments for rent, utilities, cell phones and even video streaming services, yet oftentimes, these data points are not consistently reported to the credit reporting agencies nor considered during lending decisions. Collectively, the industry and regulators, need to do more to encourage the consistent reporting and inclusion of expanded data onto consumers’ credit reports. In fact, based on our research, we’ve found that some of the aforementioned expanded data sources can empower lenders to assess the credit risk of a significantly larger pool of consumers. These expanded data sources have been shown to be highly accurate predictors of future loan payment behavior. And, when expanded data is combined with advanced analytics, up to 96% of the population can be scored, including an estimated 65% of credit invisibles.1 Broadening access to fair and affordable credit for more consumers means leaning into combining conventional tradelines with expanded Fair Credit Report Act-regulated data sources. The more information lenders have available to them about prospective borrowers’ past payment performance the more empowered they are to minimize risk and more confidently extend credit. Pushing for more data is the best path forward.
In an era where financial transactions occur at the click of a button, the significance of accurately verifying and authenticating consumers’ identities cannot be overstated. From online purchases to mobile banking, ensuring secure and reliable digital connections and safeguarding consumers’ information are table stakes for any business operating in the digital ecosystem. Unfortunately, some advocacy groups are calling for stricter regulatory guidelines that may impede business’ ability to effectively and efficiently protect a consumer’s financial information and identity. We’re, of course, referring to the push to classify credit header data— identifying information, such as name, current and former addresses, phone number and Social Security number, found at the top of credit reports—as a consumer report under the Fair Credit Reporting Act (FCRA). Subjecting credit header information to the FCRA will unnecessarily limit its permitted use, and effectively make it more difficult—and potentially impossible—for banks and other businesses to use the information to authenticate and verify consumers’ identities. It’s an unintended consequence that will surely compromise the security of our digital identities. Foundational to fraud prevention Credit header data plays a pivotal role in helping businesses detect suspicious activity and stay ahead of increasingly sophisticated fraud schemes. With credit header information, banks and other financial institutions cross-reference loan applications against transactions from hundreds of thousands of contributors to spot anomalies and thwart fraudsters before they inflict harm. In fact, many of the industry’s most advanced fraud prevention tools and signals rely on credit header data to verify the legitimacy of any given transaction. Keep in mind, the transactions we’re referring to are transactions of consequence. For instance, opening a new bank account, applying for a loan or transferring money. This level of activity carries inherent risk, and without proper vigilance, could result in significant financial or reputational harm to consumers and businesses. But it’s not only lenders that leverage credit header data, the use cases for credit header data are broad. Government agencies and businesses in the public sector, law enforcement, and some pharmacies use the information to issue one-time passcodes for identification purposes, find missing persons, or verify consumers’ identities prior to prescriptions being filled. Credit header data is already regulated Some of the concern surrounding credit header data centers on consumer privacy, and rightfully so. Protecting consumers’ privacy should be central to the use of sensitive information; however, credit header data is already regulated by the Gramm-Leach-Bliley Act. In fact, for more than 25 years, the Gramm-Leach-Bliley Act specifically provides that the permissible use of credit header data includes fraud prevention, while also mandating consumer privacy and data protection. Subjecting credit header data to additional FCRA regulation, which does not clearly allow for fraud prevention, could make it impractical or impossible for many businesses to use it for that purpose. Not only is additional regulation unnecessary, but it potentially creates a contradictory web of regulations that increases the compliance burden and confusion for many businesses. This ultimately thwarts the purpose of GLBA by delaying fraud prevention efforts and potentially raising costs for consumers. Credit header data is far more than information included at the top of consumers’ credit reports, it is a linchpin that powers many of the most advanced fraud prevention and identify verification tools in the market. Before any further regulation is considered, we have to acknowledge the role that credit header data plays in keeping consumers’ information safe and how any changes may impact the safety and soundness of our digital economy.
Experian continues to affirm its leadership in financial technology, earning the 7th spot on the 2024 IDC FinTech Rankings. This is the third consecutive year that the company has ranked among the top 10 providers, reinforcing its position as a key player in the FinTech space. The IDC FinTech Rankings assess the top 100 financial technology providers based on revenues generated in 2023 from financial services and FinTech sectors. In addition to this notable achievement, Experian has been awarded the 2024 IDC Real Results Award for Bank Deposit Transformation. This award highlights Experian’s innovation in driving measurable and impactful changes within the financial services industry. The recognition is particularly focused on the company’s success in helping banks transform their deposit processes through advanced fraud prevention technologies. Experian’s Ascend Fraud Sandbox: A Game-Changer A key factor behind this award is Experian’s Ascend Fraud Sandbox, a groundbreaking tool that offers financial institutions a comprehensive platform for fraud detection and prevention. The Ascend Fraud Sandbox empowers organizations to analyze data, identify new fraud patterns, and quickly build, test, and deploy models. This technology enables banks to enhance their fraud detection capabilities, leading to higher approval rates for online deposit accounts and reduced fraud-related losses. The sandbox operates with over 10 billion identity and fraud events, which include applications, login activities, and transactions. It also continuously incorporates tens of millions of new events each day. This expansive dataset allows banks to stay ahead of increasingly sophisticated fraud attempts, especially those driven by artificial intelligence (AI). Experian’s success in Bank Deposit Transformation demonstrates the company’s ability to help financial institutions improve their processes while simultaneously enhancing fraud protection. By providing advanced fraud-prevention and identity-protection technologies, Experian enables its customers to optimize their operations, reduce risks, and achieve better financial outcomes. Recognition of Experian’s Innovation This dual recognition—ranking 7th in the IDC FinTech Rankings and winning the Real Results Award—further solidifies Experian’s standing as a leader in technology. These accolades underscore its capacity to offer data, technology, and scalable solutions that allow financial institutions to make informed business decisions at the necessary speed to remain competitive in an evolving market. Now in its 21st year, the IDC FinTech Rankings evaluate technology providers based on the revenue they generate from financial institutions, including banks, insurers, and capital markets firms. With both the FinTech Rankings and the Real Results Award in hand, Experian continues to deliver innovative solutions that help financial institutions navigate the complexities of modern finance with confidence.