World
News about Experian from all over the globe:
Five years ago, I began volunteering as an Experian Ambassador, teaching personal finance to local high school students. It is so rewarding to share my credit knowledge with young people, and to see their eyes light up when they understand how credit works. I ended up starting my career at Experian 26 years ago because my passion for credit runs in my blood. I was raised in a household where reputation was everything to my father. The idea of having a good name, a good reputation and a good credit score was drilled into me. So, when Experian created the Ambassador Program to promote financial literacy in local communities through employee volunteers, I jumped at the chance to participate. At the time, I was an Account Executive and knew that for most consumers, credit is an obscure subject. I thought this program would be a great opportunity to apply my expertise and educate people in my community about the importance of taking their financial reputation seriously. As an Ambassador, I gave my first presentation on financial literacy to high school students, and the experience was so rewarding that I immediately contacted my son’s high school to see if I could teach the same class to his classmates. The program has grown to where I now go to the school twice a year, teaching the entire student body of 4,000 students about how they can responsibly build their credit. For each class, I share personal stories and anecdotal examples that are relatable to them. For example, to explain how credit scores affect consumers, I ask every student to think of number between 350 and 800. I then pick three volunteers to come to the stage – one who chose a number in the low range, one from the mid-range and third from the higher range. I then ask those three kids to agree on the dream car they would buy. Once they agree on the make and model, we talk about how the price of the car is the same for everyone, but that their credit score determines the loan financing. Someone with a higher credit score will pay much less over the life of a car loan than someone with a lower score. That’s the moment my students’ eyes light up, because they finally understand how credit works. Over the years, I’ve had kids come up to me in grocery stores and thank me for teaching them about credit. One young man in particular came up to me at a local farmer’s market, beaming. “I remember when you taught me about credit scores,” he said. “Because of you, I was able to save money, get a secured card, build my credit and buy my first car.” His pride was infectious. Credit has an impact in everyone’s life at some point. By speaking to students at a young age, in terms and language they understand, I’ve helped countless students successfully and safely build credit to help them reach their first financial milestones. I am proud of the opportunity I have been given at Experian to help young people to take control of their financial futures.
I’m constantly amazed at how Experian gets to uncover and bring to life the data that really matters. By partnering with the National Literacy Trust to analyze different data sets, we uncovered a widespread literacy crisis in England. A while back, Experian was approached by the National Literacy Trust in England, asking us to collect information to help them better understand how far-reaching literacy problems are in England. Using data from Experian, the National Literacy Trust and the 2011 census, our data analytics team compared data sets against social factors that are closely associated with low literacy levels, such as education, income and unemployment rates. Through this in-depth analysis, we were able to create a literacy vulnerability score for every single electoral ward and parliamentary constituency in England. We found that 86 percent of all English constituencies have entrenched problems with literacy. What was most surprising was how far-reaching the problem was across the country. I guess I had assumed, as most would, that in the more affluent areas where there are good levels of education, higher incomes and higher employment rates, children would have a good relationship with books. We found, however, that it doesn’t matter what community you live in, or how affluent or deprived the area is – literacy issues can affect all of us. While the initial reaction by the public has been one of shock, I really think this study was something England needed to help the next generation avoid the same problems. Working alongside the National Literacy Trust, we’re leveraging this data to raise awareness within the government. Early in February 2017, we supported an event for Members of Parliament (MPs) to highlight how the issue may affect their constituencies, using a ranking table that shows which areas are the most affected. You could say this literacy issue is a bit of a crisis, and MPs would now agree. In my role at Experian, I frequently look at what we call “societal impact stories” that highlight how Experian is engaged in local communities. What I love about my job is getting to see how all the powerful information we have on hand is being used to lay the foundations for others to transform lives and local communities for the better. While there is still much work to be done to solve the literacy issue in England, I’m constantly amazed at how we at Experian get to uncover and bring to life the data that really matters.
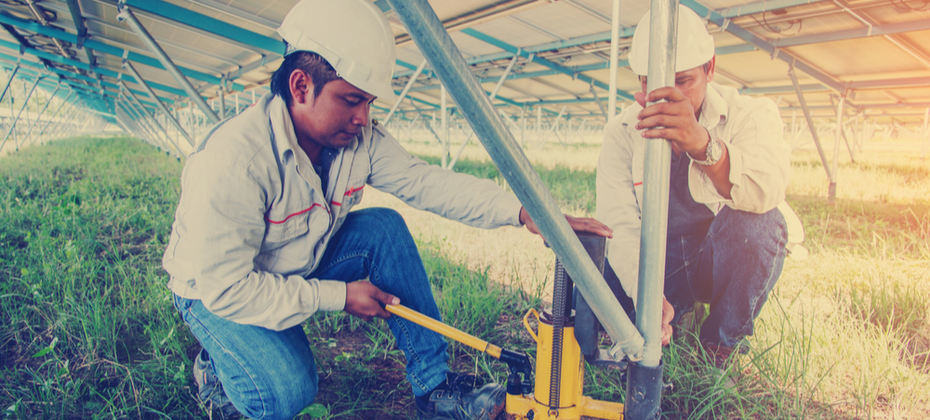
In Malaysia, nearly 280,000 people live without electricity. By volunteering with the Liter of Light program, we’re bringing solar panel lights to remote villages, transforming the quality of life and brightening the darker hours for families. In Malaysia, more than 1 percent of the population lives without electricity – one of life’s basic necessities – which equates to nearly 280,000 people living in darkness after the sun goes down. Some people have never had electricity in their life, making simple tasks like cooking or reading nearly impossible after dark. I wanted to change that. My day job is to support and enable individuals within Experian to pursue various career opportunities, but what I’m most passionate about is the way Experian helps me invest in my local community through the Heart of Experian Corporate Social Responsibility program. This year, my team and I had the chance to collaborate with Liter of Light (LOL) – a global, grassroots movement committed to providing affordable, sustainable solar light to people with limited or no access to electricity. In February, we joined one of their projects to install 60 solar street lights in the village of Orang Asli, an indigenous community in the Cameron Highlands. Over the span of two days in February, a group of 30 Experian volunteers built and installed the solar panel lights. On the first day, the LOL team taught us how to build the panels, teaching us the skills needed to cut wire, assemble PVC pipes and drill holes. The second day, we rode in Jeeps through muddy roads and a three-foot deep river to reach the village. We spent hours unloading the lights and assembling the panel boxes, plotting the village maps and identifying the right spots to install the solar panel lights. I was happy to see some of the local villagers’ curiosity and participation throughout the day. Some helped us assemble the lights while others prepared the right spots for installation by building bamboo stands. The weather was kind to us, so by 5 p.m., nearly all the lights were installed – just before dark! After completing all the hard work, our team recorded a group video using a drone that all of the Orang Asli children chased after. Thanks to our service project providing light to a village in darkness, 150 villagers in Orang Asli will now have more productive, higher-quality lives during the dark hours of the day. I’m so glad I got to play a role in that.
Becoming a victim of identity theft and fraud can be a constant fear for many consumers. In fact, according to Experian’s recent Identity Theft Survey findings, 84 percent of respondents acknowledged concern about the security of their personal information online. Surprisingly, despite this overwhelming concern, our survey also found that nearly two-thirds (64 percent) of consumers also believe it’s “too much of a hassle to constantly worry about securing personal information online.” With personal vigilance declining and identity theft on the rise, developing the right consumer tools is essential. Today’s consumers demand easy-to-use, reliable identity protection products that give visibility to their personal and financial information’s possible theft and fraud exposure. In response to this growing need, we’ve launched IdentityWorks – a comprehensive identity theft protection product which helps consumers become actively engaged in defending themselves against identity fraud. For example, IdentityWorks’ dark web monitoring and alerts help consumers manage the risk of exposure in a place they can’t even see or access. Most consumers don’t really know anything about the dark web – other than it’s a bad “place.” The product also allows a user to instantly lock or unlock their Experian credit file, literally by clicking or tapping an icon via desktop or mobile device. It’s that simple. In addition to providing an array of user-friendly tools, IdentityWorks offers a set of resources to give consumers peace of mind. If suspicious activity is detected, Experian’s team of fraud resolution specialists are available to guide consumers through the process of repairing the damage done and shielding them from additional damage. Furthermore, while we work to secure your information, up to $1 million in identity theft insurance is available, just in case. * We know consumers perceive keeping track of, and protecting one’s identity as complex and inconvenient. According to our Identity Theft Survey, approximately 53 percent of individuals believe staying on top of financial transactions is a challenge. That’s why we believe IdentityWorks is exactly the right solution at the right time. It reduces the scale of that challenge into something much more manageable, with resources for both monitoring and remediating identity theft and fraud. The responsible use of credit can propel consumers’ livelihoods – helping to qualify opportunities like affordable mortgages and automotive loans – but identity theft can make it more difficult to obtain credit, making someone’s good credit history look poor. This is why IdentityWorks is so relevant to Experian. We are driven to help consumers achieve their long-term financial dreams. By enabling consumers’ active role in protecting themselves from identity theft and fraud, we help them buy a home, purchase a car or invest in their education. We hope the launch of IdentityWorks will empower consumers to manage their financial futures and remain vigilant against those who would take that away. * Identity Theft Insurance is underwritten by insurance company subsidiaries or affiliates of American International Group, Inc. (AIG). 175 Water Street, New York, New York 10038. Please refer to the actual policies for terms, conditions, and exclusions of coverage. Coverage may not be available in all jurisdictions.
When it comes to credit for small businesses, it’s a classic chicken-and-egg situation: you can’t get credit until you have credit history, and you can’t get credit history until someone grants you credit. I know this first-hand because my own parents were small-business owners in California. My parents had built an independent insurance agency. I distinctly remember as a kid sitting in the backseat of our car and overhearing the discussions they would have about their struggles to grow the business or how they would make payroll that month. Many small businesses don’t have access to small-business loans or business credit cards, so they rely entirely on the business owner’s personal credit to make purchases. This means that while there may be a credit history for the individual, there is none for the business itself. This also means that whenever my parents needed money to get through the month, they essentially had to put their livelihood at risk because there was no separation between personal and business loans. The lack of access to funds, and the consolidation happening in the insurance industry at the time, led my parents to take another big risk – they sold the business and our house, and they liquidated their retirement accounts and put everything into a restaurant franchise. They felt there would be more stability representing an established brand owned by someone else. When I graduated from my MBA program years later, one of the things that first attracted me to Experian was the opportunity I had to ease the burdens of small business owners through my work here. The work I do really hits home, because I’m working every day to open up small-business credit, using different types of data. In today’s economy, a lot of great business ideas – profitable ones, at that – never get a chance to see the light of day simply because they don’t have the capital they need to grow. Experian is making business ideas a reality by gathering, analysing, combining and processing a breadth of new data that allows us to develop credit scores for more people and paint the most realistic picture of a situation. By verifying a business’s history, its social media accounts, its website sophistication and traffic, and customer reviews, we can measure a small business’s legitimacy, how long they’ve been operating and how they’re growing. This information, coupled with transaction data, all help determine a business’s credit worthiness and allow us to give its owners greater access to capital. Data is a huge enabler for positive change because it can give small-business owners access to credit that they wouldn’t receive otherwise. When used in the right ways, data can empower and enable small businesses to get the funding they need to hire employees, invest in their business or open a new location. In many ways, I’m helping people just like my parents.
About a year ago, my colleague Natalia invited me to join her in a new volunteer opportunity with the Ministry of Housing in Colombia. The Ministry had created a new program called Mi Casa Ya – which means in English “My Own Home Now,” to help people in Colombia own their first homes. Excited and eager to lend a hand, Natalia and I introduced ourselves to Alejandro, the Director of the National Housing Fund at the Ministry of Housing. Alejandro told us how an unexpected roadblock threatened to derail the program. He had created Mi Casa Ya so that even the poorest people in the country could get a government subsidy to purchase a home. To get the subsidy, they just needed to qualify for a mortgage from a local bank. But that was the problem. In order to get the bank loan, applicants needed a strong credit history. Yet most of the people looking to take advantage of the subsidy through Mi Casa Ya, he explained, were considered “credit invisible.” That is, they had no viable credit history, thin or un-scoreable credit files, or they simply had bad credit. So banks had no choice but to reject them. Natalia and I heard the frustration in Alejandro’s voice, and we knew just how we could help. We told Alejandro that if the Ministry could determine which individuals were being rejected by the banks, we could come in and build credit scores for them using Experian’s data. You see, building credit histories is the sort of thing we do every day at Experian. Over the years, Experian has innovated with analyzing traditional and alternative data sources, such as public records and magazine subscriptions, to create the most accurate and realistic picture of someone’s credit. And by unlocking the power of this data, we are able to identify the data sets that can help lenders make better decisions when making loans, especially for people with thin credit files. Working with Natalia and Alejandro for Mi Casa Ya over the past year has been incredibly rewarding – and our work here isn’t done! Since I work in the legal department at Experian, I am now involved in reaching an agreement with the Ministry of Housing to help advance this project. The details are tricky and the process is tedious, but when I think about the people whose lives we have the ability to transform, I just get excited. Because of our work, many more families in Colombia will be able to fulfill their dream of owning their own homes – that’s huge.
By volunteering through Experian’s Sohos Reais – Real Dreams – project, I taught a mother of five about understanding basic business concepts so she could expand her sewing business and keep pursuing her dream. I grew up with parents who loved helping others, which fostered my love for volunteerism. Now that I work at Experian, this passion has blossomed as I’ve volunteered in many different capacities, from dressing as a clown to cheer up people in hospitals, to helping teach financial literacy to small-business owners in São Paulo, Brazil. Experian’s Sohos Reais – Real Dreams – program is designed to help connect entrepreneurs and small-business owners with experts who can advise them on how to help their business succeed. My volunteer partner, Diana, and I went through the training together, and a few months later were contacted by Aliança Empreendedora – Experian’s project partner – to help support a local entrepreneur. We were sent information about a woman named Adriana who was looking for advice for her sewing business. When we first met at Adriana’s house, she welcomed us into her home, fed us toast and black coffee, and introduced us to her five children. Adriana is a single mom whose husband left her after becoming a drug dealer. She told us how he had stopped supporting her and the children financially, and how Adriana now relied on her sewing business to support herself and the children – two of whom had serious health issues. Creating this business had been her dream since she was 12, when she had made her first dress for a school party. Now, she sewed colorful shopping bags and purses every day that she sold for R$1.25 a piece – a tiny price compared with the amount of work it took her to produce them. While she loved her job, Adriana told us that the money she made from her sales barely allowed her to cover basic living expenses, like water and electricity. She was on the brink of giving up her dream. The more we talked with Adriana, the more Diana and I realized that what she needed most was someone to help her understand basic business concepts, like cost and revenue. I thought that if we could help her control the money going out, we could solve a lot of her problems. Adriana was eager to learn, so right then and there, I showed her how, by keeping track of costs and profits, she could pay her bills and start to save money for her family. After our first meeting, a group of us from Experian were so inspired by her story that we raised R$1,415 for Adriana to buy fabric for her bags, and gave her a book to help her track her finances. Now every time we meet, Adriana brings the book with her, full of notes – she says it helps her work out her profit from the bags she sells so she knows how much more fabric she can buy. I never imagined that just sharing my financial knowledge with someone could help change their life. By volunteering with Real Dreams, Diana and I helped Adriana get back on her feet and continue pursuing her dream as a small-business owner and provider for her family.
I recently attended a conference in Alwar, India, hosted by Experian and the International Finance Corporation. During one of the sessions, I met a single mother of two who had recently moved to a rural village in India. Her husband had left her and she was hoping to pick up work as a tailor once she purchased a sewing machine to support her family. As we talked, she confided in me that she was having trouble securing a loan from microfinance institutions because she didn’t have papers to prove her identity. And since she was new to the village, no one knew who she was. Without a proven identity, she couldn’t qualify for a loan and get the money she needed to support herself and feed her children. Indian banks predominantly serve urban customers whose credit reports are extensive. However, most customers from smaller districts and rural towns – like this woman – can fit their credit history on less than a page. Identification may be the only way they can verify their character to secure a loan. As I sat with this woman, I started telling her about our Prove ID tool that I had recently helped to develop. Using an individual’s biometrics, the tool would search her credit history, bank card and any information that can prove she is who she claimed to be. I explained that by using this tool, she could now prove what village she’s from, that she was a permanent resident in her new village and that she was likely to repay her loan. She was stunned and overwhelmed. In that moment, I realized that rural clients often need human connection to clearly understand what a bank or microfinance institution requires in order to obtain a loan. Many rural customers can’t read the brochures or pamphlets sitting in a bank, but by engaging them in conversation, you can effectively educate them about how to prove their identities and build their credit profiles to successfully access the finances they need. As a Product Developer for banks, I sometimes get so caught up on how to make products run that I lose sight of how the work I do impacts the community. Helping one woman discover Prove-ID to secure a loan and provide for her family inspired me. I want to continue being more involved in my community to help others who may not be literate learn how to prove their identities so they can better support their families.
I’m a Business Systems Specialist on Experian’s Information Technology Services team. While the work I do is largely behind the scenes, the data I process helps power advertising campaigns, provide accurate credit score reports to consumers and enable people who might not otherwise have access to credit to achieve their goals. The most valuable thing I can provide the businesses Experian works with is accurate data, because data is the backbone of a business. I run systems and support software that helps process the data for Experian’s products and services, and work to ensure businesses have access to the most accurate data sets. Businesses from across different sectors send us data about their consumers—like if an individual paid rent or a bill on time — that we update into our databases so that when that person applies for a loan or to rent an apartment, our data is timely and accurately reflects that individual’s true credit score. Accuracy can be the difference between a person getting a lease or having to look elsewhere. The data I help process and service is used for other business purposes as well, like advertising campaigns. Marketers will send us a list of the demographics they’re looking to reach. I help aggregate and compare those lists of demographics against the data we already have on hand to provide that client with an accurate list of addresses. Armed with that timely, accurate information, those businesses can reach their target audience and increase revenue for that quarter – and consumers benefit from more targeted messaging from companies they care about. I joined Experian more than 20 years ago, and have seen it evolve and grow from essentially a traditional credit bureau to a global information services enterprise. For me, the extent to which we as a company can provide services that empower consumers to succeed on their life’s journey has always been the end deliverable. Read more #ExperianStories from our colleagues around the world.