World
News about Experian from all over the globe:
The world in 2018 is defined by data. Vast quantities of information flow through our lives like threads across an elaborate tapestry. On a micro level, these threads bind the business world together. But they also come together to weave a picture of the economy that is colourful, detailed, and uniquely fascinating. At Experian, we process more than 1.5 billion records per year, making us specialists in the processing and understanding of this data - and in making sure it is used for the benefit of consumers and businesses. To share our unique perspective, we’ve created our first ever Spending Power Index. The index looks at the UK’s income and spending habits, including both a detailed view of the present, and insight into longer term trends and the nation’s changing preferences. Giving businesses the bigger picture Stepping back from day-to-day business to look at the whole economy is a chance to identify new opportunities and work out the best ways of adapting to new challenges. The insights we’re providing through the Spending Power Index are designed to fuel that process by offering a view of existing and emerging trends across all demographic segments of the UK economy. What is the Spending Power Index? We’ve defined ‘Spending Power’ as a combination of key factors: Average income growth over time Levels of spending for one demographic group when compared to another Levels of spending as a proportion of incomes These combined factors reveal a wealth of hidden information about income and spending. All these insights have been drawn from Experian’s modelled data using secondary sources such as our ‘Financial Strategy Segmentation’ (FSS) tool. The data for this comes from a range of publicly and commercially available sources, such as the edited Electoral Roll, the UK Census and permission-based market research data taken, for example, from the lifestyle questionnaires many of us complete. New insights and confirming market trends Some of the insights revealed by the index have been surprising, while others fit into social trends that are already well understood. We found some areas of significant shift, such as the movement away from owning possessions and towards spending on life experiences. But we also confirmed some new and fascinating trends such as the emergence of Generation X’s forty somethings as the biggest earners and spenders in the UK economy. Find out more by reading the full Spending Power Index report here.
Experian MicroAnalytics has surpassed a record 5 billion credit offers, demonstrating our commitment to helping people in emerging markets create credit profiles and improve financial well-being. In emerging markets around the world, people have limited access to financial products, especially credit. At Experian MicroAnalytics we’ve developed a sustainable solution to provide billions of people with access to financial products, easily accessed through their mobile phones, unlocking the power of alternative data in countries across Latin America, Asia, Africa and beyond. “We’re thrilled to have extended over five billion credit offers,” said Elio Vitucci, CEO of Experian MicroAnalytics. “2017 was our fastest-growing year, and we are now extending over 270 million credit offers every month. Our goal is to help people in emerging markets build a strong financial identity. We build financial identities using mobile phone behavioral data, one of the richest sources of customer insight, and unlock an initial set of financial products. As customers use these products, they strengthen their financial identities and obtain access to an increasingly wider set of financial services.” While only a minority of people in emerging markets have access to banking services and even fewer have access to credit services, the vast majority have a mobile phone, most on a prepaid plan. Experian MicroAnalytics partners with mobile network operators around the world, using mobile behavioral data to start creating initial financial identities for people. With these financial identities, customers can start to gain access to simple but useful financial products, such as airtime credit. As customers continue to take and repay their borrowed airtime credits successfully, they strengthen their financial identities and progressively unlock a wider, more complete set of financial services. This creates a virtuous circle, where in time customers graduate to a full set of financial products. “We help consumers in emerging markets to build a financial identity, unlocking access to financial products such as loans, credit cards, insurance and more, all available via their mobile devices,” Vitucci added. “These financial products fuel economic development, stimulate growth and have a positive impact on the quality of life for billions of people.”
Today we announced our results for the last financial year. The results and the business growth are strong, and a reflection of the actions we have taken to build our success. While we posted some very good results – 8% total revenue growth for the year is great – but it is the people, the strategy and the execution behind those numbers that we are most proud of. In recent years, we intentionally set a course that started with a brand promise to power new opportunities for our clients while creating a better tomorrow for consumers and society. In the last year, towards our quest to achieve that promise, we have made significant progress: We have invested in technologies like API and analytical sandboxes to help us better serve clients worldwide and effectively and safely manage the data and decisioning tools that help our clients succeed; We have made key investments to add new sources of data – including the acquisition of Clarity Services in North America and our continued strategy to look at mobile phone data in EMEA and Asia Pacific to help those who are excluded from the traditional financial system; We have introduced new products for consumers that help them better protect their identities and help them effectively manage their financial profile and credit standings to help ensure financial access in today’s credit economy; and We have created innovations such as our “Text for Credit” offering, which not only makes it easier for consumers to have a seamless credit application process, but it also enables lenders to have a more productive relationship with consumers who are looking for loans. Those are just some of the efforts that underscore our financial results. But more important than the positive results is the fact that we achieved this growth while also staying true to our brand promise. We are doing great things around the world – for businesses, for people and for society. The possibilities and potential of data have never been more exciting or life-enhancing – and our belief remains that data is central to how we all live and has the potential to transform all our lives for the better. The work our nearly 17,000 employees are doing – and have been doing – is indeed transformational. And that is one result for which we couldn’t be prouder.
Promoting a better understanding about how the credit economy works and improving financial awareness, so that people can take control of their financial situation with positive, proactive decisions, is absolutely fundamental to our business strategy. This is encapsulated through our financial education programmes. In partnership with Young Enterprise, we have created 28 Centres of Excellence for schools to support children’s financial education. And through Experian’s Values, Money & Me, we have created the UK’s first free online teaching resource to help children develop their financial knowledge and abilities. Credit Awareness Week is, then, a natural place for us to continue that focus. And to take that conversation more widely, to our industry partners, for us all to consider how we might find better ways of working, and drive better outcomes for our customers. There’s no doubt that we are living through a period of significant financial uncertainty. At times like this it is important that consumers are aware of all the options available to them from a financial perspective. And we believe your credit score is one of the first things you should look at. It’s perhaps surprising then that our annual Credit Awareness Week consumer survey found that public awareness of credit and how it can be used to help with day to day challenges still remains relatively low, despite some signs of improvement – potentially driven by the widespread availability of free score services. The percentage of people who said they know their current credit score went up from 22% to 26%, while 47% have ever checked their credit report, up from 45% last year. However, there is still much misunderstanding coming through. 39% of those surveyed wrongly believe their own credit score can be affected by a previous resident of their address having a poor credit score, while 14% think, incorrectly, that checking their own credit report and score has an impact on their credit rating. More than a quarter (26%) are also wrong to believe having a high income can affect their score, while 14% are incorrect to think checking their own score has an impact. The number of people who believe that the system needs to provide clearer explanation about how the decision was made when credit is refused has also increased. What the results of our poll tell me is that more needs to be done in promoting a better understanding about all the options available, like the existence of eligibility and comparison services which are designed to help empower people shop around for better deals and, where credit is concerned, avoid damaging their score while they do so. So there is work to do in building a better understanding about how credit works, which is something we are committed to and that’s why we are supporting this campaign. To help, Experian and Credit Strategy have launched an improved ‘credit refusal pathfinder’ [add hyperlink] tool, to help guide people who apply for credit and get turned down. I’d encourage everyone, even those of us who think we know this business inside out, to take a look at the tool. And, in the spirit of building greater trust and transparency with our customers, let’s take this opportunity to have a think about what we in the industry can do to make things clearer for people. Helping them understand how lending decisions are made and empowering them to take control of their financial situation and make better, sustainable choices through affordable access to finance.
Before you read this blog post, I thought providing you with an introduction to who I am might be helpful. My name is Jennifer Schulz and I am a 46-year-old white American woman whose DNA indicates my ancestors originated mostly from Europe with a very small trace from East Asia. I am married to Bob Roback, my partner in life. I am the mother of two incredibly active boys, ages 8 and 5. I am the bonus mom to our daughter (20) and son (soon to be 18). I am a sister, daughter and friend. I am also the very proud leader of Experian’s Health, Auto and Targeting businesses in North America. As #metoo swept social and mainstream media and drove hundreds of thoughtful articles on a whole host of gender related topics, I found myself reflecting and feeling genuinely grateful to be at Experian. During my interview and onboarding process four years ago, I came to realize that Experian had a great culture full of smart and genuinely caring people. It was – and still is – a culture characterized by a strong client orientation and financial performance, and genuinely wanting to do the right thing. It continues to be an organization with a determined focus on improving its diversity at the top. Our leadership knows that to stay innovative and attract and retain talent we have to make diversity a priority. As the global sponsor of Women in Experian and a member of the North American leadership team, I have had the honor of witnessing the progress the company has made as an organization over the last couple of years. We’ve invested time and resources to build out programs, change policies and make our organization even more inclusive. We’ve made progress around the globe: In the last year, we’ve added two incredibly strong women to our Board of Directors – Caroline Donahue and Ruba Borno. They join Deirdre Mahlan who has been on the Board since 2012. With these additions, women will comprise 27% of our Board. We continue to develop a strong proportion of women through our leadership programs globally. This is feeding our future talent pipeline. We launched Women in Experian in 2016 and now have active programs in every region supporting a range of initiatives including enhancing our parental leave and flexible work policies, creating mentorship and sponsorship programs, examining and addressing pay disparity and requiring our recruiters to present diverse candidate pools. Experian was one of 28 companies globally recognized on the Anita Borg Leadership Index of organizations that show strong representation and development of women technologists. We have continued to develop and adjust family friendly policies in a number of countries, aimed at giving given greater flexibility and choice for working parents and families. Although we celebrate progress, we know that we have more work to do. We need to increase the diversity in our senior leadership ranks. We need to increase the number of women in technology. And, most importantly, we need to continue to keep diversity and inclusion a priority. The other night while I was driving my son to his soccer practice, I received a work call. He sat quietly while I talked for a few minutes, well accustomed to my attempts to balance work and life. When I hung up the call, my son asked me, “What is International Women’s Day?” I answered by telling him (reminder he’s 8) that historically women haven’t always been treated fairly and that this day is about honoring and recognizing all the men and women who are working to make things fairer. He then asked if it was my full-time job. Suppressing a laugh, I said no, it’s not my full-time job but it’s an important part of it. He asked, “Why?” Why? I looked in the rear-view mirror and said, “Because I want to try to make the world better for you, your brothers and your sister.” I believe at Experian we are doing just that … making progress. Our momentum is building and tomorrow will be better. #PressforProgress
Having a diverse workforce is vital to help us innovate and deliver on the needs of our increasingly diverse clients and consumers. Over the years, we've made some great progress, but there's so much more we can do and it's going to take the collective effort of all of us to continue to move the needle. That's why we're gearing up to celebrate International Women's Day (IWD). It's a day celebrated in many countries around the world to recognize the achievements of women and drive equality among men and women. At Experian, IWD activities are extending throughout the month of March. Have a look at what's going on around the world as Experian celebrates this important day: Asia Pacific The Asia Pacific region is hosting a range of activities across our offices in March, which will include round-table and speaker events as well as an opportunity to network and pledge their support for IWD. EMEA and UK&I EMEA and UK&I are joining together for IWD to support and celebrate diversity and inclusion. The week started with a video of employees from both regions reflecting on what diverse teams bring to our business. Employees will also be invited to a variety of events to engage and network with inspirational women and hear stories from our leaders on what diversity means to them personally. Latin America Throughout the month of March, Latin America has been running a campaign to share stories of achievements in their region and raise awareness about breast cancer prevention and other diseases more common in women. On IWD, there will be a panel of women leaders who will address issues such as the social inclusion of women in the region, women's participation in the labor market, Experian's commitment to female leadership and the importance of a work/life In Brazil, IWD is kicking off with a presentation by members of the United Nations to present their 50-50 Gender Equality program (which aims to eliminate gender inequalities by 2030) and how they are working with companies around the world to achieve this vision. Employees will have an opportunity to hear from leaders in our business about diversity and inclusion plans for the region, and listen to a panel of external speakers discuss diversity challenges and career development. North America Our employees in North America will be kicking off the week with celebrations across their ITS’ 13 offices in the region. Each office will have daily activities throughout the week, and all employees – including virtual and those based in smaller offices – will be invited to attend webinars focused on Diversity and Inclusion topics. On IWD, there will be panel discussions with senior leaders who will speak on various career development topics. To close out the week, there will be a special Book Club discussion on March 9. We will continue to update this blog post all week with pictures and other ways we’re celebrating IWD. Bookmark this page and come back.
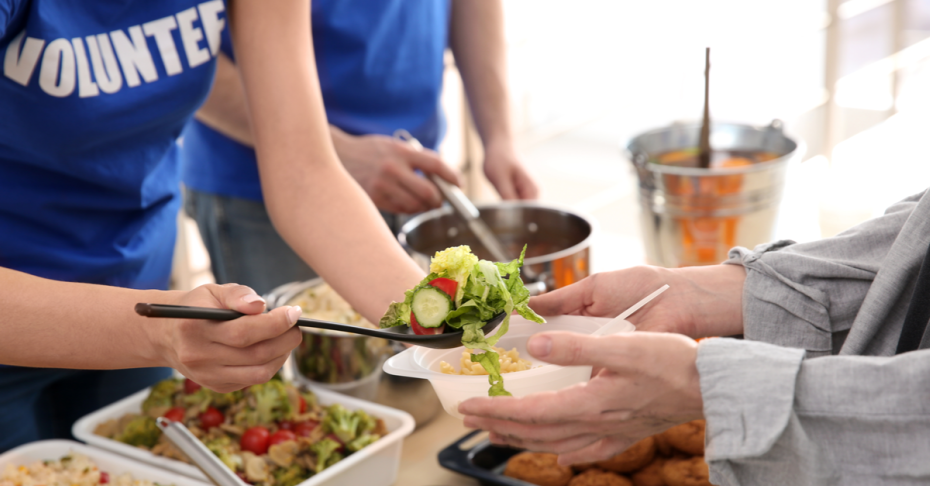
I feel that part of Experian’s responsibility as a global information services company is to build and bolster community involvement initiatives that help others. I’m currently a manager of our Fraud Resolution Team and Credit Educator Department in Allen, Texas, but I also have the honor of managing all outreach programs for our branch, bringing together Experian employees to give back to the community. Taking on a volunteer project on top of regular work can be daunting. As the point person for my office’s volunteerism, I’m in charge of communications about upcoming events and drumming up interest and excitement among employees, be it through flyers, silly videos, emails or even free t-shirts. I know a lot of my fellow employees, but I don’t know everyone, so spreading the word isn’t always easy. Despite these challenges, I continue doing this important work because I care about the impact Experian makes in its local communities. My first volunteer experience with Experian was working alongside Stop Hunger Now – an international hunger relief nonprofit – several years ago. I was amazed at the impact we had. Shortly thereafter, I also participated in a canned food drive, rallying Experian employees to visit the Texas Food Bank. After these two chaotic, inspirational, behind-the-scenes experiences, my interest was permanently piqued in on-site volunteer days within the Allen community. Since then, I’ve organized volunteer days with many other nonprofit programs. The amount of organization and work that goes into each volunteer day is much more than you might think. For every Stop Hunger Now event, we package 10,000 meals for those in need, which requires about 100 volunteers dedicating their time. When we worked with Habitat for Humanity, a nonprofit organization devoted to building homes for those who need them, our first two scheduled events were rained out – and it never rains in Texas! I was worried that no one would show up the third time, when we had to reschedule for 7 a.m. on a Saturday. Luckily, every single volunteer spot was filled. We got to meet the family we were building a house for, and we all signed a piece of wood from the house for them. Their gratitude made all the frustration and extra work worth it. It takes a village to get some of these events off the ground, but I have a strong support structure at Experian. And learning to empathize with people through volunteering helps me in my day-to-day work. People who are dealing with fraud can be very emotional, and fraud is unexpected by nature. My volunteering experience has equipped me with the skills needed to empathize with others better and think on my feet.
This morning on my way into the office, I made my usual stop for coffee. Just like every other day, the barista greeted me by name and my usual drink was being made before I got to the counter. Doesn’t it feel nice when you’re recognized? The same holds true when we interact online. We want to be recognized when we transact online, because recognition helps to stimulate trust. And trust is what makes all of us feel safe and protected. New research from our Global Fraud and Identity Report demonstrates that customer recognition also plays a large role in indicators of fraud. Most of the 500 business executives in 11 countries that we interviewed across the globe, said that if they were certain about a customer’s identity, the need for fraud risk mitigation would be reduced. One of the trickiest components to fraud detection, is finding the fine line between turning away good customers and letting the fraudsters slip through. Our global research revealed that most businesses tend to demonstrate suspicion when it comes to preventing fraud, following a route of detection rather than permission or trust. In fact, 71 percent of businesses know that they deny more transactions than they should. The end result isn’t just a loss of sales, but it also may very likely damage the lifetime value of that customer. Business leaders agree that if they were more precise in identifying the customer and avoiding denial of real transactions, they would see an increase in revenue. In addition, the report confirmed what we all already know – as consumers, we expect the companies we do business with to protect us. We surveyed 5,500 people in 11 countries, and many said they equate visual signs of security and the barriers they encounter when accessing their accounts to mean the transaction is more secure. Nearly 7 out of every 10 people like the security protocols when they transact online because it makes them feel protected. As customers, we want to believe that banks and retailers are doing everything they can to protect and secure our online transactions. Our study also found that 72 percent of businesses say fraud is a growing concern, with online fraud continuing to be a top concern across the globe. One of out every 10 businesses are experiencing the same or more fraudulent losses online compared to a year ago. Fraud is always evolving and fraudsters are becoming more resourceful than ever before. And while there is no silver bullet, and good modern fraud detection requires multiple fraud detection strategies, better customer recognition could make an immediate difference. Simply put, the better you recognize the customer, the better you can recognize fraud. Get a copy of the complete Global Fraud and Identity Report
Patients ideally should know what they’re going to owe when they show up for an appointment – the last thing they need is a big financial surprise to add to the stress of their visit. Similarly, doctors, nurses, hospitals and all healthcare providers help people to stay healthy day in and day out. Providers should be able to go to sleep at night knowing that they’ll be fairly compensated for the work that they do. However, making that happen isn’t easy. Behind the scenes, contracts, benefits and eligibility between medical groups, hospitals and insurance payers are fairly nuanced and complex. Clients benefit when it comes to how much a patient owes a hospital or medical group after treatment, rough estimates aren’t ideal – perfection is difficult/ create problems and issues. Billing must have pinpoint accuracy and add nuance based on unique contract terms that all medical groups and hospitals sign with their employers and payers. The details can actually be quite difficult to keep straight, and there is an extensive amount of variation in each contract’s rules. Experian Health works to make payment transparency the norm, so that patients know what to expect and healthcare providers are paid fairly, accurately and in a timely fashion. I began working for Experian in 2004 but my interest in product development and research eventually led me to Experian Health. My team of more than 100 Experian employees painstakingly reviews contracts, patient eligibility, benefits information and historical claims to generate an accurate fee estimate for each patient’s medical visit. Nuance/aiding are helping to work toward this. We utilize up-to-date technology that organizes all the information we find in an extensive database and review the claims on behalf of both our medical group clients and patients. The biggest challenge for me and my team is anticipating both patients’ and hospitals’ future needs and innovation in the field. Any time healthcare policies are changed or reimbursement guidelines shift, it affects our clients and requires nimble thinking on our part. How do we ensure that our technology is as modern as possible and our team members stay current on the latest trends and news? I’m looking forward to seeing how we continue adapting in the future.