 By Ben Luthi
 Edited by Michelle TipswordBy Ben LuthiEdited by Michelle Tipsword

You should generally avoid adding a consumer statement to your credit report unless you're dealing with identity theft or a failed dispute that requires human context. A statement allows you to explain your side of the story, but it can't remove the entry, and it won't have any impact on your credit score.
Here's what a consumer statement does, when it's worth adding and how to add or remove one.
A consumer statement is a short written explanation you attach to your credit report to give context for information listed in your file. Anyone who pulls your report can read it, including lenders reviewing a new application.
Under the Fair Credit Reporting Act, you have the right to file a brief statement when a dispute doesn't resolve the way you wanted. Credit bureaus can limit your statement to 100 words.
Your statement will sit alongside the tradeline (account) listed on your credit report rather than replacing it. While future lenders can review your statement, they're not obligated to change how they evaluate the negative item it's attached to.
There are two kinds of statements you can request be added to your credit report:
Account-specific statement: This statement is linked to a single account in your credit history. If a delinquency was the result of extended unemployment, for example, you can attach a statement to that account explaining the circumstances. It comes off your report at the same time the account does. Account-specific statements come in two forms:
A consumer statement can add useful context to your credit report, but there are some clear limits to what it can do. It won't change the entry itself or affect your credit score.
That said, here are some situations where it can be helpful.
You have the right to dispute credit report information you deem to be inaccurate, incomplete or unverifiable. But if the credit bureau can verify the information as accurate, it'll stay put. In this scenario, adding a statement of dispute tells future lenders that you disagree with the status of the tradeline and why.
If you're a victim of identity theft, you may add a general consumer statement to let prospective lenders know the situation and that you're taking steps to clear it up. On top of that, you'll want to take other steps, such as filing an identity theft report with the Federal Trade Commission, adding a fraud alert to your credit file and possibly even freezing your credit reports—steps you have the right to take.
Learn more: How to Report Identity Theft
If you missed payments because of a natural disaster, extended unemployment or a medical emergency, a short statement explaining the situation could help your case. This is especially true if you can show that you managed your credit responsibly before and after the event and can provide documentation.
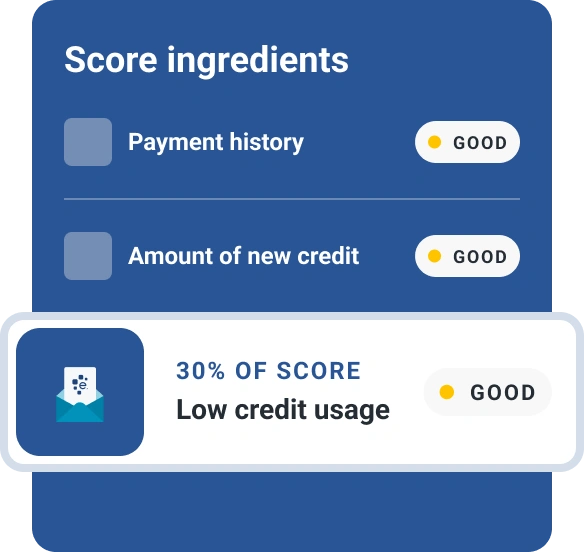
Better understand your creditworthiness with an overview of your total debt.
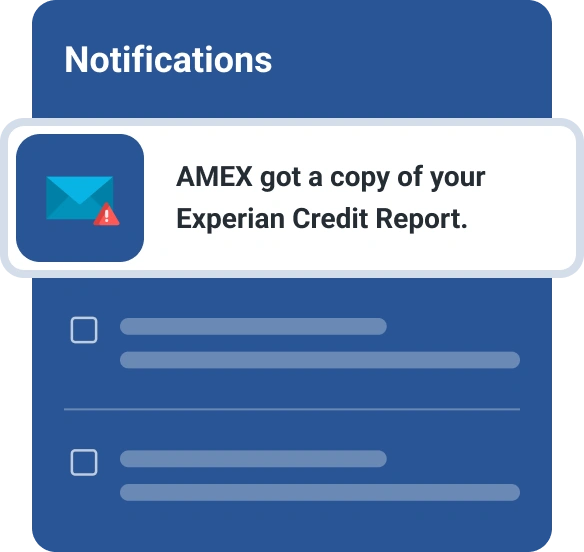
Check for any changes with customized alerts and an updated report daily.
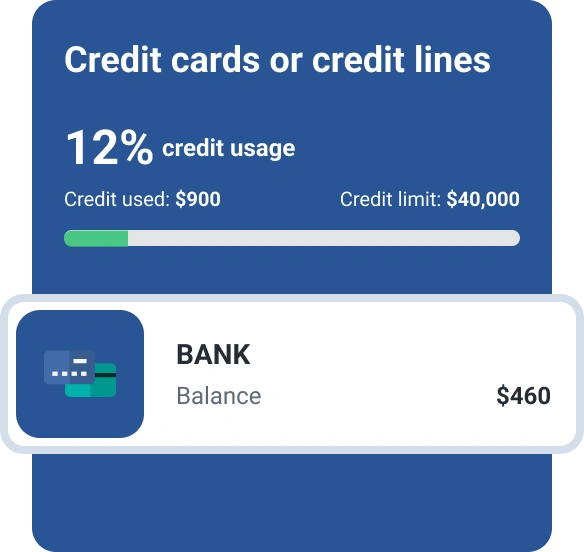
Reviewing your credit report can help you spot potential fraud or identity theft.
Each of the three credit bureaus maintains its own file, so you'll need to make three separate requests when adding or revising a consumer statement.
With Experian, a statement of dispute goes in through the online Dispute Center. Sign in to your account, choose the item in dispute and select Add a Statement from the menu of dispute reasons. TransUnion and Equifax each handle their own requests, so you'll need to contact them directly.
You can also mail a signed written request to each bureau's dispute address. Include the exact wording you want on your report, along with your full name, date of birth, Social Security number and current address, plus any other address you've lived at in the past two years. You'll also need to enclose copies of a government-issued ID and a bill or bank statement showing your current address.
You can mail your request to the following addresses:
You can edit or remove a consumer statement on your credit report at any time.
A consumer statement can provide important context to a negative item on your credit reports, especially when a lender uses a manual underwriting process. On top of that, it's important to take other steps to build and maintain a good credit history.
One way to do that is by regularly monitoring your credit. Experian's free credit monitoring tracks your Experian credit report and FICO® ScoreΘ, with alerts when something in your file changes.
Stay up to date with your latest credit information—and get your FICO® Score for free.
Get your free reportNo credit card required

Ben Luthi