Pros and Cons of Home Improvement Loans

Quick Answer
- Home improvement loans can help you pay for home repairs and improvements.
- Depending on the project, these loans may not be the best fit.
- Pros include fast funding, no collateral needed and fixed payments, while cons include added debt, hidden fees and potential damage to your credit.
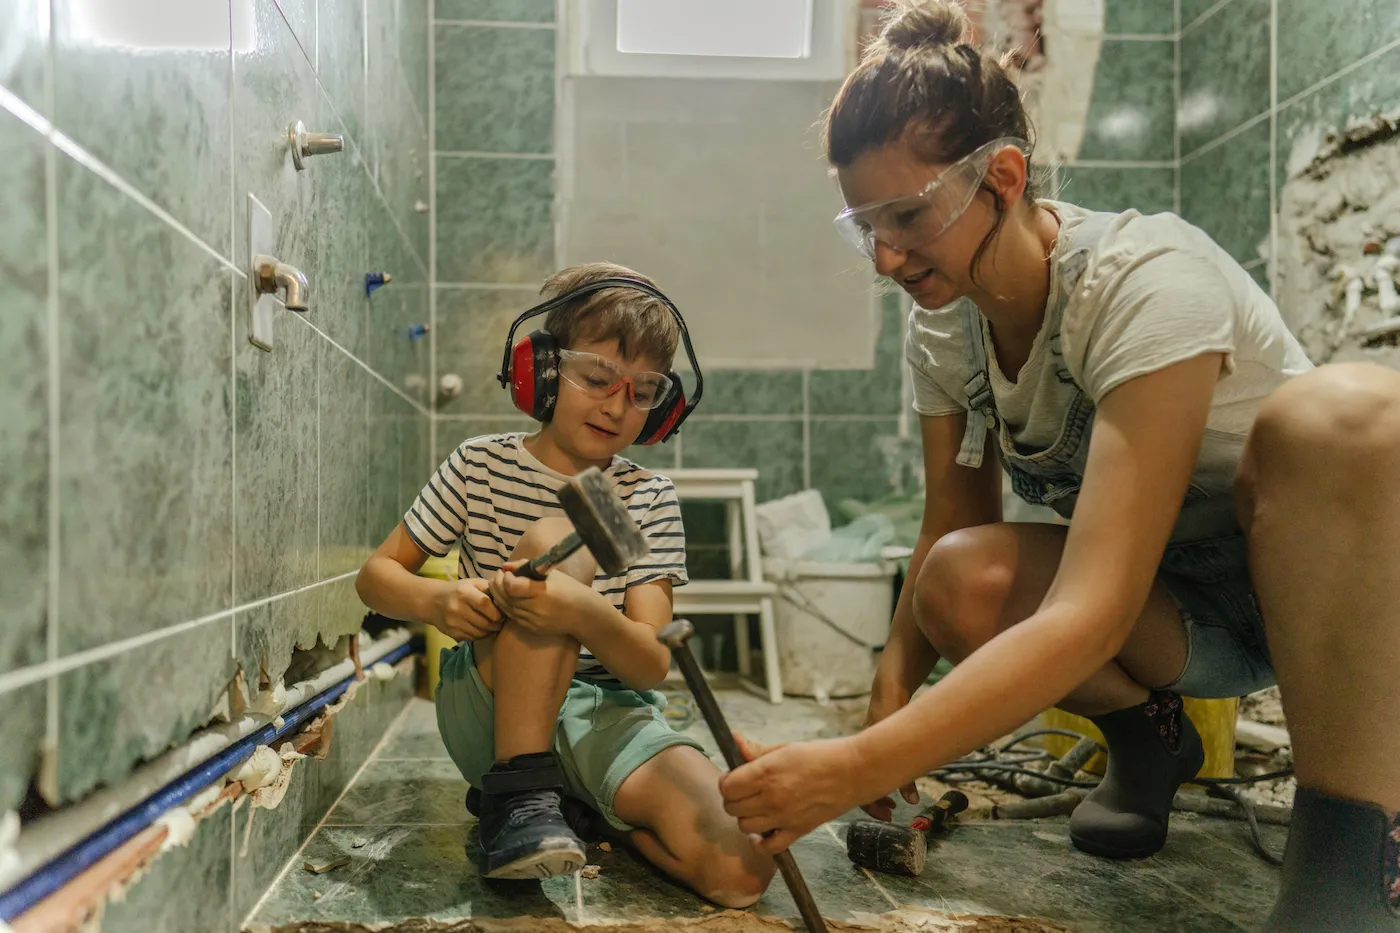
Home improvement loans provide fast, collateral-free funding to pay for repairs or renovations. But they tend to come with higher interest rates than other types of financing options, such as home equity loans, and you'll typically need good credit to qualify for the best terms.
Weighing out the pros and cons can help you decide if a home improvement loan makes the most sense for your situation.
What Is a Home Improvement Loan?
A home improvement loan is a type of personal loan that lets you borrow money in a lump sum to pay for home repairs or renovations. Collateral isn't typically required, and you'll repay the loan over a fixed term.
Once the loan is funded, you can generally choose to use the money in any way you want. This could mean paying for home improvements, but you can also use some or all of the funds to pay off debt or cover other expenses.
Pros of Home Improvement Loans
When you need to make repairs or renovations, home improvement loans can offer several advantages, including:
Pros
-
No collateral needed: Most home improvement loans are unsecured personal loans. This means lenders won't require you to put up collateral to get approved.
-
No home equity required: Unsecured loans don't require you to borrow against the equity in your home, so you don't need to have equity built up. And you won't risk losing your house if you default on the loan.
-
Potentially large loan amounts: Depending on the lender you choose, as well as factors such as your credit and income, you may be able to borrow up to $100,000. And you don't have to use all of the funds on repairs.
-
Fast funding: After approval, the money is typically available in your bank account within a week; some online lenders can deposit the funds as soon as the same day.
-
Predictable payments: Home improvement loans are generally repaid in fixed monthly payments over a set term, typically one to seven years.
Compare personal loan rates
Find APRs from 5.96% to 35.99% and flexible terms of 24 to 120 months. Loan amounts range from $1,000 up to $250,000, with funding available the same day or up to 3 days.
Offers from our partners


View all of our Best Personal Loans for 2026 to see what you’re likely to qualify for, and the rates and terms you might get.
Cons of Home Improvement Loans
Home improvement loans may come with several downsides, including:
Cons
-
Higher interest rates and shorter loan terms: Personal loans may have higher interest rates compared to other financing options for home improvement costs, such as home equity loans. Repayment terms also tend to be shorter than other types of loans that let you borrow against your home's equity.
-
Fees: Some lenders charge an origination fee ranging from 1% to over 10% of the loan. Other fees you might encounter include application fees, prepayment penalties, late or returned payment fees, and payment processing fees.
-
Credit score requirements: While there's no universal minimum credit score requirement, you'll typically need good credit scores or better to qualify for the best loan terms and lowest rates.
-
Increased debt: A home improvement loan is a form of debt that could leave you overleveraged, depending on your financial situation. So it's important to consider your budget carefully before taking out a loan.
-
Potential credit damage: The loan will raise your overall debt, which could lower your credit score. And late or missed loan payments can significantly damage your credit score and remain on your credit report for seven years.
Is It a Good Idea to Get a Home Improvement Loan?
Home improvement loans can be a fast and low-risk way to finance home improvements. But they may not always be the right choice for your situation.
When a Home Improvement Loan Could Be a Good Idea
Here's a look at some common situations where a home improvement loan could be a good idea.
- You don't want to use collateral. Since most home improvement loans are unsecured, there's no risk of losing your personal assets if you default on the loan.
- You need to make urgent repairs. Fast funding can help you get the cash you need to pay for emergency repairs quickly.
- You want to boost your property value. Using the loan funds to make home improvements can potentially increase your home's value significantly, depending on the type of renovation or repairs.
- You don't have enough home equity. If you're a new homeowner or haven't built up enough equity to borrow against, an unsecured home improvement loan might be a good choice.
- You want to stick to a budget. Borrowing only what you need and getting fixed monthly payments can help you avoid taking on extra debt and keep your budget on track.
When a Home Improvement Loan May Not Be a Good Idea
Here's a look at some common situations where a home improvement loan might not be the best fit.
- You have bad credit or existing debt. If your credit is less than perfect or you have a high debt-to-income ratio, you might not get a high enough loan amount to finance your project. Or, the interest rate rate may be too high to make borrowing worthwhile.
- You plan to move soon. Taking out a home improvement loan when you plan to sell your home in the near future could leave you stuck paying off the cost of repairs long after you move.
- You're not sure how much you need to borrow. More flexible financing options might be a better fit if renovations are ongoing and you want to be able to access more money without having to apply for a new loan.
- You've built significant home equity. Other financing options that let you borrow against the equity in your home may offer higher limits, longer repayment terms and lower interest rates.
- Your renovation won't add enough property value. Improvements made to your home don't always increase property value, or they may not add enough value to justify the cost of taking out a loan.
Alternatives to Home Improvement Loans
If you are worried you won't qualify for a home loan due to your credit or other factors, or prefer to tap into your home's equity, it might be worth considering these alternatives.
- Savings: Tapping your savings account is the cheapest way to cover home improvements. You can also set up a sinking fund to save for home improvements. While creating a sinking fund takes time, you won't go into debt.
- Home equity loan: A home equity loan allows you to borrow against the equity in your home and is often a popular choice to cover remodeling costs. You'll receive your funds in one lump-sum payment and repay the amount in fixed monthly payments over the loan's term, usually five to 30 years.
- Home equity line of credit: A home equity line of credit (HELOC) is a line of credit that allows you to access a portion of the equity in your home, using the home as collateral. Most lenders let you borrow up to 85% of your home's equity. You can draw funds over a set period of time, generally 10 years, without needing to apply for another loan, and the repayment period typically lasts 20 years. A HELOC offers flexibility for ongoing renovations or projects that go over budget.
- Cash-out refinance: With a cash-out refinance, you'll take out a new, larger mortgage loan on your home. Your previous mortgage is paid off using the new loan, and you get the excess cash, which you can use to pay for home improvements or home repairs.
- FHA 203(k) loan: An FHA 203(k) loan is a government-backed rehabilitation loan that allows you to finance the repair and rehabilitation of a single-family home. These loans are intended for fixer-upper homes and have strict lender requirements.
- Contractor financing: Sometimes a contractor, like a roofer or window replacement company, will offer a loan to help you pay for repairs. Loans are generally through a bank they work with, and like with other types of loans, you'll repay the loan in installments with interest.
- 0% introductory APR credit card: With good credit, you might qualify for an 0% intro APR credit card, which you can avoid paying interest for up to 21 months. Just keep in mind that any balance remaining after the introductory period ends will accrue interest at the card issuer's standard rate, which could be significantly higher.
Tip: You might get a tax deduction for the interest you pay on a home equity loan, HELOC or cash-out refinance if you use the money to substantially improve your home rather than do basic repairs or maintenance.
The Bottom Line
Home improvement loans can help make your home a nicer place to live and improve your property value when it comes time to sell. However, it's important to consider the benefits and drawbacks—and shop around to compare different options—before you apply.
Experian offers a loan comparison platform that can help by matching you with loan offers from multiple partner lenders based on your credit profile. Plus, Experian's No Ding Decline™ feature within the loan comparison marketplace can help you find the best offers with more confidence. It allows you to apply for certain personal loans using only a soft credit pull, so your credit scores won't drop if you're not initially approved.
⊛Applying for loans labeled No Ding Decline™ won't hurt your credit scores if you aren't initially approved. Initial approval and/or acceptance of this loan may result in a hard inquiry, even if you're unable to pass final verifications, which may impact your credit scores.
Need a loan?
Whether you're shopping for a car or facing a last-minute expense, compare loan offers matched to your credit profile.
Start now for free
About the author

Sarah Archambault
Sarah Archambault is a personal finance writer and editor who enjoys helping others figure out how to make smart financial decisions. She’s an expert in credit education, auto finance, banking, personal loans, insurance and credit cards.
Read more from Sarah