How to Maintain a Good Credit Score

Quick Answer
- Maintain a good credit score by keeping up the same habits that helped you achieve good credit initially.
- Prioritize paying all bills on time, lowering your credit utilization, and sustaining a long credit history.
To maintain a good credit score, focus on paying your bills on time, limiting your credit utilization and keeping your oldest credit cards open, when possible. Achieving a good credit score is a big milestone, but keeping up positive credit habits is just as important. Making even one payment late by 30 days or more can dramatically lower your credit score, especially once it is in the good or excellent range.
Take these steps to keep your good credit going strong.
What Is a Good Credit Score?
A good credit score is 670 to 739 according to the FICO® ScoreΘ model, and 661 to 780 in the VantageScore® credit score model. The closer yours is to the maximum score of 850, the more likely you are to receive the lowest interest rates and most advantageous terms on credit products.
To build credit, you'll need to demonstrate that you can responsibly manage debt. That means developing habits that correspond to the most important credit scoring factors:
- Payment history (35% of your FICO® Score): Make every payment on time on credit cards and loans.
- Amounts owed (30%): Minimize amounts owed on debt accounts, particularly credit cards.
- Length of credit history (15%): Maintain a long history of managing credit accounts.
- Credit mix (10%): Manage range of account types.
- New credit (10%): Apply for new credit infrequently.
6 Ways to Maintain a Good Credit Score
The same behaviors that helped you develop good credit will ensure you sustain it long term. Take these steps to keep your credit thriving.
1. Pay All Your Bills on Time
Debt payment history has the biggest influence on credit scores. If your score is in the good or excellent range, you likely already have a plan in place to ensure your bills always reach your credit card issuer or lender on time. To be safe, set up autopay so your payments come directly out of your checking account before the due date.
It's also important to pay all utility bills by the deadline. If you're significantly behind on payments, utility companies may charge off your account or send it to collections—both of which will negatively affect your credit.
Get your FICO® ScoreΘ for free
Sign up and get instant online access to your FICO® Score for free.
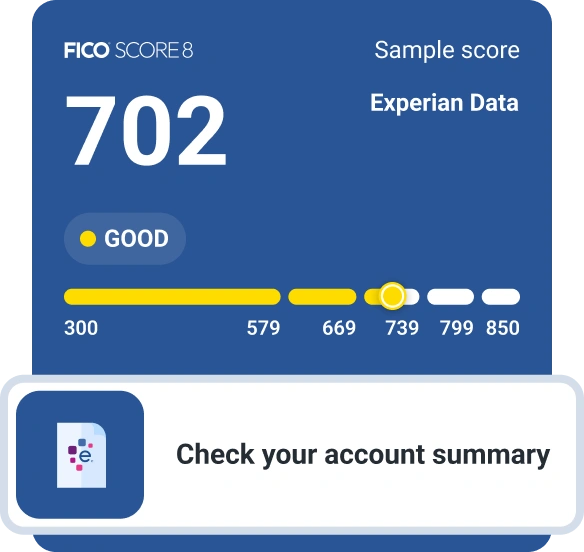
Checking your own credit won’t lower your credit scores.
View specific factors that are affecting your score and how to improve it.
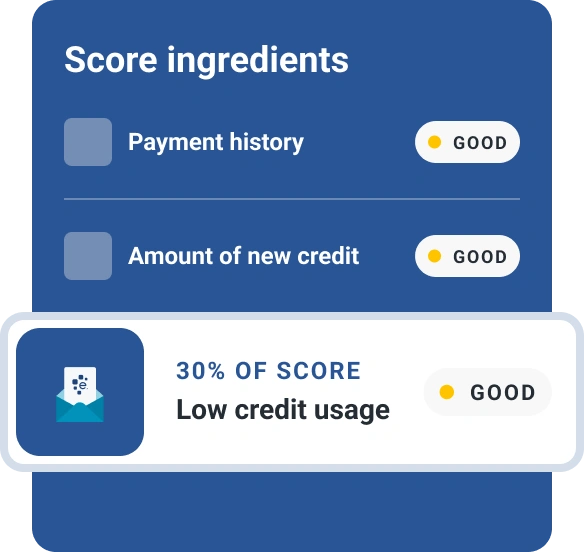
2. Keep Your Credit Utilization Low
The second most critical factor in your credit score is the amount of debt you carry. Credit utilization is a big contributor to this category, and it's the proportion of available credit you're using on each credit card (and other types of revolving credit accounts).
Your credit score may decline more precipitously once credit utilization hits 30%. But consumers with the best credit scores typically have credit utilization rates under 10%. That means that if your credit card's credit limit is $3,000, plan to carry a balance under $300. When your credit score is already strong, aim for the lowest credit utilization rate possible while still using your credit cards regularly.
3. Keep Older Credit Accounts Open When It Makes Sense
Credit scoring algorithms reward long credit histories. Instead of closing old credit card accounts you no longer use, keep them open to show that you can manage credit well over an extended period. You can use the card to cover one small monthly bill, for example, such as a streaming service or a utility payment, and make sure the account is set to autopay.
An additional benefit of keeping credit card accounts open is that you'll have access to more available credit, potentially lowering your overall credit utilization and helping your credit. There are circumstances when it can make sense to cancel an old credit card, though. If it comes with an annual fee that you're unable to afford, or you're concerned the available credit might entice you to go into debt, the forfeited credit history could be worth it.
4. Apply for New Credit Only When You Need It
Submitting an application for a credit card, credit limit increase or loan—either as the main borrower or as a cosigner—means the creditor will request to view your credit history. That will add a hard inquiry to your credit report, which can lower your credit score by a few points temporarily.
Avoid multiple hard inquiries for different credit types in a short period. Credit scoring models and lenders may conclude that you're seeking credit because you can't manage the accounts you already have.
5. Sustain a Healthy Credit Mix
Credit mix is the variety of credit accounts that you own. In general, your credit score will benefit from having a mix of credit types in your name. These can include revolving credit, such as credit cards and home equity lines of credit, and installment credit, like mortgages and car loans.
For most consumers, credit mix will grow naturally as they seek out financing at different stages in their lives. Credit mix only makes up 10% of your credit score, so prioritize limiting debt and making timely payments on existing accounts over seeking out new types of credit just to boost your score.
6. Check Your Credit Reports and Credit Scores
Regularly monitor your credit report, since your credit scores are calculated using the information from your report. Ensure that your personal information is accurate and that all the accounts listed belong to you. If you find an account you don't recognize, that could be a sign of identity theft. You have the right to dispute credit report information you believe to be incorrect.
Accessing your own credit report will never hurt your score. You can get a free credit report from each of the consumer credit bureaus (Experian, TransUnion and Equifax) at AnnualCreditReport.com.
It's also important to regularly check your credit score for changes so you can swoop in quickly if it drops. When you get your credit score, you'll typically see risk factors listed, which point to areas you can focus on improving. There are multiple ways to get access to your credit score. For example, Experian offers free access to your FICO® Score, used by 90% of top lenders.
Learn more: What Is the Average Credit Score in the U.S.?
The Bottom Line
The work doesn't end once you've built a good credit score. Preserving it is a lifelong journey that will have huge benefits, from saving you money and stress during the mortgage process to giving you access to premium credit card rewards. Keep up the good financial behavior you learned while building your score, and the perks will make the effort worthwhile.
What makes a good FICO® Score?
Learn what it takes to achieve a good credit score. Review your FICO® Score for free and see what’s helping and hurting your score.
Get your FICO® ScoreNo credit card required

About the author

Brianna McGurran
Brianna McGurran is a freelance journalist and writing teacher based in Brooklyn, New York. Most recently, she was a staff writer and spokesperson at the personal finance website NerdWallet, where she wrote "Ask Brianna," a financial advice column syndicated by the Associated Press.
Read more from Brianna