What Is a Co-Branded Credit Card?


Quick Answer
Companies and brands partner with credit card issuers to offer co-branded credit cards to customers. You can use one of these cards—such as an airline or store card—to get extra rewards or benefits from the brand.
A co-branded credit card is the result of a deal between a credit card issuer and a non-credit card brand. Common examples include store credit cards, airline credit cards and hotel credit cards.
Co-branded credit cards encourage brand loyalty, but they also offer perks to the cardholder. With a co-branded credit card, you might earn extra rewards, exclusive perks or elevated status with that company's loyalty program. Purchases outside the branded network, though, may not earn the best rewards.
What Is a Co-Branded Credit Card?
A co-branded credit card combines typical credit card features with additional brand-specific perks to encourage you to shop at a particular retailer.
Co-branded credit cards offer perks to cardholders, but they also benefit the brand by encouraging brand loyalty. For example, if you're a die-hard Costco shopper, you might get a card from a credit card issuer (Visa, for example) that's co-branded with Costco. With elevated rewards at Costco, you'd earn more cash back every time you shop there, and the retailer would benefit from your continued loyalty.
Learn more: What Is a Credit Card and How Does It Work?
Best credit cards of 2026
Compare cards from our partners with intro bonuses, cash back or points offers, and annual fees as low as $0.
Offers from our partners

Blue Cash Everyday® Card from American Express
Intro APR:0% on Purchases and Balance Transfers for 15 months
Ongoing APR:19.74%-28.74% Variable
Annual Fee:$0

Revel® Platinum Mastercard®
Ongoing APR:35.90% Fixed
Annual Fee:$49 - $125
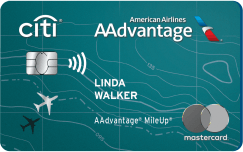
American Airlines AAdvantage® MileUp® Card
Intro APR:0% for 15 months on Balance Transfers
Ongoing APR:19.74% - 29.74% (Variable)
Annual Fee:$0
First Progress Select Secured Mastercard® Cash Back Rewards
Ongoing APR:17.74% Variable
Annual Fee:$39

Delta SkyMiles® Reserve American Express Card
Ongoing APR:19.74%-28.74% Variable
Annual Fee:$650

Delta SkyMiles® Platinum American Express Card
Ongoing APR:19.74%-28.74% Variable
Annual Fee:$350
cashRewards Credit Card
Ongoing APR:10.65% - 18% Variable
Annual Fee:$0
Bank of America® Customized Cash Rewards secured credit card
Ongoing APR:See Terms
Annual Fee:$0
See all our best credit cards for 2026.
How Does a Co-Branded Credit Card Work?
Most co-branded cards work just like other credit cards. As with other credit cards, you receive a credit limit when you're approved for a card, and you can borrow up to this limit each billing cycle. When your account comes due each month, you'll have to make at least a minimum payment. Or, if you pay your balance in full, you can use your card to finance purchases without accruing interest.
While the basics are the same, co-branded cards stand out for their brand-specific rewards and benefits. Here's a closer look at some common features of co-branded credit cards:
Closed- vs. Open-Loop
One important aspect of a co-branded credit card is whether it's an open-loop or a closed-loop card.
- Open-loop: Open-loop co-branded credit cards allow you to shop anywhere your card issuer is accepted. If you have a co-branded United Airlines card that's open-loop, you can use it to purchase tickets from United, but also anywhere else.
- Closed-loop: Closed-loop cards limit you to a particular retailer or chain of stores. For example, the Target Circle credit card is only accepted at Target stores and on Target's website.
Some brands also offer both closed- and open-loop cards. It might be easier to qualify for the closed-loop card, but consider the cards' benefits and how you plan to use the card before applying.
Rewards and Earnings Structure
With many co-branded credit cards, you can earn additional points per dollar spent on certain purchases made from that brand.
Example: You may earn 5% in rewards on purchases at a card's partner brand but 1.5% on everything else.
Signup and Ongoing Bonuses
Like some regular credit cards, co-branded cards may offer signup and ongoing bonuses. This is common with airline credit cards, where you may earn sign-up bonuses of thousands or tens of thousands of miles if you meet specific spending requirements in a certain time frame after opening your account.
Brand-Specific Perks
Co-branded cards often provide the same types of purchase protections, benefits and insurance that are commonly found on all credit cards, such as zero liability for unauthorized purchases. But in addition to these standard perks, co-branded cards may offer benefits that are brand-specific, such as credit toward elite status in the brand's loyalty program. Here are some other examples of brand-specific perks co-branded cards may offer:
- Airline cards: Free checked bags, priority boarding
- Hotel cards: Free breakfast, room upgrades
- Store cards: Free shipping, exclusive sales
Learn more: Credit Card Protections and Insurance Trends
Pros and Cons of Co-Branded Credit Cards
Co-branded credit cards aren't short on flashy perks, but do your homework before applying. These cards can have some disadvantages that are worth weighing against potential rewards:
Pros
-
Status in loyalty programs: Certain brands, such as hotels or airlines, offer ways to earn what's known as "elite status" in their loyalty programs. Some co-branded cards offer a leg up on earning elite status.
-
Bonus rewards: Most co-branded cards offer bonus rewards when you spend with their brand. This means you can earn more rewards—whether that's cash back, points or miles—with the shopping you're already doing.
-
Extra benefits: Co-branded cards may offer additional benefits—some that are specific to their brand and others that apply to any purchase. For example, an airline co-branded card may offer free checked bags when you fly on that airline. But it also may waive foreign transaction fees for any purchase made in another country.
-
Accessibility: Some co-branded cards may be easier to qualify for than regular credit cards or rewards cards. If you have trouble qualifying for other cards and need a way to build credit, a co-branded card could help—if you use it responsibly.
Cons
-
Higher interest rates: Co-branded cards can have higher interest rates compared to standard cards. An estimated 90% of retail cards have a maximum annual percentage rate (APR) above 30% (compared to only 38% of non-retail credit cards), according to the Consumer Financial Protection Bureau (CFPB).
-
Spending limitations: With a closed-loop card, you can only use it at the branded retailer. This may limit your ability to earn rewards and shop around for the best deals.
-
Limited reward potential: Often, co-branded credit cards reward you for shopping at their store with higher cash back rates, but earnings on other purchases are mediocre. This can limit your overall reward earnings if you're using your co-branded card for all of your purchases.
-
Potential overspending: Earning perks and rewards can feel good, especially when you think you're getting a deal. But when you spend more than you want to on things you don't need, co-branded cards can land you in debt.
Learn more: Are Credit Card Rewards Worth It?
Should You Get a Co-Branded Credit Card?
Co-branded credit cards can reel you in with exclusive deals, and you can often apply for them on the spot—for instance, during checkout or even mid-flight. While it may be tempting to save money upfront or take advantage of a limited-time offer, consider how applying for a new credit card will affect your credit scores.
You should also think about whether having a co-branded card might encourage you to overspend. Unfortunately, it can be easy to get carried away and, potentially, end up in credit card debt.
However, if you're a responsible credit card user, there are a few scenarios in which getting a co-branded card might make sense:
- You do the majority of your shopping at one store and want to maximize your rewards with that store's loyalty program.
- You want to save money on specific purchases, such as getting free checked bags when you buy an airline ticket.
- You want to take advantage of the card's benefits—such as free airport lounge access or an annual hotel night voucher—and you've done the math to make sure the monetary cost of those benefits outweighs any annual fee.
If you do decide to apply for a co-branded card, review the current welcome bonus offers for new cardholders. Sometimes you can get a coupon for your next purchase or bonus rewards if you meet certain requirements.
Frequently Asked Questions
Check Your Credit Score Before Applying for a Co-Branded Credit Card
Your credit history and credit scores can affect your eligibility for a new credit card, including co-branded credit cards. Check your FICO® ScoreΘ for free to see where you stand and to get tips on how to improve your score. You can also compare credit card offers, including co-branded credit cards, based on your unique credit profile with Experian.
Limited-time offer. Elevate every Hilton stay.
Unlock a world of elevated travel with the Hilton Honors American Express Aspire Card. Earn 200,000 Hilton Honors Bonus Points after you spend $6,000 in purchases within the first 6 months of Card Membership and enjoy premium benefits that make every stay more rewarding. Offer ends 01/13/27. Terms apply.
On American Express’ website
Powered by